


How Conference Presentation Will Impact Ingevity Stock Investors
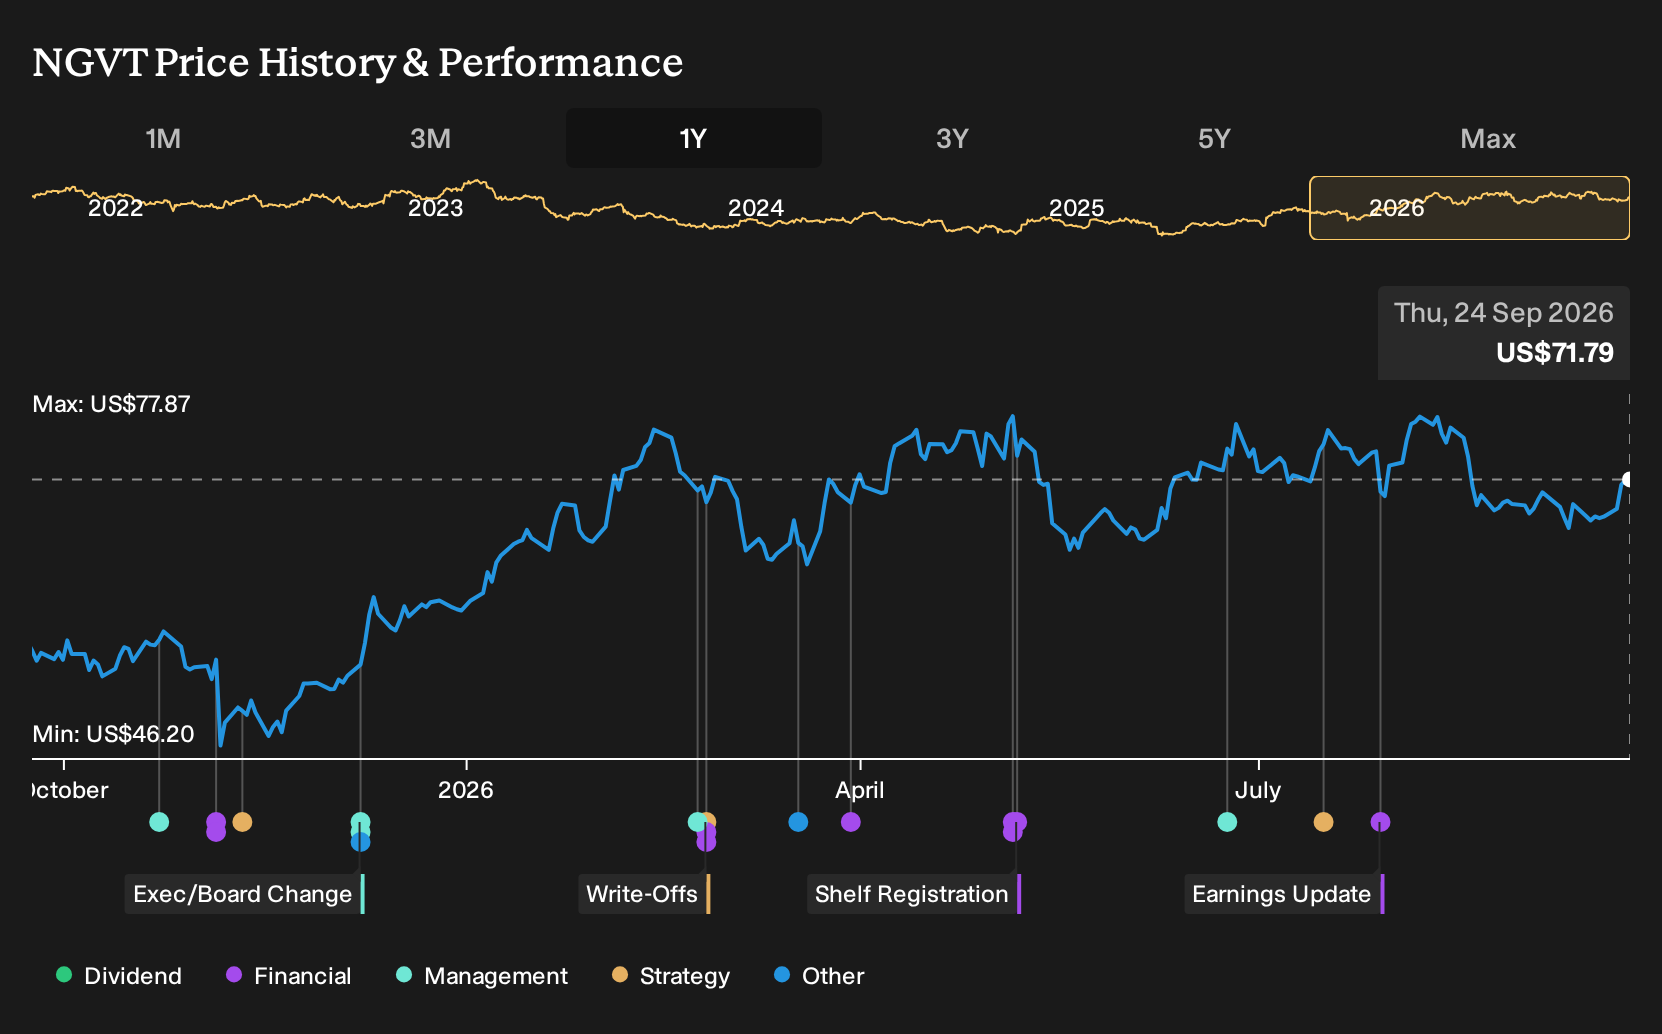
- Ingevity recently appeared at the Water Tower Research Virtual Insights Conference on September 23, 2026, where it outlined its portfolio repositioning and specialty chemicals focus.
- The presentation placed additional emphasis on how Ingevity is reallocating capital toward higher-growth, sustainability-linked areas such as EV battery materials through its partnership with Nexeon.
- We will examine how Ingevity's investment narrative is being shaped by its EV battery materials initiative, as highlighted at the recent research conference.
Scan for other specialty chemicals and EV supply chain opportunities that could echo Ingevity's repositioning story with the hand picked 84 AI infrastructure stocks.
Ingevity Investment Narrative Recap
To own Ingevity, you need to be comfortable with a chemicals business in the middle of a reset. Management is leaning into higher value specialty applications while dealing with weaker global industrial demand, tariff noise and pressure in Advanced Polymer Technologies after a large goodwill write down. The near term swing factor is execution on this portfolio shift and cost work. The main risk is that softer volumes and tariff related demand issues persist long enough to keep EBITDA margins stuck in the guided 15% to 20% range in APT.
The Water Tower Research appearance does not change that core equation by itself. It mainly reinforces what is already underway, including efforts to streamline the footprint and reweight capital toward Performance Materials and higher return specialty projects. Debt coverage from operating cash flow remains a watchpoint, especially while legacy segments face cyclical end markets like auto, footwear and broader industrials that can turn quickly.
The conference spotlight on Ingevity’s EV battery materials work with Nexeon is the most relevant recent update for this story. Management is committing meaningful R&D and partnership energy to engineered additives tied to sustainability themes, including materials for electric vehicle batteries and process purification. For investors, the key question is not the concept. It is whether this new product set can become meaningful enough to offset pressure in legacy lines and lower margin industrial specialties through the cycle.
This initiative sits alongside other catalysts already in motion, such as planned divestitures of the Industrial Specialties business and the CTO refinery, plus efforts to streamline manufacturing and maintenance capital spending. Together, those moves aim to tilt the mix toward higher margin specialty chemistry and improve free cash flow resilience over time. Execution risk remains real, especially with debt not well covered by operating cash flow today and competitive pressure still evident in APT pricing, so the EV materials push should be viewed as one component of a broader repositioning rather than a standalone fix.
Ingevity earnings and revenue assumptions behind the EV story
Analysts are effectively asking investors to evaluate Ingevity as a turnaround linked to both portfolio cleanup and the EV battery push, rather than as a straightforward growth story. The current consensus assumes revenue will decline by 1.4% a year over the next three years. At the same time, earnings are projected to shift from a loss of $156.0 million today to a profit of $350.3 million by 2029, with margins moving from 13.2% in the red to 31.0%. This represents a very large increase in profitability, supported by a higher mix of specialty projects such as battery materials and by a shrinking share count that analysts estimate will fall 4.65% annually. To align with that view, investors would also need to be comfortable with the stock eventually trading on a 9.7x P/E multiple on those forecast profits, compared with a negative multiple today because of the loss.
Ingevity's narrative incorporates projections of $1.1 billion in revenue and $350.3 million in earnings by 2029. This scenario assumes revenue will decline 1.4% per year and earnings will rise by about $506 million from the current loss of $156.0 million.
Uncover how Ingevity's fair value indicates a 24% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band from US$89 to about US$169 per share, which shows how far apart retail opinions on Ingevity sit today. That spread reflects real business risk around APT tariffs and cyclical demand. Consider it a prompt to compare multiple viewpoints before leaning on any single narrative.
Explore another Ingevity fair value estimate, including one that suggests it could be worth just $89.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Ingevity research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ingevity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingevity's overall financial health at a glance.
Looking for more investment ideas beyond Ingevity?
Once you have a handle on Ingevity, it can help to widen the lens and compare it with other businesses that match your preferred mix of quality, risk and income potential using the Simply Wall St Screener.
- If capital preservation is high on your list, scan for companies that score well on resilience and balance sheet strength with the 31 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, sort through candidates that combine solid fundamentals with appealing valuations using the 16 high quality undiscovered gems.
- If dependable income matters most, filter for companies with more robust payout profiles and higher yields through the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com