


Butterfly Network (BFLY) Could Be 12% Undervalued Following Needham Coverage And Merge Labs Deal
Butterfly Network stock reacts to coverage initiation and licensing deal
Butterfly Network (BFLY) jumped 22% on heavy trading after Needham began covering the stock with a Buy recommendation, alongside news of a multi-year Butterfly Embedded licensing agreement with Merge Labs.
For anyone tracking Butterfly Network over more than a single session, the latest jump lands on top of a 7-day share price return of 18.22% and a year-to-date share price gain of 150.93%. The 1-year total shareholder return of 380.10% points to strong momentum, which contrasts with a weak 5-year total shareholder return that is slightly below break-even.
Scan how Butterfly Network fits into the broader move in healthcare and AI imaging by comparing it with 38 healthcare AI stocks positioned around similar catalysts and licensing momentum.
Butterfly Network now has a handheld ultrasound business showing revenue growth alongside fresh AI licensing buzz. After a move like this, is the stock still a sensible entry point or already pricing in that promise?
Most Popular Narrative: 12% Undervalued
Butterfly Network’s most followed valuation story pegs fair value at $10.67 per share, which sits above the last close of $9.41 and frames the current move as a catch-up rather than an outlier.
Ongoing advances in semiconductor manufacturing, new product launches (e.g., iQ Station and upcoming fourth-generation P5 technology), and cost containment efforts are driving product miniaturization and lower production costs. This supports higher gross margins and a credible path to sustainable profitability at scale as portable imaging adoption accelerates globally.
See why 35 investors see Butterfly Network as 12% undervalued.
Result: Fair Value of $10.67 (UNDERVALUED)
Still, Butterfly Network’s story can break if large enterprise deals stall or if continued heavy R&D spend keeps losses wide for longer than analysts expect.
Find out about the key risks to this Butterfly Network narrative.
Another View: Butterfly Network looks expensive on sales multiples
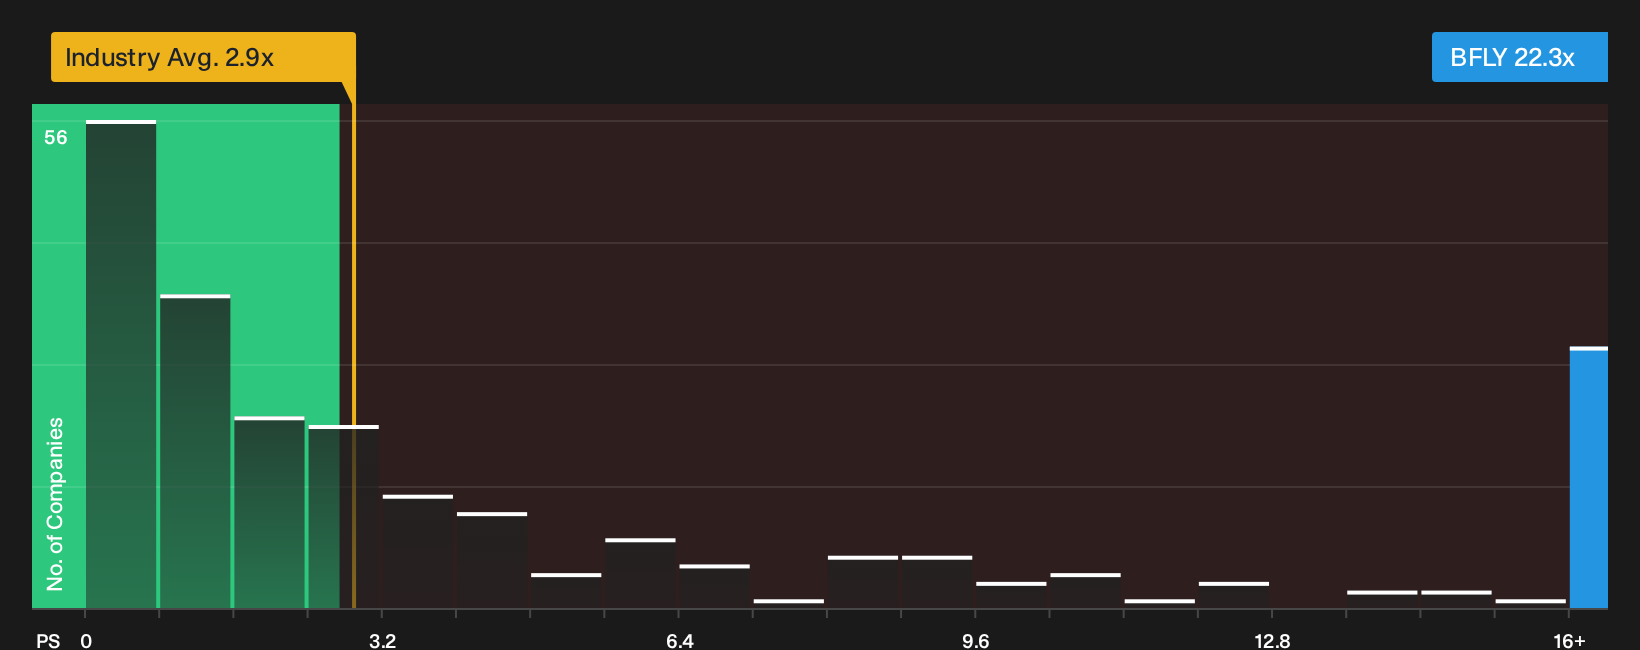
While the popular narrative frames Butterfly Network as 12% undervalued on a fair value of $10.67, the current P/S of 22.3x tells a different story. The wider US Medical Equipment group sits at 2.9x, and a fair ratio of 6x suggests meaningful valuation risk if sentiment cools.
For a closer look at what the market is pricing into that sales multiple, and how it compares with peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Butterfly Network so far. If you want to move quickly and reach your own call on the tension between risk and upside, start by weighing the 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Butterfly Network?
Do not stop with Butterfly Network alone. Use the Simply Wall Street Screener to surface more focused ideas that fit your style and risk comfort.
- Target long term compounding potential by scanning for quality companies trading below their estimated worth through the 30 high quality undervalued stocks.
- Identify income focused ideas by reviewing resilient payers filtered via the 7 dividend fortresses.
- Dial down portfolio stress by concentrating on sturdier businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com