


3 AI Stocks Trading Up To 61% Below Fair Value
Global bond markets are being shaken by rising government debt costs, with interest payments now rivaling spending on AI itself. That paradox creates an opening for investors. While many focus on higher yields and policy risk, some AI linked businesses quietly trade at prices that do not fully reflect their role in powering the ChatGPT era. This article highlights three such undervalued AI stocks from our screener.
The three stocks covered below are only a sample from this theme. The full screen surfaced 47 more AI focused businesses with equally compelling narratives around semiconductors, cloud infrastructure and software that are not discussed here.
If you want to identify your own highest conviction ideas across this space, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener to filter, analyze and focus on the AI opportunities that best match your approach.
Adobe (ADBE)
Overview: Adobe Inc. is a global software company that powers creative, marketing and document workflows, now deeply embedding generative AI into its Creative Cloud and Experience Cloud platforms.
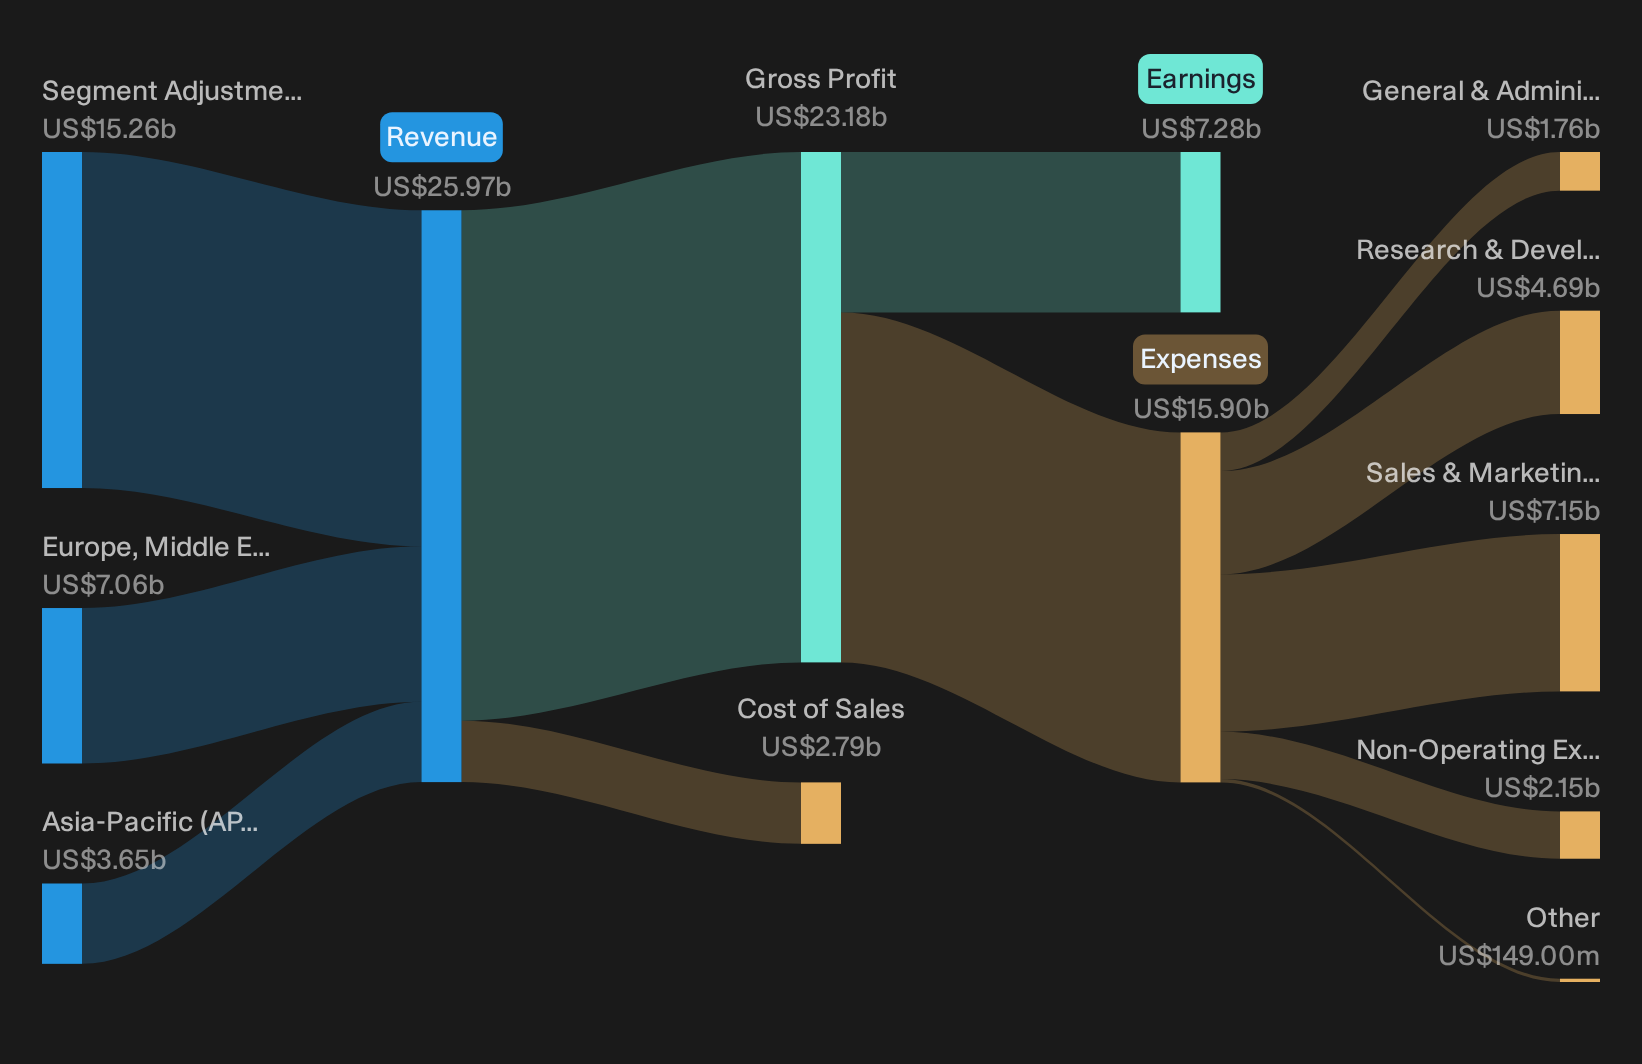
Operations: Adobe reports revenue globally, with about US$7.1b from EMEA and US$3.6b from Asia-Pacific, alongside a large segment adjustment item.
Market Cap: US$93.7b
Adobe matters for this AI screener because it owns the creative and customer experience tools that many ChatGPT era workflows already run through, and its generative products turn that footprint into a direct way to charge for AI usage rather than just offering another set of experimental tools.
"As professionals integrate AI into their daily workflows, their credit usage increases. When they hit the limits of their current plan, the path of least resistance is to upgrade to a higher Creative Cloud tier or purchase a credit pack, thereby driving Average Revenue Per User (ARPU) expansion."
What really affects the long term AI opportunity for Adobe is how one quiet pressure on its profitability curve ultimately resolves.
That pressure point is exactly where the full narrative for Adobe shows whether Adobe’s AI driven ARPU engine can keep accelerating while the cost curve quietly decouples.
Salesforce (CRM)
Overview: Salesforce provides cloud based customer relationship tools and AI powered Agentforce platforms that embed large language model agents directly into CRM workflows.
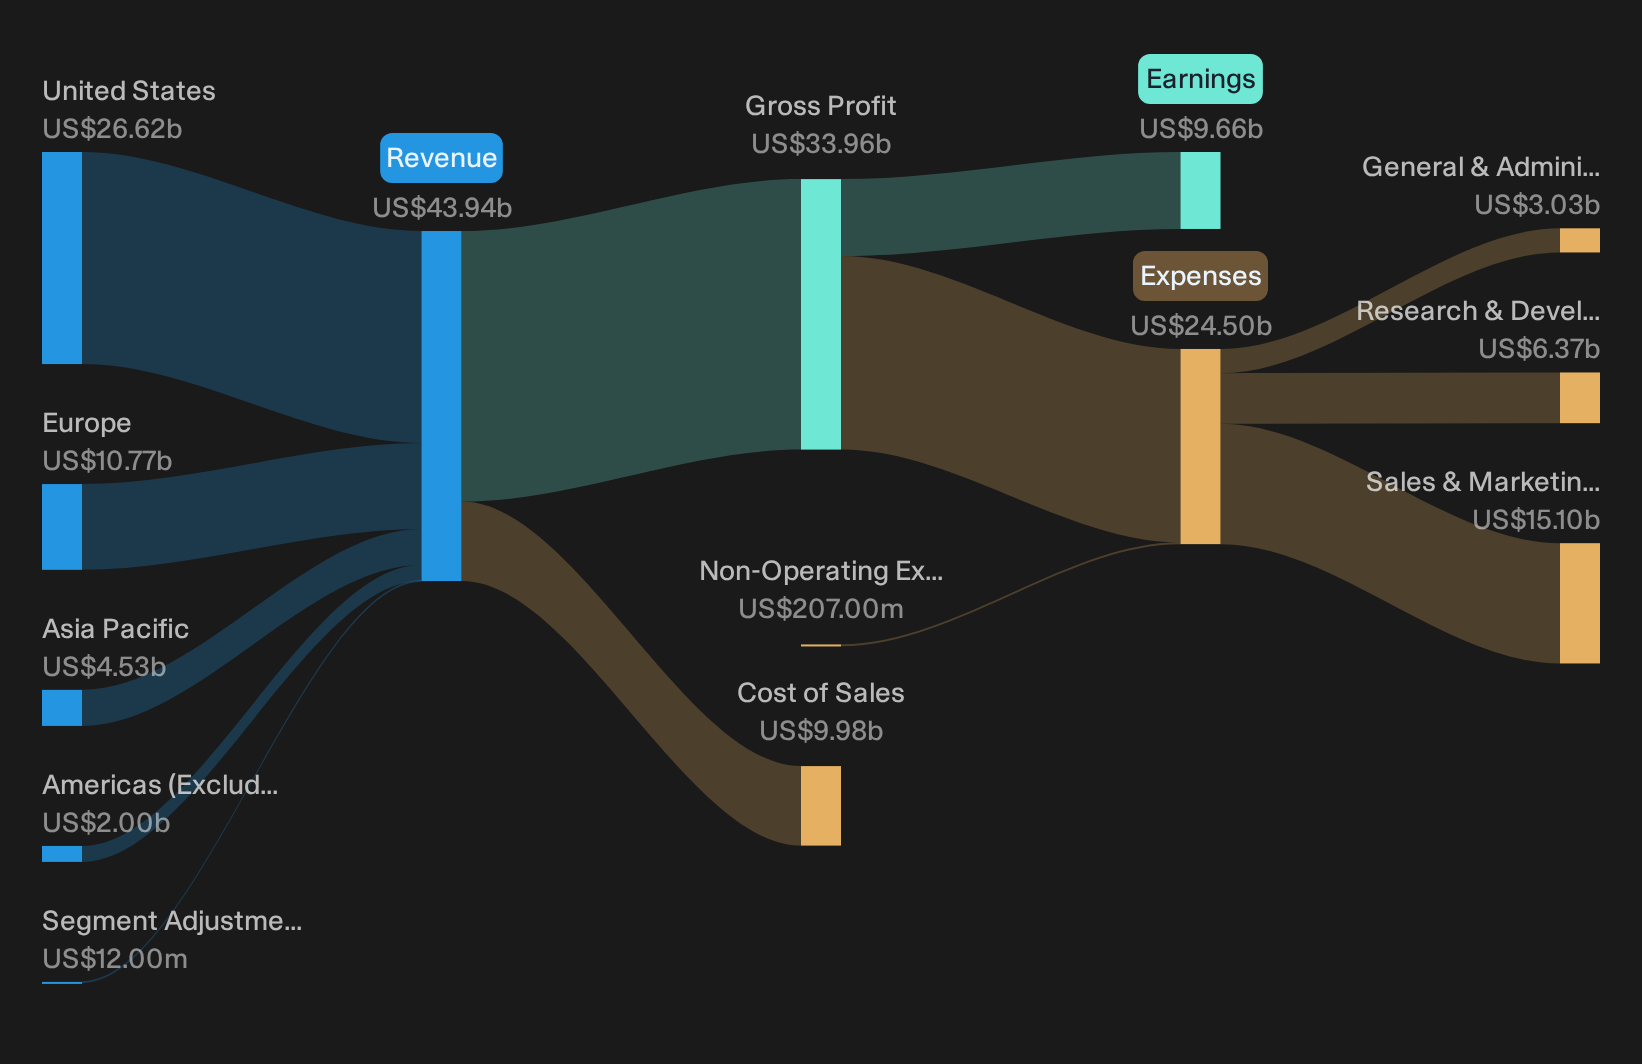
Operations: Salesforce generates about US$43.9b from a single enterprise cloud computing segment, with most revenue coming from the United States and Europe.
Market Cap: US$195.5b
Salesforce is included in this AI screen because Agentforce turns its CRM footprint into a place where autonomous agents and large language models directly handle day to day customer, sales and support work.
"Salesforce's ongoing integration of AI and agent-based automation (Agentforce, Data Cloud) into its product suite is contributing to adoption, with 40% of new agentic bookings reportedly coming from existing customers expanding usage, and reported triple-digit growth in Data Cloud and AI ARR."
A key consideration for Salesforce is whether that AI driven shift in how work gets done ultimately widens margins to the degree the market currently anticipates.
Whether that margin story widens or stalls, the full narrative for Salesforce shows how Salesforce’s AI engine, churn risks and competitive pressure really fit together beneath the headline numbers.
Broadcom (AVGO)
Overview: Broadcom builds semiconductor hardware and infrastructure software that power high performance AI data center networking, storage acceleration, and private cloud platforms.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions, including AI focused networking and custom silicon, and US$29.7b from Infrastructure Software.
Market Cap: US$1,694.6b
Broadcom matters for this AI screener because its high performance networking chips, custom accelerators and connectivity hardware are the plumbing that lets ChatGPT scale from a clever demo into a global service used by millions.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The main variable to watch is how hyperscaler appetite for ever denser AI compute clusters holds up once the first wave of data center buildouts reaches capacity limits.
Once that buildout hits its first ceiling, the full narrative for Broadcom shows how Broadcom’s AI plumbing, contract depth and capital returns story could keep accelerating beyond today’s data center cycle.

Seeking Fresh Alternatives Beyond AI?
Fresh opportunities rarely stay under the radar for long. Momentum can shift fast, and early data goes stale before the crowd catches it. Scan these ideas and consider your options.
- Identify established cash generators that could fund future initiatives by filtering for resilient balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Track where capital may move next by scanning curated 21 cryptocurrency and blockchain stocks with real operating businesses behind the ticker symbols.
- Look for potential momentum before headlines catch up by focusing on curated 31 resilient stocks with low risk scores that pair stability with controlled downside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com