


How Investors May Respond To LTC Properties (LTC) Dividend Sustainability Concerns
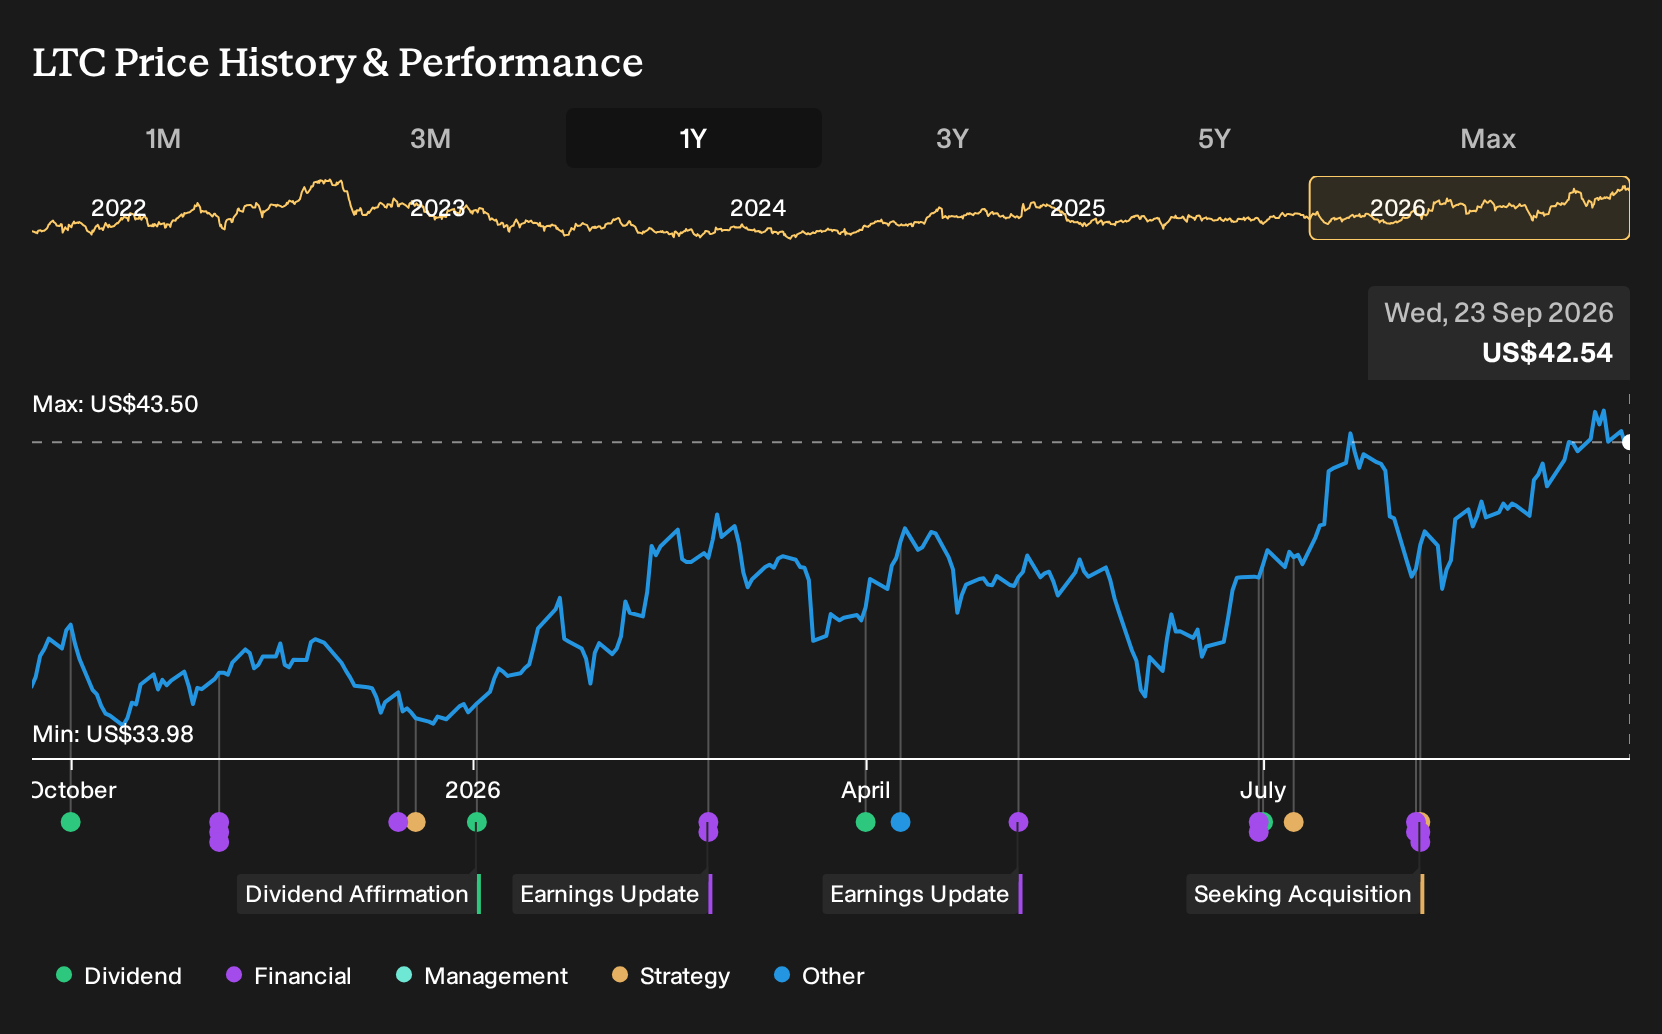
- LTC Properties has paid a total dividend of $0.19 per share with an ex dividend date of 22 September 2026 and a reported forward yield of 5.31% alongside a dividend payout ratio of 1.32.
- The combination of a relatively high forward yield and a payout ratio above 1.0 raises practical questions about how LTC Properties balances dividend commitments with reinvestment needs in senior housing and health care assets.
- We will now look at how LTC Properties' elevated payout ratio could influence the existing investment narrative around its dividend capacity.
Scan beyond LTC Properties to compare its 5.31% forward yield and payout risk profile with a hand picked group of 7 dividend fortresses.
LTC Properties Investment Narrative Recap
To own LTC Properties, you need to be comfortable with a seniors housing and health care landlord that leans heavily on its dividend story while juggling growth plans, acquisition funding, and operator health. The key near term swing factor is how effectively management recycles capital into newer SHOP and triple net assets that support cash flow, given rising funding costs and tenant concentration risk.
The latest US$0.19 per share dividend with a 5.31% forward yield and a 1.32 payout ratio does not fundamentally change that equation in the short term. It does, however, sharpen focus on interest cover, the use of higher risk funding, and whether future external investment or shareholder dilution becomes the bigger pressure point for the business.
Among recent developments, the most relevant piece of information for this dividend event is the elevated payout ratio tied to earnings that include large one off items. Earnings reportedly grew 63.2% over the past year, helped by an US$87.2m gain that flatters payout metrics and makes dividend coverage look healthier than underlying recurring cash generation alone might support.
Set that against forecasts that revenue could grow 35.6% per year while earnings are expected to decline on average 9.9% annually over the next three years, and the US$0.19 payout looks more like a stress test of LTC Properties than a simple income headline. For readers, the catalyst to watch is how quickly management can convert forecast top line expansion into cleaner, interest covered cash flows that comfortably fund distributions without leaning on dilution or asset sales at awkward moments.
LTC Properties' current analyst narrative points to US$997.1 million of revenue and US$101.1 million of earnings by 2029, built on 43.2% yearly top line growth and an earnings decline of about US$33.6 million from the US$134.7 million reported today.
Uncover why LTC Properties' fair value indicates a 6% potential upside to its current price, which could close faster than many income focused investors expect.
Exploring Other Perspectives
Opinions inside the Simply Wall St Community span fair values from US$45 to about US$85 across three individual assessments, so you are looking at a wide spread of LTC Properties views. When you also consider risks like higher funding costs and intense bidding for senior housing assets, the gap between these valuations could matter for future execution. Readers should weigh these contrasting signals and explore several alternative viewpoints before leaning too heavily on any single fair value line.
Explore 2 other LTC Properties fair value estimates, including one that suggests as much as 100% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your LTC Properties research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for LTC Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LTC Properties' overall financial health at a glance.
Looking For More Ideas Beyond LTC Properties?
If the LTC Properties dividend story has you rethinking portfolio income and risk, casting a wider net across other companies can sharpen your sense of what feels attractive on yield, balance sheet strength, and long term resilience.
The Simply Wall St Screener lets you filter for specific traits so you can compare LTC Properties against a broader set of opportunities that match your own risk and income preferences.
- For investors who want income with fewer obvious weak spots, scan a curated group of 31 resilient stocks with low risk scores that pair resilience scores with measurable financial strength.
- If you care most about durability of cash flows, start with a list of solid balance sheet and fundamentals (23 results) so you can focus on businesses with stronger foundations behind their dividends and reinvestment plans.
- Those hunting for under the radar prospects can widen the opportunity set through a 16 high quality undiscovered gems that highlights quieter stories with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com