


Procter & Gamble (PG) Could Be 37% Overvalued On New Clinical Product Push
Procter & Gamble (PG) just pushed two of its biggest personal care franchises further into clinical territory, rolling out Head & Shoulders HydraZinc Complex shampoos and expanding the premium Oral-B iO electric toothbrush range.
For shareholders, these product launches land after a fairly muted stretch for Procter & Gamble, with the share price up 3.95% year to date but the 1-year total shareholder return fractionally down 0.46%. This points to steady but fading momentum as investors weigh near term earnings risks against longer term brand strength.
Find more clinically driven consumer staples like Procter & Gamble in our hand picked list of 31 resilient stocks with low risk scores that aim to pair brand strength with resilient fundamentals.
Procter & Gamble now trades with a modest year to date gain, a flat 1 year return, and fresh clinical launches in core categories. Does that mix still tip the risk reward balance toward buyers at today’s price?
Most Popular Narrative: 37% Overvalued
On the most widely followed valuation view, Procter & Gamble screens as significantly above its implied worth, with a fair value estimate of $107.52 versus a last close of $147.39. That gap is grounded in detailed assumptions about margins, reinvestment, and long run growth for this mature consumer brands group.
Despite this, I feel the future for this company still holds some friction by the appearance of fierce competition, pressuring Procter & Gamble to reduce its prices and by consequence its operating margins. Also, unless something exceptional happens, given the maturity of the business, I see its revenues grow below or at the economy growth rate.
See why 34 investors see Procter & Gamble as 37% overvalued.
Result: Fair Value of $107.52 (OVERVALUED)
Still, Procter & Gamble could see this 37% premium narrative challenged if consumer trade down pressures margins or if clinical style launches fail to sustain pricing power.
Find out about the key risks to this Procter & Gamble narrative.
Another View On Procter & Gamble’s Value
The user narrative pegs Procter & Gamble at around $107.52 per share, which points to a premium at the current $147.39 price. Our SWS DCF model lands in a very different place, with a future cash flow value of $196.96, which frames PG as trading at a discount instead.
This gap between a cash flow based estimate and a more conservative narrative fair value raises a practical question for investors. Is the market paying up for perceived resilience in Procter & Gamble, or is the long term cash generation still being priced too cautiously?
Look into how the SWS DCF model arrives at its fair value.
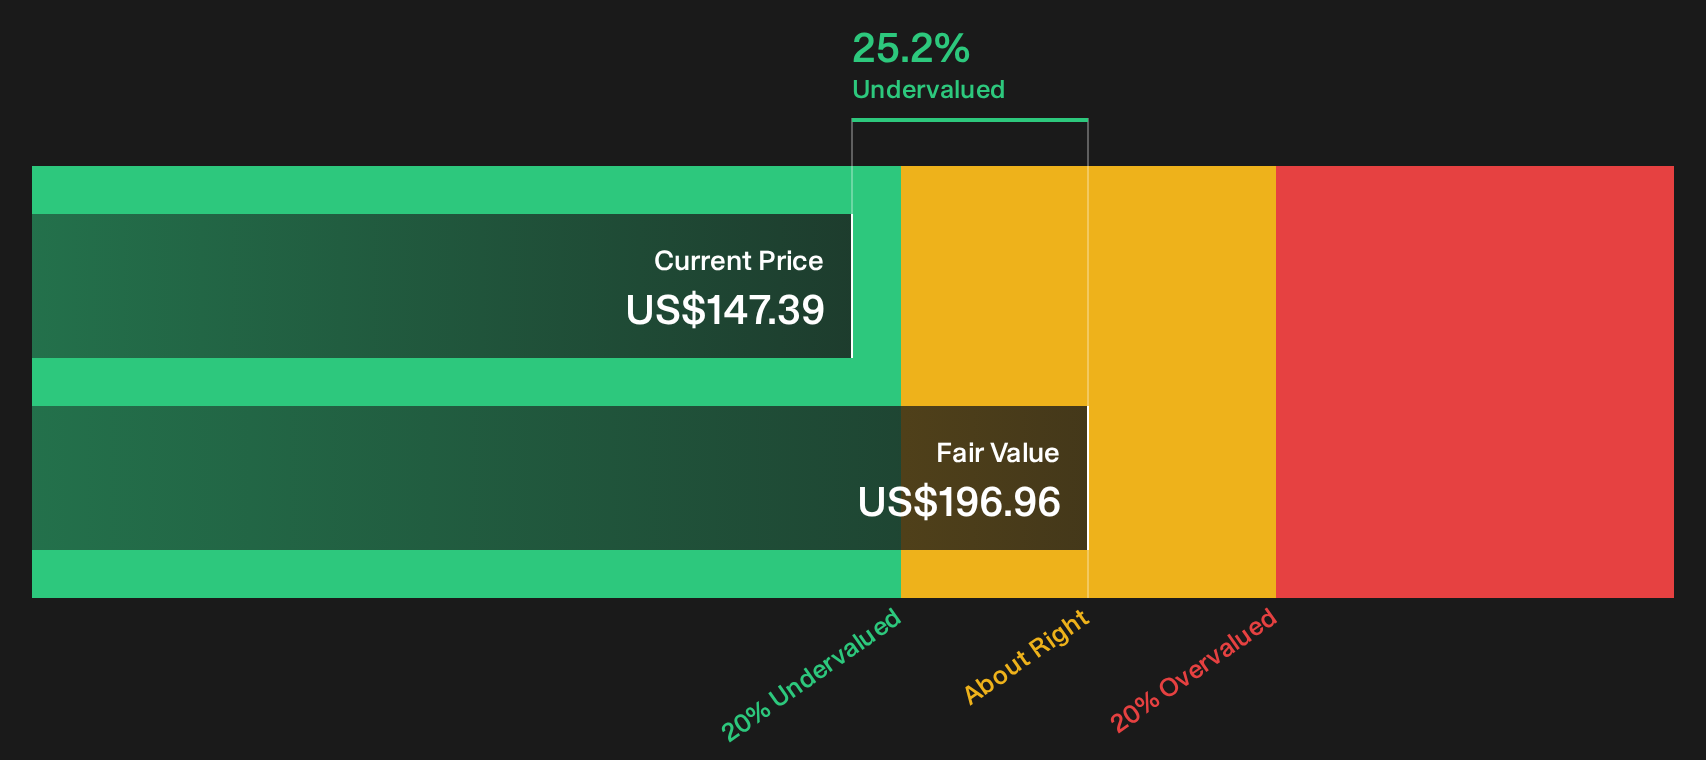
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Procter & Gamble for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Procter & Gamble’s valuation and outlook can create noise. Move quickly, review the full data set, and then weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Procter & Gamble?
If Procter & Gamble has you thinking more carefully about valuation, cash flows, and risk, use that momentum and hunt for other opportunities before they slip past you.
- Target resilient cash generators by scanning our 30 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their underlying strength.
- Hunt for reliable income by reviewing a curated set of 7 dividend fortresses that focus on robust payouts supported by underlying business quality.
- Zero in on financial strength by filtering for a list of solid balance sheet and fundamentals (23 results) so you can focus on businesses built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com