


Rollins (ROL) Missed On Profitability In Q2, Is The Stock Above Fair Value?
Rollins Q2 miss and conference spotlight
Rollins (ROL) is back in focus after Q2 results that missed analyst profitability expectations, followed by a U.S. All Stars Conference appearance where senior leadership addressed the pest control group’s recent performance.
Rollins’ share price has come under clear pressure, with the stock down 12.8% on a 30 day share price return and 24.1% over 90 days. The 1 year total shareholder return has declined 41.3% as investors digest the Q2 earnings miss and recent conference commentary.
Compare how Rollins stacks up against other service stocks under pressure and sift for potential rebound candidates using our curated 30 high quality undervalued stocks list.
After a Q2 miss and a slide that has reset Rollins closer to its recent lows, the key question is whether to step in now or wait for a cheaper entry as the valuation picture comes into focus.
Most Popular Narrative: 101% Overvalued
Rollins closed at $32.49, while the leading narrative fair value sits far lower at $16.20, which sets up a sharp valuation gap that investors now need to weigh against the business quality story.
Rollins is the dominant pure-play compounder in global pest control, a structurally necessary, recession-resistant service business that has grown revenue for 24 consecutive years and delivered ROIC of 23–31% for 12 consecutive years, without a single year of ROIC below 21% even through COVID-19. The investment thesis rests on three mutually reinforcing pillars: (1) a Wide Moat rooted in switching costs, commercial customers cannot switch providers without triggering compliance risk, and residential customers renew habitually at annual price increases of 3–4% above CPI without meaningful churn; (2) a proven M&A flywheel that converts a fragmented industry of 34,000+ U.S. operators into compounding route density and FCF, completing 30–45 bolt-on acquisitions annually at disciplined multiples with zero reported impairments; and (3) a capital-light business model with minimal reinvestment needs, generating FCF of $678M in FY2025 on $3.76B of revenue.
See why 8 investors see Rollins as 101% overvalued.
Result: Fair Value of $16.20 (OVERVALUED)
Still, the Rollins narrative could be tested if acquisition returns soften or if organic demand slows. This would challenge the high-quality premium investors are weighing.
Find out about the key risks to this Rollins narrative.
Another view on Rollins valuation
The community narrative calls Rollins 101% overvalued at $32.49 versus a $16.20 fair value. A very different picture comes from our DCF model, which puts future cash flow value at $59.13, implying the stock trades at a steep discount instead.
When two frameworks point in opposite directions, it raises a blunt question for investors: Which set of assumptions about Rollins do you actually trust enough to lean on when real money is at stake?
Look into how the SWS DCF model arrives at its fair value.
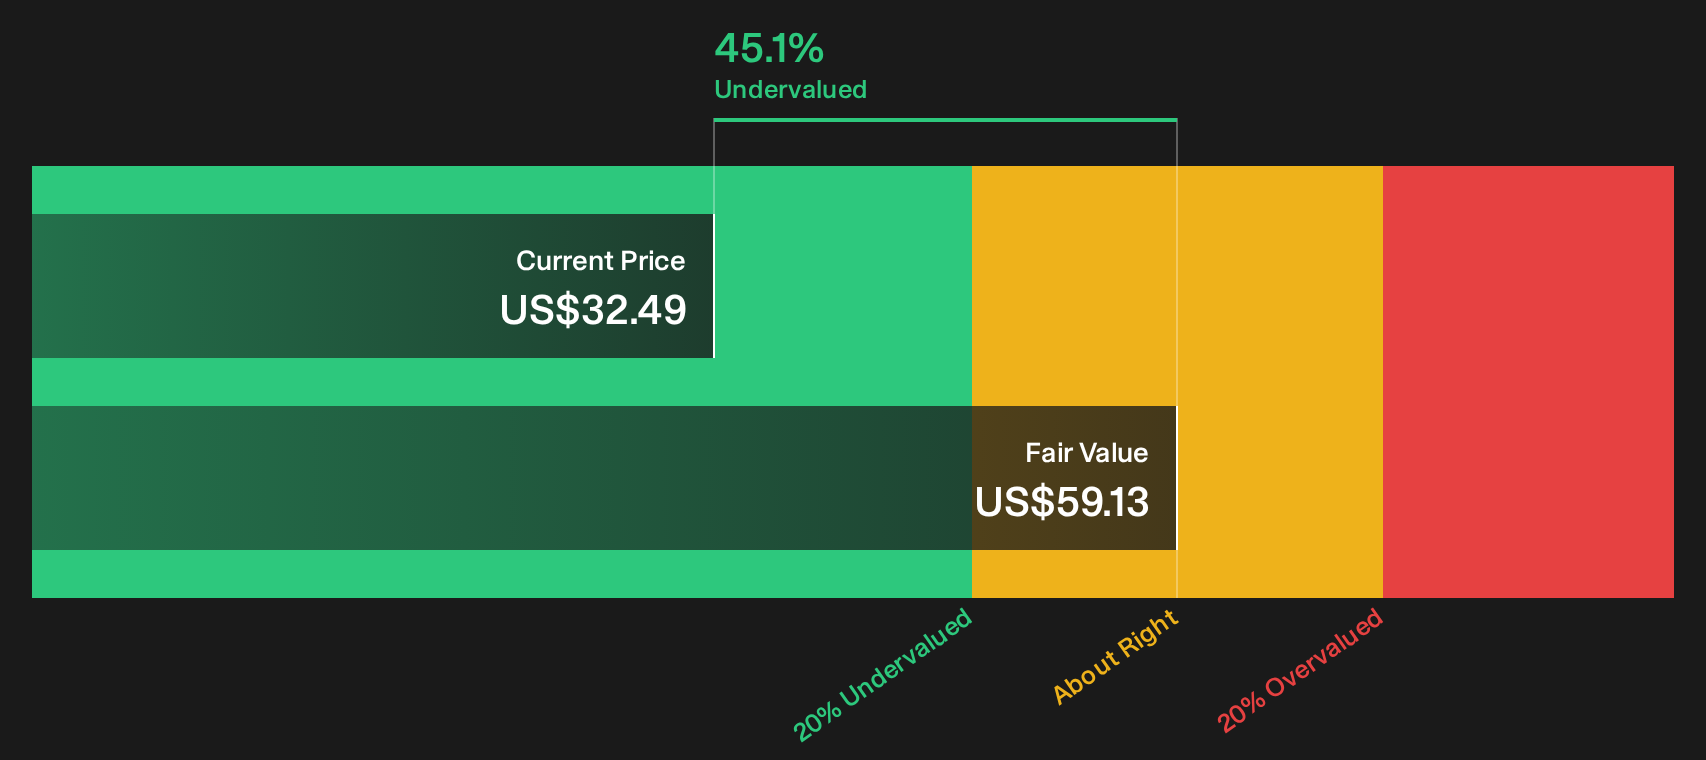
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rollins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Rollins now sits at the center of a tense debate, which means your edge comes from digging into the numbers yourself and not outsourcing conviction. Move quickly, review both the risks that worry investors and the rewards that keep others optimistic, and weigh them against your own expectations with 3 key rewards and 2 important warning signs
Looking for more Rollins sized investment ideas?
Before moving on from Rollins, give yourself a broader watchlist by scanning other opportunities on Simply Wall Street’s screener so you are not relying on a single story.
- Target resilience first by checking companies that have passed strict risk filters with the 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing the 16 high quality undiscovered gems that combine strong fundamentals with limited market attention.
- Focus on balance sheet strength by running through the list of solid balance sheet and fundamentals (23 results) that highlight financially robust businesses before they move.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com