


Reliance (RS) Rebrand Draws Fresh Attention, Is It Still Below Fair Value?
Reliance (RS) has drawn attention after its recent rebranding from Reliance Steel & Aluminum Co., with the Phoenix based metals provider now trading near $384 as investors reassess the diversified processing business.
Recent trading has been choppy, with the Reliance share price down over the past week and quarter, yet still showing a strong year to date share price return of 30.02% and a 5 year total shareholder return of 187.87%. This points to longer term momentum even as near term sentiment cools around the rebrand and metals demand outlook.
Scan beyond Reliance and compare how other metals and materials businesses with strong balance sheets and fundamentals have been behaving using this curated list of solid balance sheet and fundamentals (23 results).
Bulls point to Reliance’s long record of shareholder returns and recent rebrand as proof the metals processor still has room to run. Bears see a hot share price and mixed recent trading. Which side does current valuation support?
Most Popular Narrative: 6% Undervalued
Reliance last closed at $384.63, which sits below the most followed fair value estimate of $408.88 based on a 9.05% discount rate. That gap frames the entire debate around whether current projects and contracts are already fully factored into the share price.
The current numbers, including record tons sold, increased earnings guidance and management’s view that the stock is fairly valued, suggest that the share price already reflects meaningful success in infrastructure, government contracts and consolidation, with limited room for disappointment.
See why 6 investors see Reliance as 6% undervalued.
Result: Fair Value of $408.88 (UNDERVALUED)
Still, shifting tariffs on aluminum and higher LIFO expenses could pressure Reliance margins and unsettle the fair value case if costs remain volatile.
Find out about the key risks to this Reliance narrative.
Another View On Reliance’s Valuation
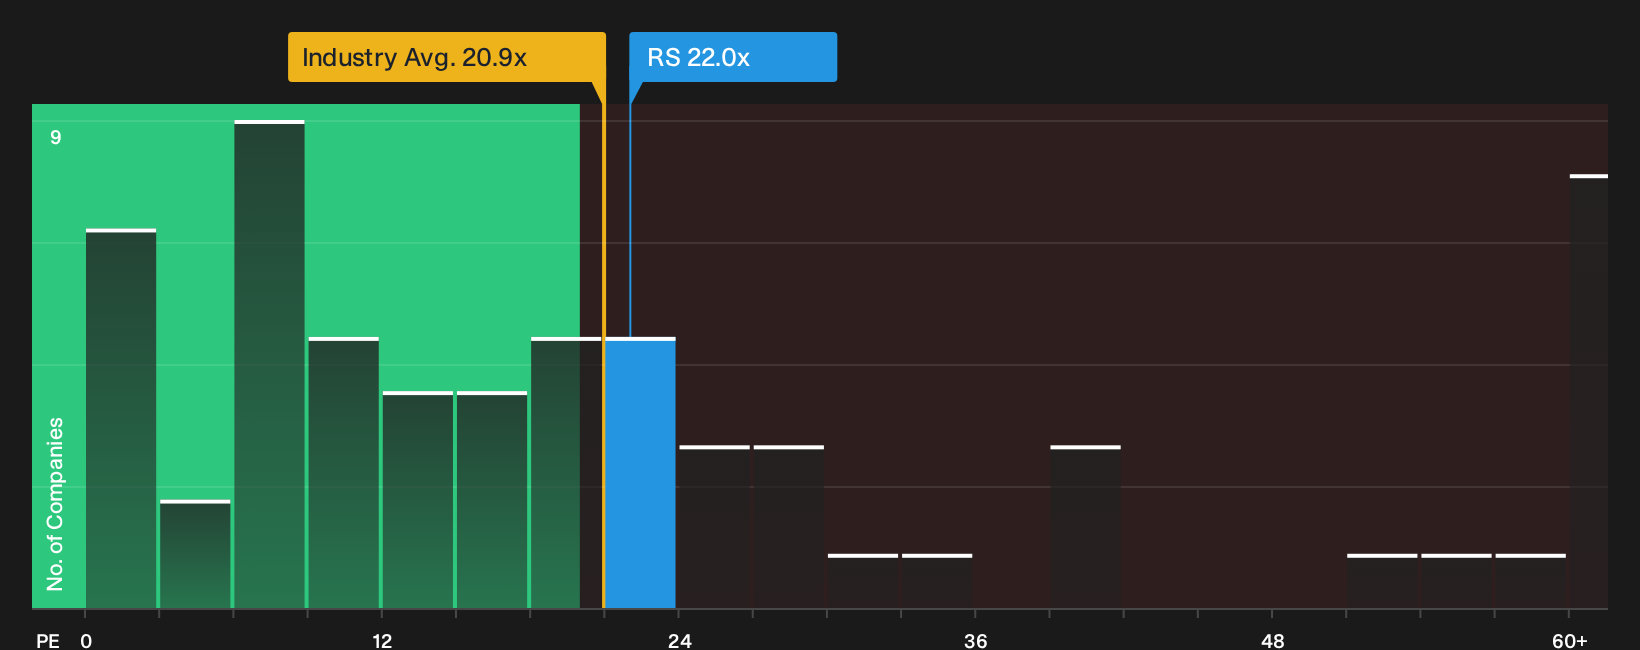
The first fair value story leans on long term earnings forecasts. A second lens, the P/E ratio, paints a tighter picture. Reliance trades around 22x earnings compared with 20.8x for the US Metals and Mining group and a fair ratio estimate of 19.4x, which implies less room for error if sentiment turns.
Numbers like that can still work for investors who believe Reliance will keep justifying a premium. The real question is whether you see that P/E gap as acceptable risk or a signal to demand a wider margin of safety, and what would change your mind if the industry multiple shifted again. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this mix of optimism and caution around Reliance, it helps to check the facts yourself and decide where you land on the risk reward line. To see both sides clearly, weigh the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Reliance?
Do not stop your research with Reliance. Broaden your watchlist with other opportunities that fit different risk, income, and value profiles using focused stock screens.
- Target potential bargains by scanning a curated set of companies that combine quality fundamentals with attractive pricing through the 30 high quality undervalued stocks.
- Build income potential into your portfolio by reviewing a focused group of higher yielding payers using the 7 dividend fortresses.
- Dial down portfolio stress by filtering for businesses with stronger financial resilience and robust fundamentals through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com