


Is Debt Refinancing Altering The Investment Case For Wynn Resorts (WYNN)?
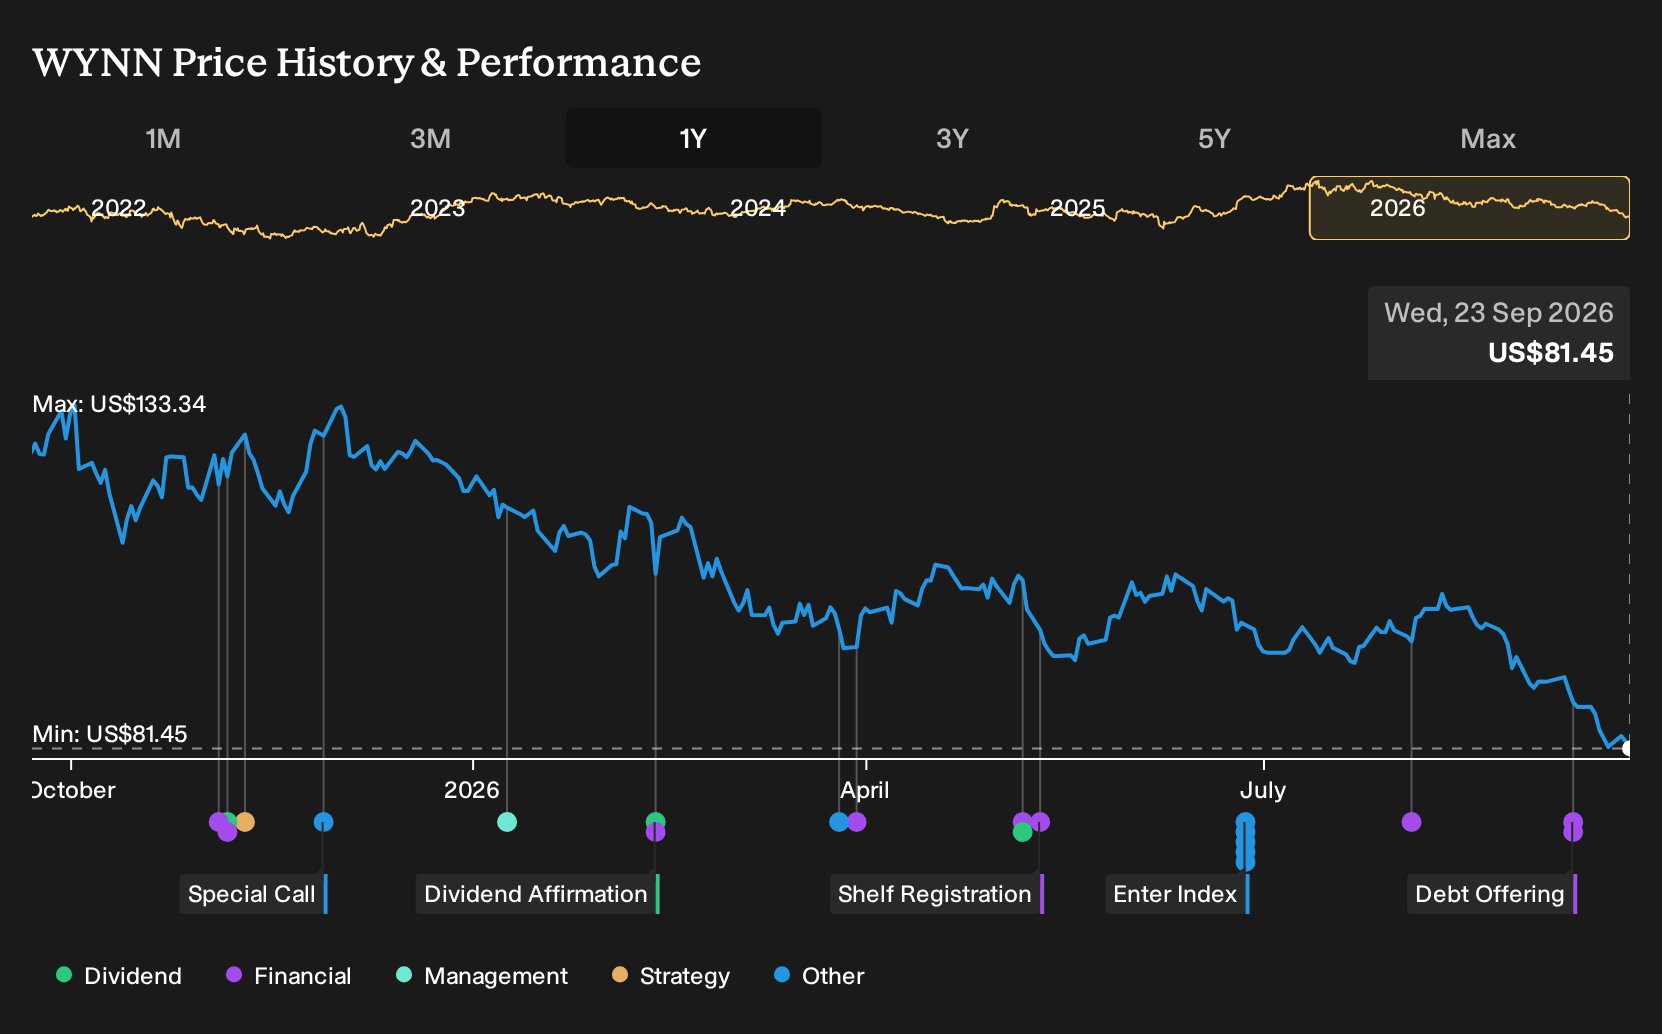
- Wynn Resorts subsidiaries recently issued US$900 million of 6.875% Senior Notes due 2035 to redeem 5.250% Senior Notes due 2027 and cover related costs.
- The refinancing shifts Wynn Resorts' debt profile toward longer maturities, which may influence funding flexibility for projects such as Wynn Al Marjan Island and the planned Wynn Palace all suite tower.
- We will now look at how Wynn Resorts' investment narrative is affected by this large 6.875% Senior Notes refinancing and the associated maturity extension.
Wynn Resorts Investment Narrative Recap
To own Wynn Resorts, you need to be comfortable with a high end, destination driven model that leans heavily on Macau, Las Vegas, Encore Boston Harbor and, over time, new geographies. The recent US$900 million 6.875% notes do not change the near term operational swing factor, which still sits in occupancy, gaming volumes and non gaming spend across these hubs.
The biggest short term catalyst remains execution on property refreshes and demand recovery through higher room rates, gaming activity and group business. The key risk stays the same: high fixed costs, meaningful leverage and negative shareholders' equity can pressure free cash flow if visitation or spend softens.
The refinancing announcement ties directly into the long dated investment program around Wynn Al Marjan Island and the planned all suite tower at Wynn Palace. Extending maturities to 2035 may give management more breathing room to keep construction and refurbishments moving while addressing the 2027 notes ahead of time.
For you as a shareholder, the question is simple: do the long term opportunities from a larger, affluent customer base in Asia and the Middle East compensate for interest costs that are not well covered by earnings today and a balance sheet built entirely on higher risk funding sources rather than deposits or low cost capital?
Wynn Resorts' current narrative centers on analysts modeling revenue growth of 7.5% a year, with earnings today of $448.9 million rising to a consensus of $582.4 million by 2029, which is an increase of about 30% in profit. Those same forecasts point to revenue of $9.2b and earnings of $582.4 million in 2029, based on a modest lift in profit margins and a future P/E multiple of 30.7x.
Uncover why Wynn Resorts' fair value indicates a 63% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternative view on Wynn Resorts leans hard into balance sheet risk. The most cautious analysts were only penciling in revenue of about US$7.9b and earnings of roughly US$495.6 million by 2029 before this refinancing, far below consensus. That group sees slower growth and higher financing strain, so opinions clearly vary.
Explore 3 other Wynn Resorts fair value estimates, including one that suggests it could be worth just $132.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Wynn Resorts research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wynn Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wynn Resorts' overall financial health at a glance.
Looking for more investment ideas beyond Wynn Resorts?
If the refinancing story at Wynn Resorts has you rethinking risk and reward, it can help to widen the lens and compare it with other opportunities across the market using the Simply Wall St Screener.
- For investors who want income that aims to keep working in the background, take a look at 7 dividend fortresses and see which stocks currently offer higher yields with robust payouts.
- If balance sheet strength matters most to you after reviewing Wynn Resorts, you can focus on capital preservation and funding resilience through our list of solid balance sheet and fundamentals (23 results).
- If you prefer to hunt for potential mispriced opportunities instead, where quality and valuation meet, then sort through the 30 high quality undervalued stocks and see which companies fit your checklist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com