


Hinge Health (HNGE) Stock Looks Above Fair Value As It Jumps 103% YTD
Hinge Health has delivered a sharp year to date gain, and the jump puts a spotlight on a simple question for investors who care about valuation. Is the current share price in line with what the company is earning today and what those earnings may reasonably support?
- The stock is up about 102.5% year to date, which raises the stakes on whether the current valuation can still be explained by its earnings profile.
- Recent commentary around Hinge Health has focused on rapid growth in musculoskeletal telemedicine and expanding profitability, which can influence how much weight investors place on its current earnings stream versus expectations for future profits.
- There is a second opinion on Hinge Health worth weighing. See what analysts think Hinge Health's shares could be worth.
The issue now is whether Hinge Health's current earnings are strong and resilient enough to justify where the stock trades today.
If you are weighing Hinge Health on its earnings, it can help to compare it with other businesses screened on similar fundamentals using 30 high quality undervalued stocks
Is Hinge Health Getting Expensive on Earnings?
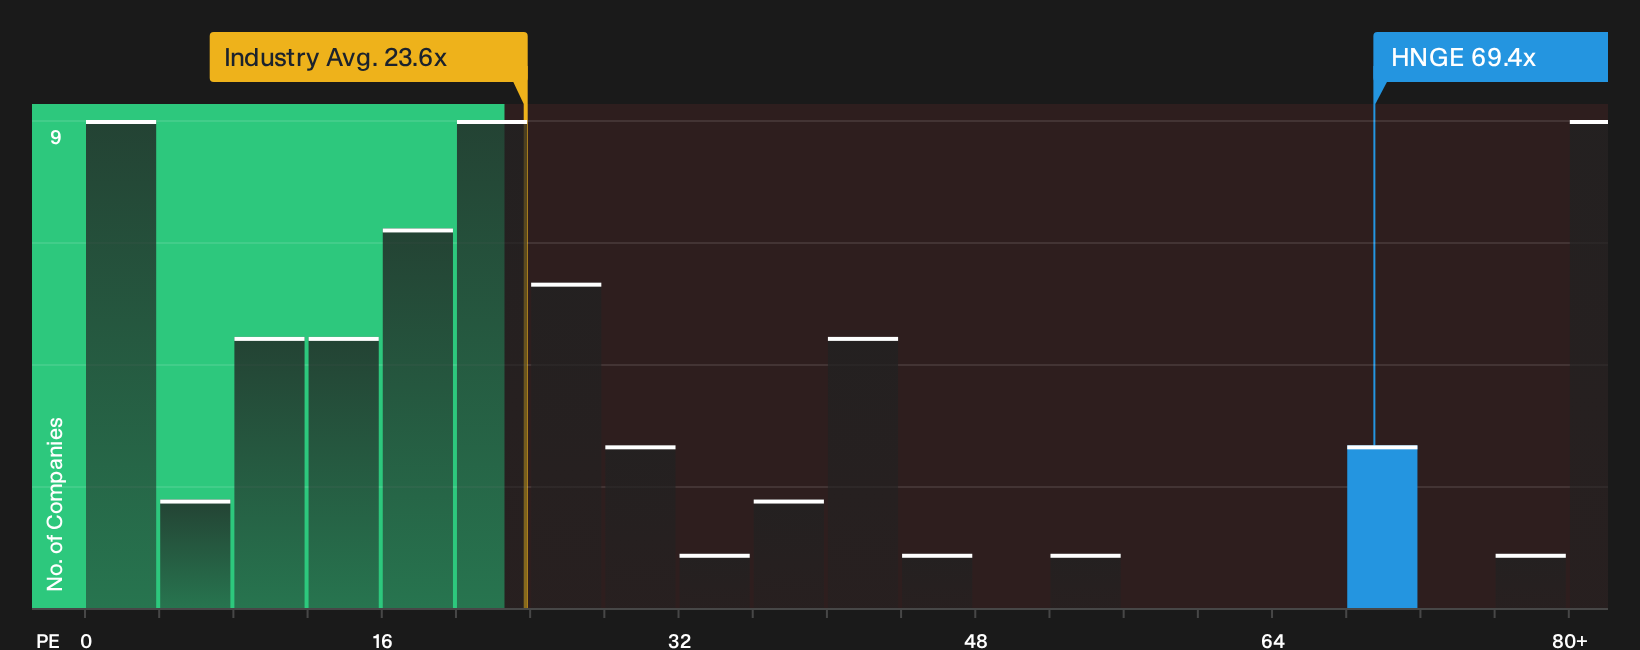
P/E is the cleanest yardstick for Hinge Health right now because the discussion is about how much investors are willing to pay for each dollar of current earnings. On that score, the stock trades on a P/E of about 69.4x, which sits above both the peer group average of roughly 61.8x and the wider Healthcare sector on about 23.6x. That gap shows that the market is already assigning Hinge Health a premium price tag relative to many other healthcare stocks.
The valuation model that blends Hinge Health's growth profile, margins, size and risk points to a lower multiple as a fairer anchor, so the current P/E appears overvalued on this framework. Because management recently raised revenue guidance and commentators such as Jim Cramer have highlighted the business in musculoskeletal telemedicine, sentiment has shifted in a way that makes this richer P/E easier for the market to accept. For anyone considering the shares, the key question is whether the earnings stream can continue to justify a rating this far above the benchmark the model suggests. Explore the numbers behind Hinge Health's P/E valuation.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Hinge Health valuation puzzle leaves off by spelling out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or less than it is today, and they sit on the platform's Community page. Rather than a single multiple or model output, each one lays out the assumptions behind its estimate of fair value so you can compare those expectations with Hinge Health's actual reported results over time.
Community views on Hinge Health split between those who see more upside in the current earnings power and those who think expectations already look full.
Bull case: 36% undervalued
"Together, these innovations allow Hinge Health to serve more members at lower incremental cost, reinforcing its competitive edge…"
Discover why this Narrative puts Hinge Health at 36% undervalued.
Bear case: roughly fairly valued
"Although the move to engagement based pricing is aligned with client interests and current average selling price is essentially flat, the model ties revenue more tightly to actual member usage…"
Explore why this Narrative puts Hinge Health at roughly fairly valued.
One more Hinge Health check that sits beside the price tag
The last piece to look at is who is actually steering Hinge Health and how their pay packets line up with your interests as a shareholder. See who runs Hinge Health and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com