


Will 2027 Gold Output Guidance Change Ramelius Resources Share Price Narrative
- Ramelius Resources issued fiscal 2027 guidance, targeting gold output between 205,000 and 225,000 ounces at all in sustaining costs of A$2,150 to A$2,350 per ounce.
- The new cost range gives investors a clearer view of how Ramelius Resources balances production volumes against inflationary pressures and ongoing investment needs.
- This guidance on 2027 production and all in sustaining costs may influence how investors assess the company’s broader investment narrative.
Scan how Ramelius Resources' 2027 cost guidance compares with peers by lining it up against 36 elite gold producer stocks that also publish detailed production and all in sustaining cost outlooks.
Ramelius Resources Investment Narrative Recap
To own Ramelius Resources, you need to be comfortable with a pure gold producer whose fortunes are tightly linked to realised prices, cost discipline and how well it runs its Australian mines. The 2027 guide of 205,000 to 225,000 ounces at A$2,150 to A$2,350 per ounce gives a clearer line of sight on the next operational phase.
In the near term, the key swing factor remains how consistently Ramelius Resources can execute at these guided cost levels after a year where profit margins moved from 39.4% to 12.1%. The biggest risk right now is that inflation, integration work and any production hiccups keep actual all in sustaining costs above the range.
The 2027 guidance call set for 21 September 2026 is the announcement that really matters alongside this cost outlook. That call gives management a platform to explain how Mt Magnet, Dalgaranga and the acquired Spartan assets fit into the production band and what trade offs they are making between capital spend and output.
For you as an investor, the detail from that call helps test the broader thesis around Ramelius Resources, including expectations for earnings growth, decarbonisation benefits and potential synergies from recent deals. It also helps frame whether current P/E multiples and analyst growth forecasts look aligned with the operational reality described in the new guidance.
Ramelius Resources' narrative projects A$2.5b revenue and A$790.7 million earnings by 2029. This implies 33.9% yearly revenue growth and an earnings increase of about A$665.3 million from A$125.4 million today.
Uncover how Ramelius Resources' fair value indicates a 24% potential upside to its current price that may not last much longer.
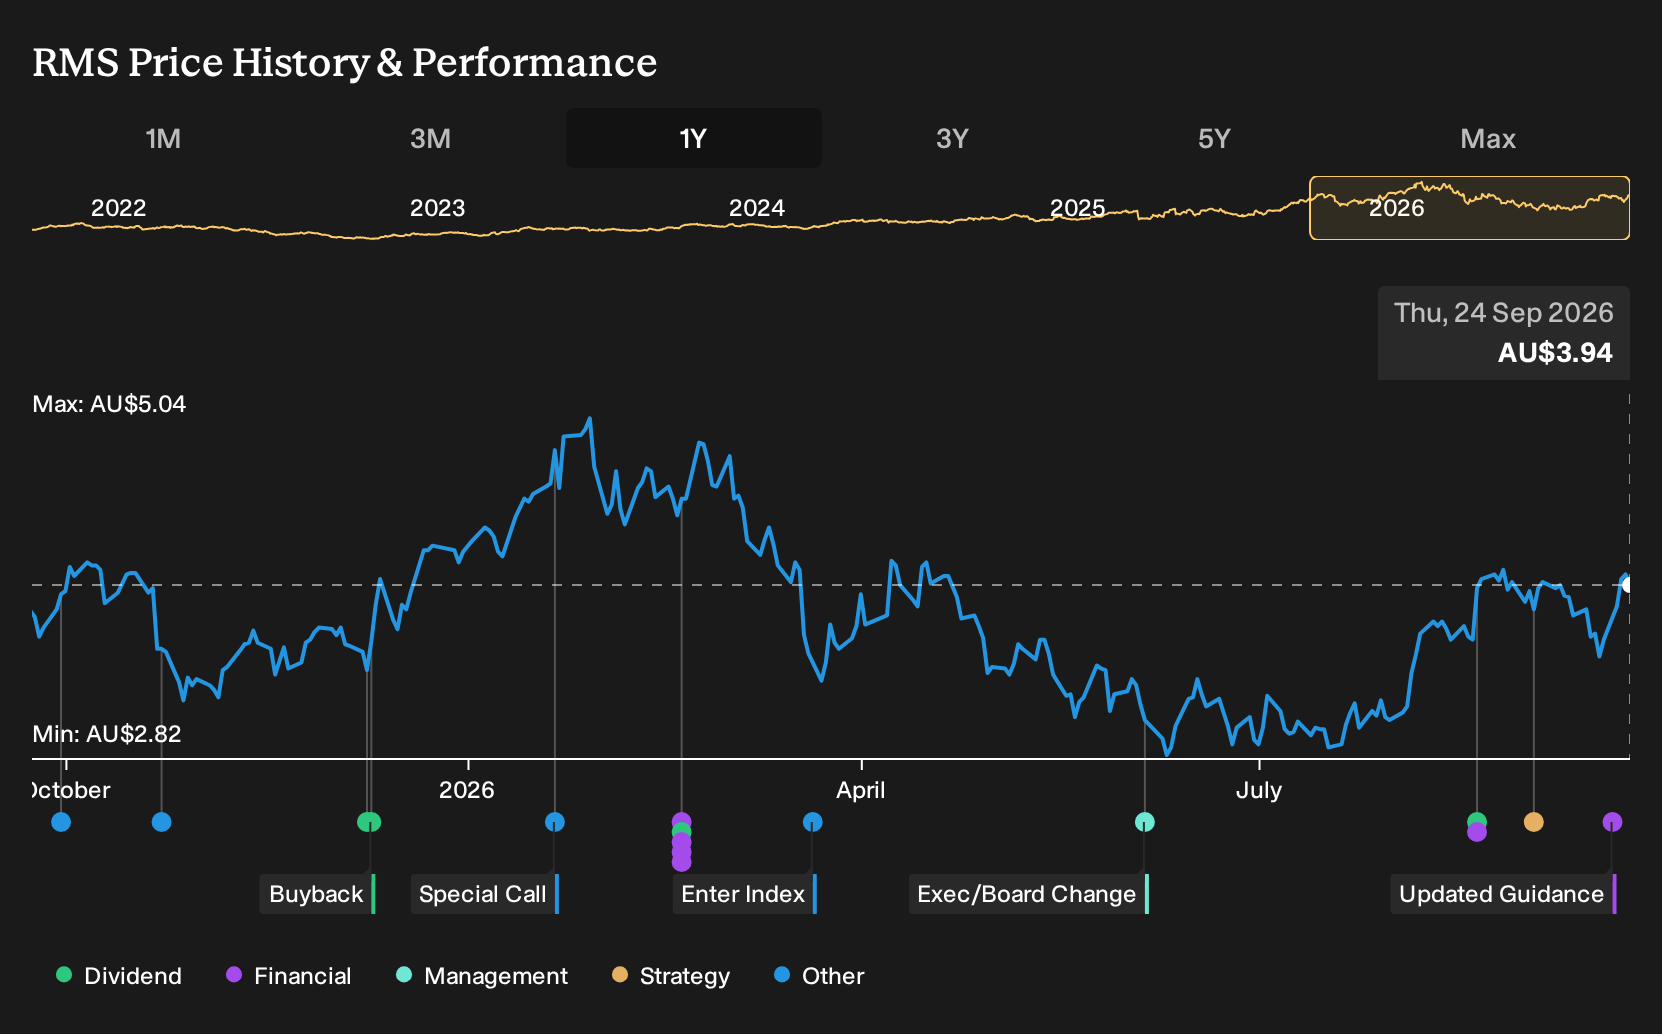
Exploring Other Perspectives
One alternate view puts ore grade depletion and heavier Western Australian exposure at the centre of the Ramelius Resources story. In that view, the lowest analysts were working off about A$2.1b revenue and A$580.9 million earnings by 2029, far below the A$2.5b and A$790.7 million consensus, and that gap may shift after this new guidance.
Explore 7 other Ramelius Resources fair value estimates, including one that suggests it could be worth just A$4.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ramelius Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ramelius Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ramelius Resources' overall financial health at a glance.
Looking For More Ideas Beyond Ramelius Resources?
If the Ramelius Resources story has sharpened your view on risk, cost control and upside potential, it can help to compare it with other listed businesses that fit very different profiles. Use that perspective to stress test your own framework rather than relying on a single gold producer.
- For investors who want potential mispricing combined with solid fundamentals, scan through a curated set of 6 high quality undervalued stocks that might sit closer to your preferred balance of quality and price.
- If capital preservation sits higher on your checklist, focus on a 7 resilient stocks with low risk scores that screens for companies with more resilient characteristics and fewer red flags on key risk metrics.
- When you want to widen the opportunity set beyond well-known tickers, cast the net over a 16 high quality undiscovered gems that often receive less attention but still show robust underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com