


MKS (MKSI), Why Is It Getting So Much Attention Now?
What MKS being added to the FTSE All-World Index could mean for investors
MKS (MKSI) was added to the FTSE All-World Index on 19 September 2026, an index move that can reshape how large global funds and ETFs approach the stock.
The semiconductor equipment supplier already features in institutional commentary, with Madison Investments citing MKS as a key contributor in its Mid Cap Fund and pointing to accelerating demand for the group’s manufacturing instruments.
Recent trading has been choppy for MKS, with the share price up 11.66% over the past week but down 35.97% over the past three months, while a 56.05% year to date share price return and 112.86% one year total shareholder return indicate that longer term momentum has been strong despite the volatility.
Compare how MKS stacks up against other semiconductor suppliers riding similar index and AI demand shifts by scanning the hand picked 85 AI infrastructure stocks in one place.
MKS now combines index inclusion, semiconductor exposure, and reported revenue and profit growth. The real tension is simple: are you paying a fair price for that package today?
Most Popular Narrative: 37% Undervalued
MKS last closed at $262.72, while the most followed narrative pegs fair value at $417.57. This implies a sizeable valuation gap that depends on how durable the AI and semiconductor equipment cycle proves to be.
The company's deepening integration of advanced materials and chemistry equipment (including Atotech) positions MKS as a unique provider of both tools and consumables required for the shift to multilayer, high-density AI-related applications; this is enabling cross-selling, leading to superior revenue growth and structural improvements in gross and operating margins.
See why 15 investors see MKS as 37% undervalued.
Result: Fair Value of $417.57 (UNDERVALUED)
Still, the bullish MKS story can break if the highly cyclical semiconductor equipment cycle turns sharply, or if trade and tariff friction compresses margins faster than expected.
Find out about the key risks to this MKS narrative.
Another View: What MKS’s P/E Is Really Telling You
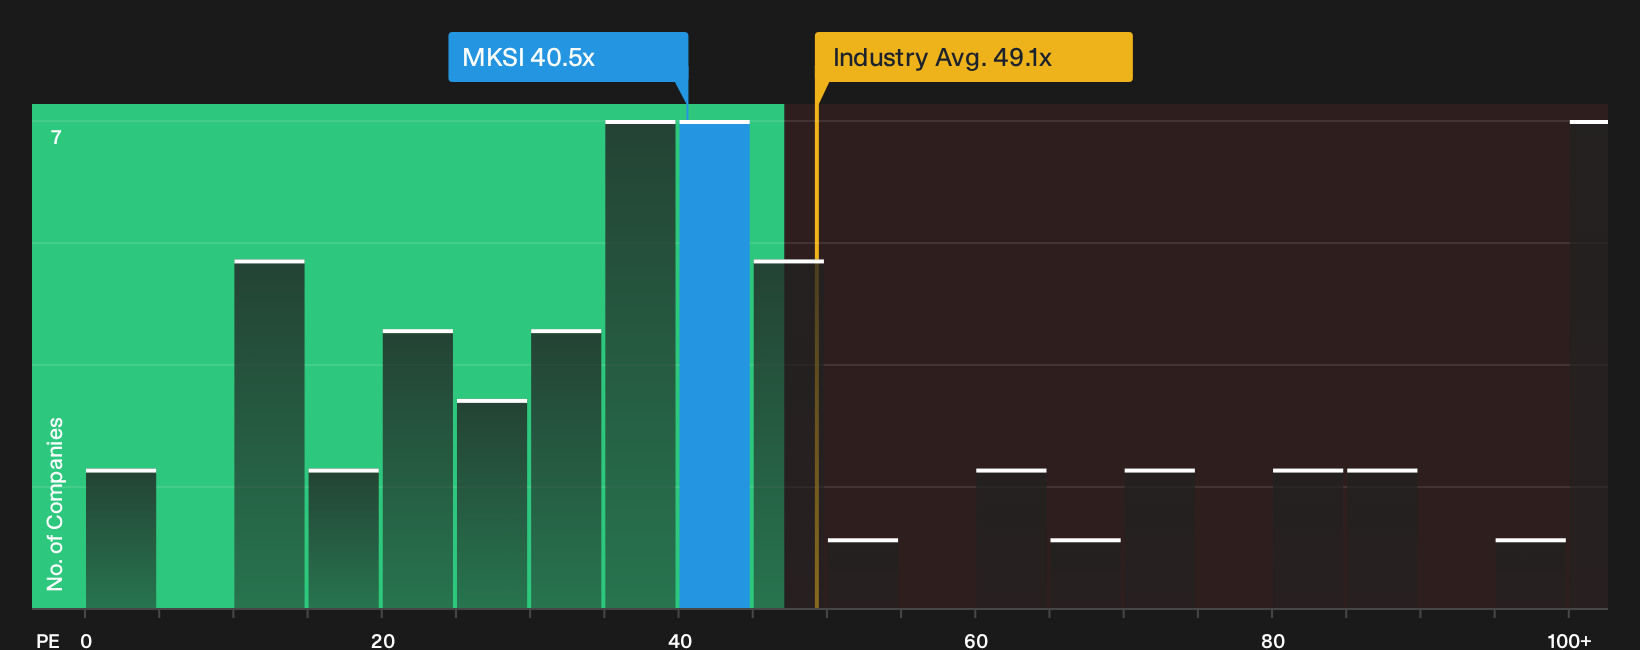
The first fair value story on MKS leans on long term earnings forecasts and a $417.57 target. The current P/E of 40.5x is only slightly above its fair ratio of 39.4x, yet it sits well below both peer averages of 62.1x and the broader US Semiconductor group at 49.1x. That mix hints at both valuation support and the risk that expectations are already rich. Where does that leave your margin of safety?
For a closer look at how the current P/E could shift over time, including how it compares with peers and that fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on MKS so far. If you want to move quickly and reach your own verdict, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more MKS sized opportunities?
Do not stop with MKS. Broaden your watchlist with a few focused stock ideas that match how you like to balance upside, income, and resilience.
- Target potential mispricing by scanning a curated set of companies that currently appear out of favour using the 30 high quality undervalued stocks.
- Prioritise reliable cash returns by zeroing in on businesses offering robust income streams through the 7 dividend fortresses.
- Protect your downside first by filtering for companies with resilient finances and sturdy fundamentals using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com