


Is ePlus (PLUS) Undervalued On Its New Share Authorization?
Share authorization change puts ePlus in focus
ePlus (PLUS) just received shareholder approval to increase its authorized common stock from 50,000,000 to 75,000,000 shares, a governance move that raises fresh questions about future capital plans and investor dilution risk.
Recent price action has been relatively firm, with ePlus posting a 13.5% 90 day share price return and a 6.7% 30 day share price return, while longer term total shareholder returns of 30% over one year and 81% over five years hint at momentum that investors are now reassessing in light of the fresh share authorization.
Compare ePlus' share authorization move with other hand-picked tech and infrastructure plays that screen well on balance sheet strength and fundamentals via the list of solid balance sheet and fundamentals (23 results)
ePlus now trades at a discount to both analyst targets and some fair value estimates, while also opening the door to possible dilution through higher authorized shares. Is the market being prudent or overly cautious on this stock?
Most Popular Narrative: 17% Undervalued
On the most followed narrative, ePlus is judged to be worth $111 per share, compared with the last close at $92.03, which puts the fresh share authorization into a sharper pricing context for investors weighing dilution risk against perceived upside.
Persistent demand for AI-powered infrastructure, security, and cloud solutions across industries is expected to accelerate, and ePlus's focused investments in AI consultative capabilities and AI-related "plumbing" (compute, networking, security) position the company to capture outsized revenue growth as enterprise adoption of digital transformation initiatives gathers pace.
The widespread adoption of remote/hybrid work models and escalating cybersecurity threats is ensuring continued robust demand for advanced networking and security solutions. These are core areas where ePlus is seeing double-digit growth, and where security now represents 22.8% of gross billings. This is supporting both top-line revenue expansion and an improved margin mix from value-added services.
See why 1 investors see ePlus as 17% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, that narrative leans heavily on continued appetite for large enterprise projects and assumes customer concentration in telecom, media, entertainment and SLED does not turn into a drag.
Find out about the key risks to this ePlus narrative.
Another view on what ePlus is worth
The narrative fair value for ePlus at $111 contrasts sharply with our DCF model, which puts future cash flow value closer to $58.97 per share. One framework treats PLUS as undervalued, while the other suggests it is rich. Which yardstick do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
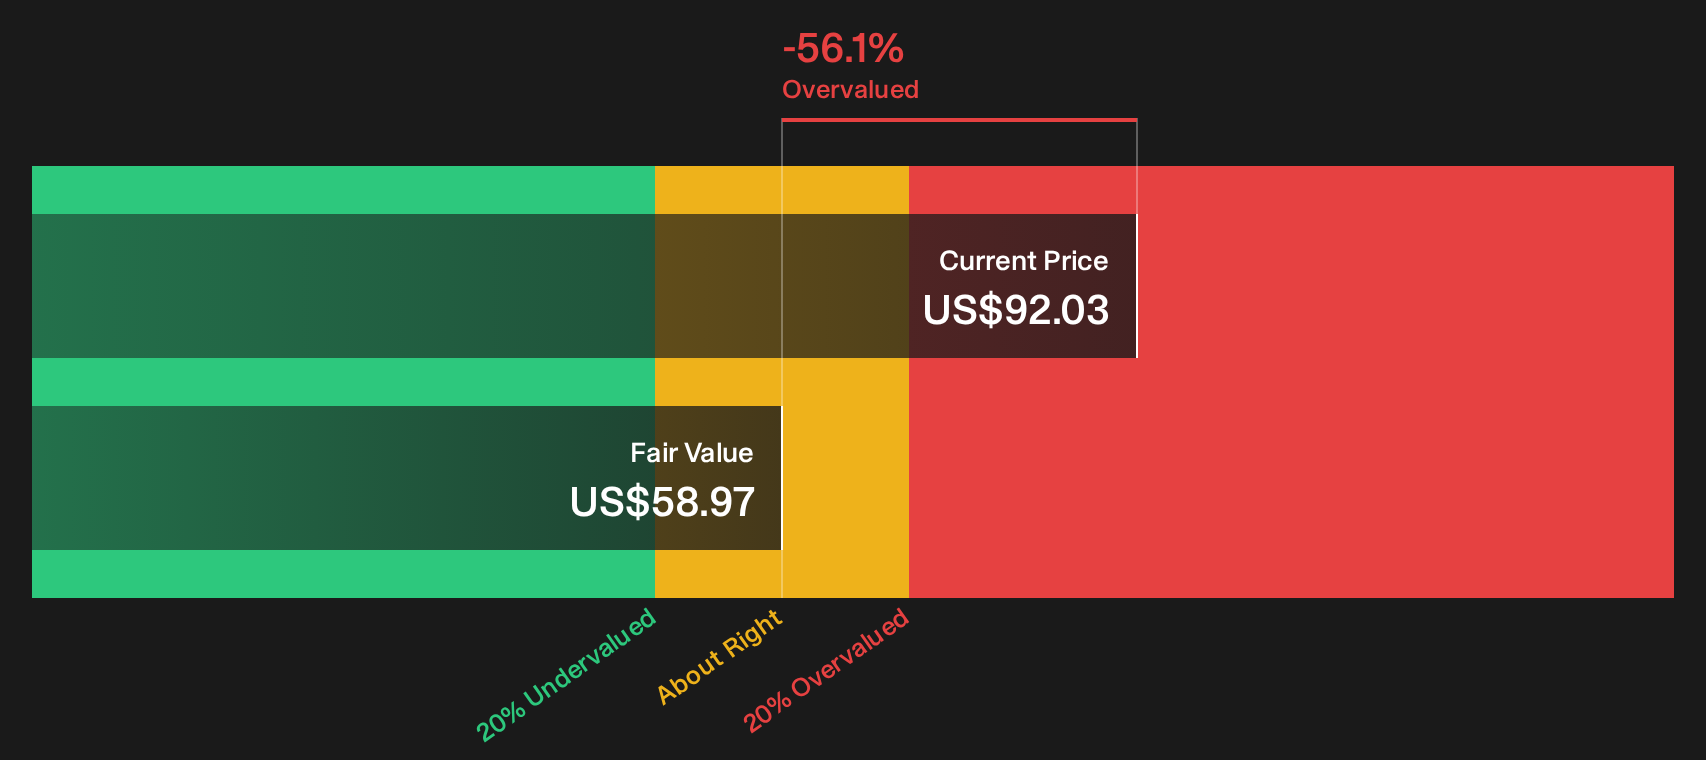
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ePlus for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ePlus can be exciting or uncomfortable depending on how you see risk and reward, so move quickly, test the numbers yourself, and then weigh those findings against the 4 key rewards
Looking for more ePlus investment ideas?
If signals around ePlus feel mixed, treat that as your cue to widen the lens and pressure test your next move against other high quality opportunities.
- Target stability first by scanning companies that show up in the 31 resilient stocks with low risk scores so your downside is not an afterthought.
- Hunt for quality at a discount by reviewing the 16 high quality undiscovered gems before the crowd starts paying attention.
- Prioritize financial resilience by checking the list of solid balance sheet and fundamentals (23 results) and avoid businesses that crack when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com