


Analog Devices (ADI), Why Is The Stock Drawing Fresh Attention?
Why Analog Devices Stock Is Back Under Pressure
Analog Devices (ADI) is under pressure as a sector-wide selloff hits chipmakers following a jump in the 10 year Treasury yield to a 19 year high, with AI infrastructure sentiment and fresh geopolitical questions adding to the drag.
Recent moves put that pressure in context. The share price is down 1.32% today to US$385.23, yet Analog Devices still shows a 7 day share price gain of 6.41% and a year to date share price return of 40.73%. The 1 year total shareholder return of 56.89% and 5 year total shareholder return of 148.04% point to strong longer term momentum, even as fresh bond issuance and the new senior notes program keep investors focused on interest rate sensitivity and funding costs.
Scan the wider AI hardware space under the same rate pressure by reviewing the hand picked 85 AI infrastructure stocks alongside Analog Devices in your next round of research.
Bulls point to Analog Devices' recent returns and double digit revenue and net income growth. Bears focus on richer multiples and a larger debt stack. Which side do the current valuation markers support next?
Most Popular Narrative: 15% Undervalued
Analog Devices' most followed valuation storyline pegs fair value at about $451 per share using an 11.28% discount rate, compared with the last close at $385.23. This frames the current selloff as a pullback within a narrative built around AI, power and industrial demand.
Robust expansion of AI infrastructure, green energy investments, and aerospace & defense outlays is creating healthy backlog and supply-constrained opportunities in several high-value segments, likely resulting in continued revenue and profitability momentum as ADI ramps internal capacity and leverages proprietary products.
See why 59 investors see Analog Devices as 15% undervalued.
Result: Fair Value of $451.03 (UNDERVALUED)
Still, rising competition from lower cost analog rivals and potential disruption from trade restrictions could quickly challenge the bullish Analog Devices narrative that investors are relying on.
Find out about the key risks to this Analog Devices narrative.
Another View On Analog Devices Valuation
The analyst-driven fair value narrative presents Analog Devices as about 15% undervalued at $451, yet the SWS DCF model points the other way. On that cash flow view, ADI at $385.23 trades above an estimated future cash flow value of $217.64, which screens as overvalued instead.
The contrast is clear. Earnings-based assumptions and analyst targets indicate the current price may have room on the upside, while the cash flow model suggests investors are already paying ahead of those projected streams of cash. Which lens do you rely on more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
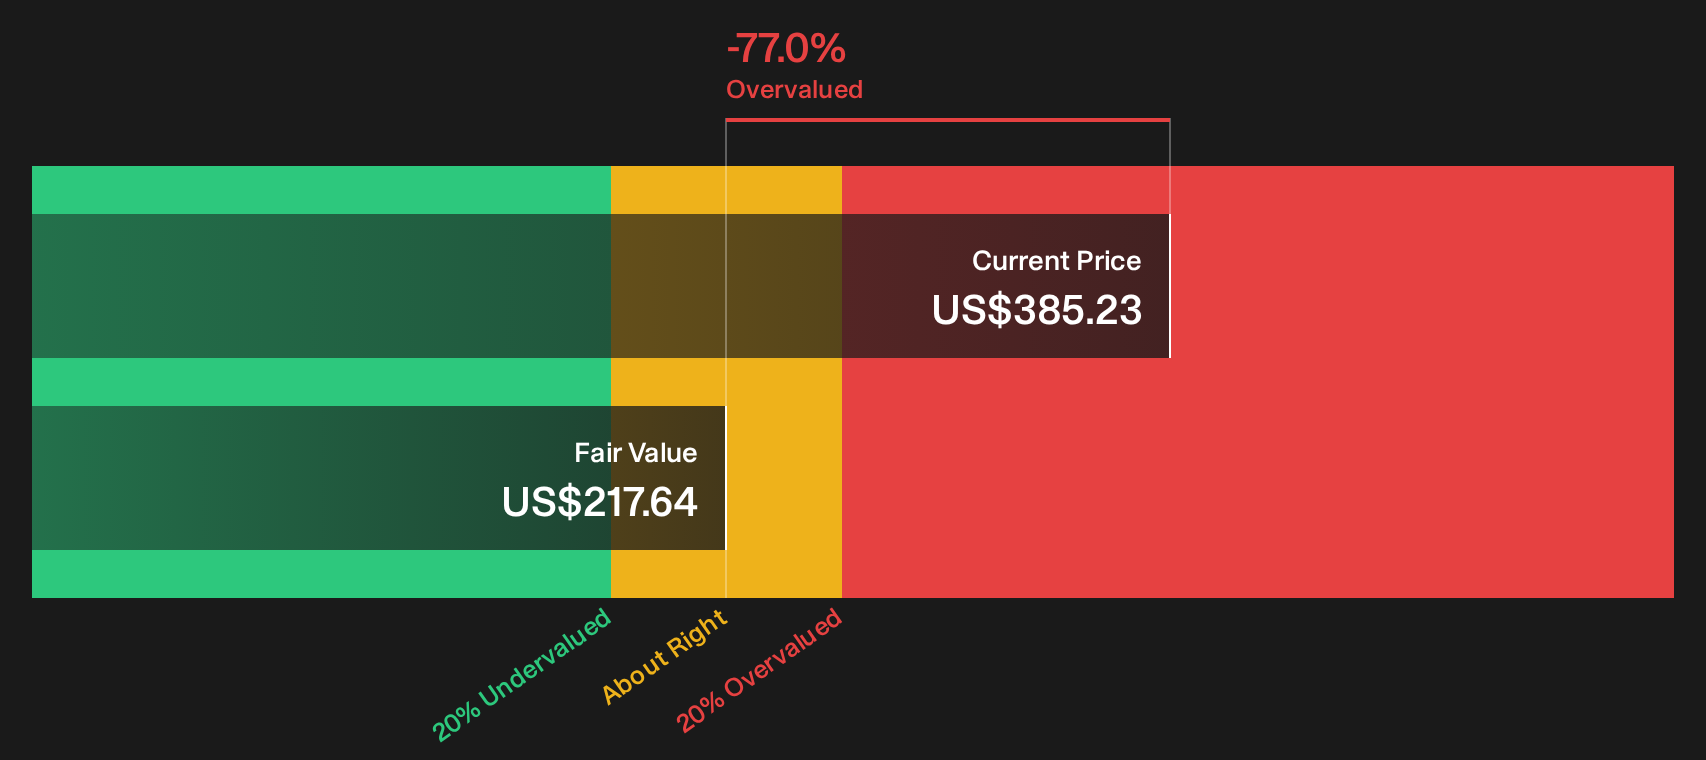
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Analog Devices for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split between upbeat returns and fresh valuation questions around Analog Devices is hard to ignore. Move quickly, review the key metrics and decide where you stand using the 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Analog Devices?
Before moving on, treat this as a moment to widen your watchlist and stress test your Analog Devices thesis against other opportunities uncovered by the Simply Wall St screener.
- Target dependable cash generators by scanning companies with robust profits and balance sheets using the 30 high quality undervalued stocks.
- Protect your downside by reviewing a 31 resilient stocks with low risk scores that highlights businesses with resilient fundamentals and calmer return profiles.
- Spot tomorrow's potential leaders early by studying the 16 high quality undiscovered gems that quietly pair solid financials with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com