


Is MGM Resorts Stock Underperforming the Nasdaq?
Las Vegas, Nevada-based MGM Resorts International (MGM) is a global gaming and entertainment company operating a portfolio of iconic hotels, casinos, resorts, and entertainment venues. Its properties include Bellagio, MGM Grand, ARIA, Mandalay Bay, The Cosmopolitan, and Borgata, spanning major U.S. markets and international destinations.
With a market cap of $9.8 billion, MGM Resorts International falls within the “mid-cap stock” category, generally referring to companies valued between $2 billion and $10 billion.
Its market leadership stems from its iconic global resort portfolio, strong brand recognition, and diversified revenue streams spanning casino gaming, hospitality, entertainment, dining, and digital sports betting. Its scale and established presence in major gaming markets provide a strong platform for attracting customers and generating recurring cash flow.
Despite its notable strength, MGM shares have struggled to maintain momentum, falling 26.6% from their 52-week high of $51.59, reached on July 17. The recent weakness has been particularly pronounced, with the stock down 19.3% over the past three months, while the Nasdaq Composite ($NASX) has gained 5.3% during the same time frame.
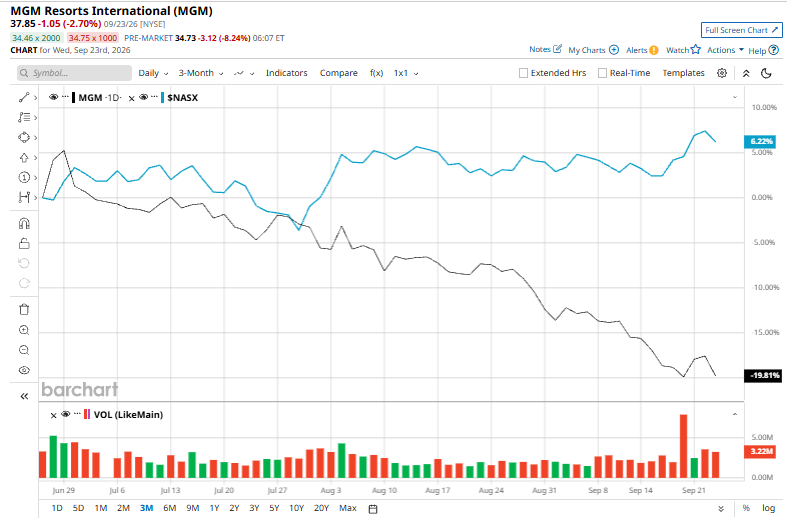
Over the longer term, MGM has managed modest gains of 3.7% year to date and 8.9% over the past 52 weeks, but still trails the Nasdaq Composite’s 15.9% YTD advance and 19.3% gain over the past year.
MGM’s technical picture remains firmly bearish, with shares trading below both key moving averages, falling below the 50-day moving average in late July and remaining below the 200-day moving average since mid-September.
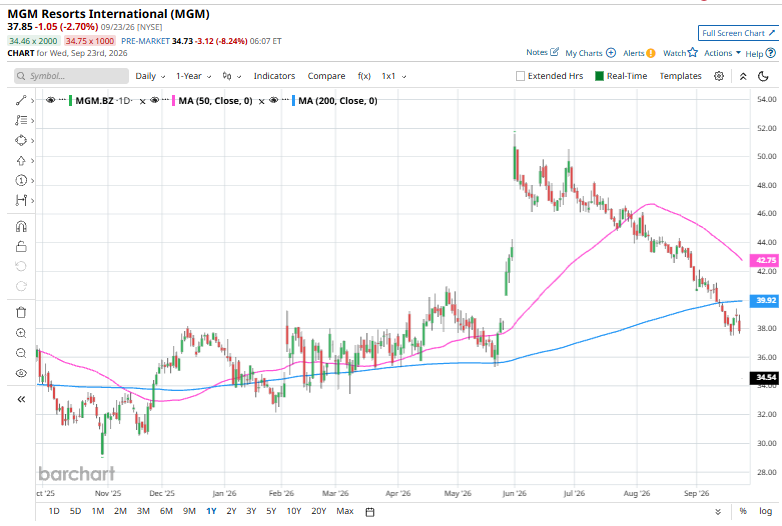
MGM has lagged the broader market over the past year amid weaker gaming demand, pressure on its Las Vegas operations, and concerns around its Macau exposure. The stock has also faced investor caution over the highly cyclical nature of casino and resort spending, while competition across the gaming and hospitality markets has weighed on growth expectations.
Moreover, its 2% revenue growth over the past two years has trailed consumer discretionary peers, while weakening capital returns raise concerns about the effectiveness of its investments. Meanwhile, a 12× net-debt-to-EBITDA ratio points to significant leverage and reduced financial flexibility.
Within the casino and resorts arena, MGM Resorts has held up better than rival Caesars Entertainment, Inc.’s (CZR) 26.6% YTD decline and 12.2% drop over the past year.
Wall Street analysts are bullish on MGM’s prospects. The stock has a consensus “Moderate Buy” rating from the 22 analysts covering it. The mean price target of $50.52 points to potential upside of 33.5% from MGM’s current price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.