


New AI Chips Might Change The Case For Investing In Qualcomm Stock
- Qualcomm recently introduced new 2 nm Snapdragon 8 Elite Gen 6 and 8 Elite Extreme Gen 6 processors, featuring advanced on device AI for premium Android phones and early design wins across brands including Motorola, OnePlus, OPPO, vivo and Xiaomi.
- The company is tying these mobile chips to a broader push into edge AI, automotive platforms, data center acceleration and optical connectivity. This suggests Qualcomm is trying to rebalance its business mix away from handset cyclicality.
- Next, the focus shifts to how Qualcomm’s push into agentic AI hardware, especially the new Snapdragon 8 Elite Extreme, could reshape its investment narrative.
QUALCOMM Investment Narrative Recap
To own QUALCOMM, you need to believe the business can turn its AI, automotive, IoT and data center bets into a less handset heavy model while keeping returns attractive. In the short term, the main swing factor is execution on new AI chips and early wins like Googlebook laptops and Motorola’s Signature 27, versus a smartphone market facing pressure from higher memory costs.
The biggest near term risk still sits in handset cyclicality and competitive pressure from in house silicon at large OEMs, along with Qualcomm’s own guidance that earnings are expected to decline slightly over the next three years. The latest AI announcements do not remove that risk; they simply give management more levers beyond phones.
The most relevant update for the current AI story is Qualcomm’s plan to start booking AWS related data center revenue from the December 2026 quarter, tied to custom silicon and optical connectivity. That agreement is framed as up to US$60b of product purchases over ten years, which is material relative to today’s US$44.1b revenue base.
If Qualcomm executes on that AWS program alongside its High Bandwidth Compute roadmap, it directly supports the target of US$5b in data center sales in fiscal 2027 and US$15b in 2029. The risk is clear. Any slip in design wins or product ramp would leave Qualcomm carrying higher R&D and capacity costs without the planned offset, which would pressure QCT margins and soften the AI narrative that investors are currently focused on.
QUALCOMM's current analyst storyline points to US$60.0b in revenue and US$11.5b in earnings by 2029, built on assumptions of 10.8% yearly revenue growth and an earnings increase of about US$2.2b from US$9.3b today.
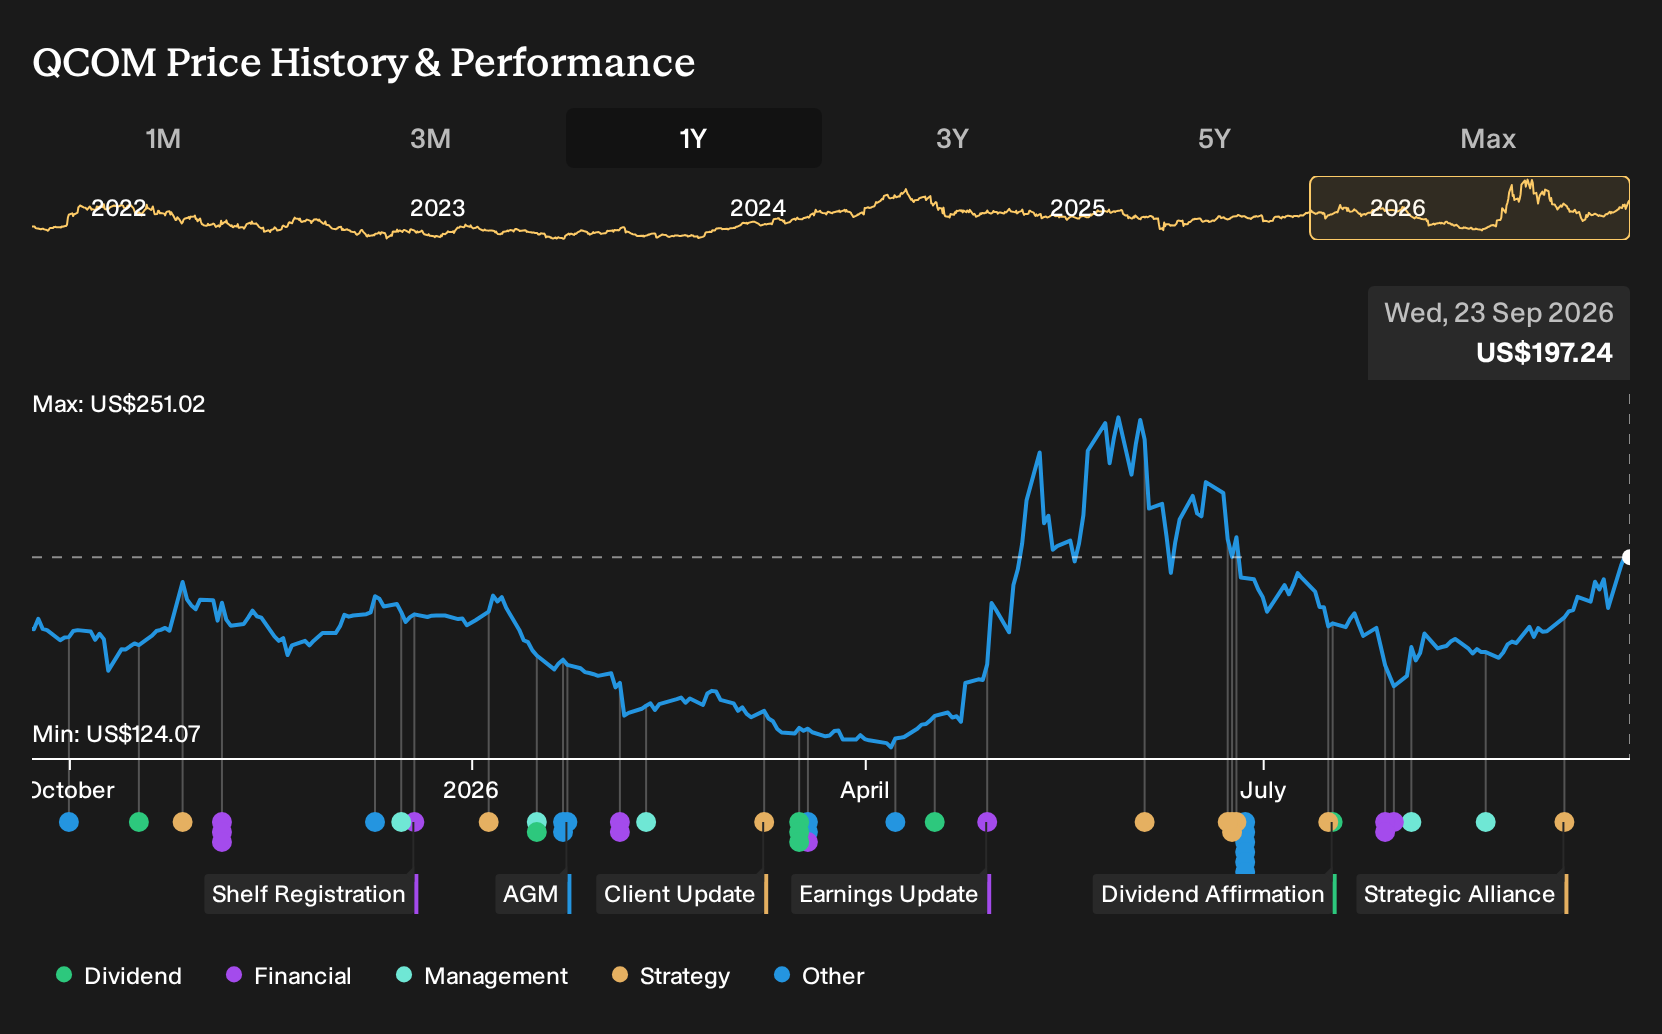
Uncover why QUALCOMM's fair value indicates that QUALCOMM is currently priced roughly in line with its value.
Exploring Other Perspectives
One alternate view fixates on geopolitical risk rather than AI upside. Under that lens, worsening US China frictions and localization efforts could pull Qualcomm’s 2029 revenue closer to US$48.4b with earnings around US$9.2b, which is far below consensus. That bearish cohort prices in a P/E of 15x and invites you to question whether the new Snapdragon AI push and events like the Humanoids Summit might eventually shift those assumptions.
Explore 8 other QUALCOMM fair value estimates, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your QUALCOMM research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QUALCOMM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QUALCOMM's overall financial health at a glance.
Looking For More Investment Ideas Beyond QUALCOMM?
If the QUALCOMM story has sharpened your view on AI hardware and long term growth, it can help to compare it with other companies that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside with tighter capital, scan a focused list of 9 elite penny stocks with strong financials that already show strong fundamentals instead of relying purely on hype.
- If value is the priority, filter for businesses trading below their estimated worth with solid cash generation using our curated 30 high quality undervalued stocks as a starting universe.
- For those who care most about resilience and capital preservation, narrow your research to a 31 resilient stocks with low risk scores and see which tickers align best with your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com