


3 Indian Undervalued Stocks With Up To 47% Fair Value Discounts
Indian equity indices recently fell sharply as rising global bond yields and higher oil prices pushed investors toward safer cash flows. That kind of risk-off mood can turn solid, cash-generating businesses trading below estimated fair value into rare bargains. This article looks at three Indian stocks highlighted by a discounted cash flow screener that flags companies where current prices may not fully reflect their potential for generating future cash streams.
The three stocks highlighted below are only a sample from this idea, as the full discounted cash flow screen identified 4 more Indian companies with similarly interesting cash profiles that are not discussed here. To identify and analyze those extra candidates side by side with the picks in this article, go straight to the Undervalued Stocks Based On Cash Flows screener.
WPIL (BSE:505872)
WPIL is a Kolkata based pump and water infrastructure specialist. Its engineered systems and long running service work link directly to this screener’s focus on cash flow strength and discounted cash flow valuation, making it a useful case study for value oriented investors.
WPIL manufactures pumps and turnkey pumping systems for water, irrigation, municipal and energy uses, with about ₹10.7b from Pumps and Accessories and ₹9.1b from Project works contracts, and carries a market value of roughly ₹42.9b.
"Rising global focus on water infrastructure, including river linking, wastewater and municipal water projects, is feeding into WPIL's consolidated project and product order backlog of about ₹5,200 crores."
What that backlog ultimately means for WPIL’s margins and cash conversion hinges on how one less visible pressure point plays out.
That pressure point is exactly what the full narrative for WPIL unpacks, including how WPIL’s order mix and cash timing could be masking a more attractive engine.
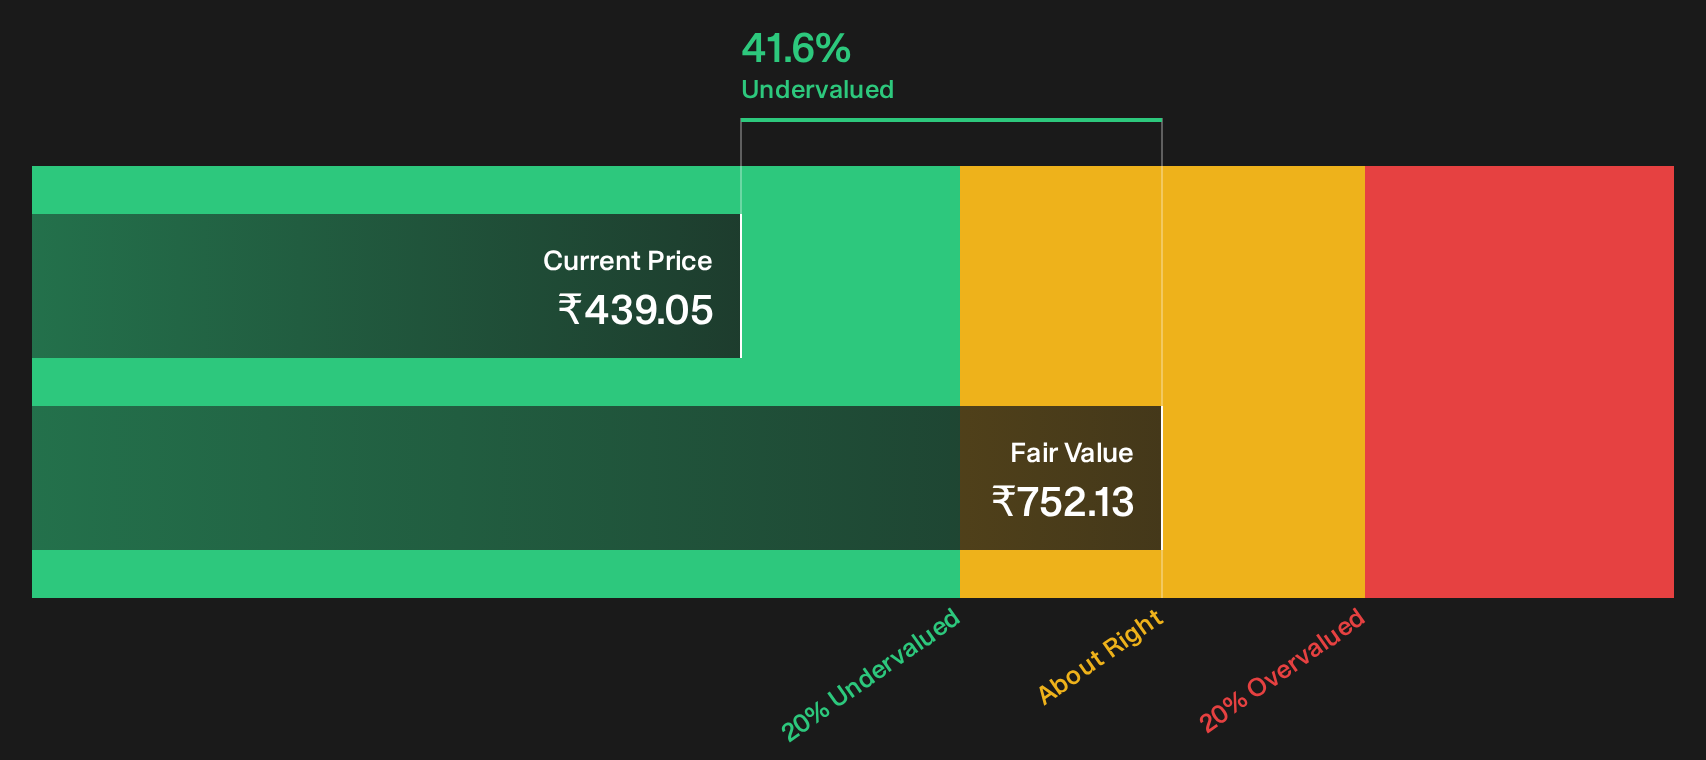
Flair Writing Industries (NSEI:FLAIR)
Flair Writing Industries runs a broad pen, stationery and houseware franchise, and its writing instruments cash engine aligns directly with this discounted cash flow theme, since that segment contributes about ₹12.8b of revenue inside a stock valued by the market at roughly ₹25.4b.
For value focused investors, Flair Writing Industries offers a familiar consumer product story where steady writing related cash flows meet a business that is quietly reshaping its mix toward higher margin categories that matter for long term earnings power.
"Scaling of high growth, higher margin creative and steel bottle and houseware portfolios, which together already contribute about 30% of revenue versus 15% last year, is expected to structurally lift consolidated revenue growth above prior guidance and sustain EBITDA margins near or above 18%."
What really tests the cash flow thesis for Flair Writing Industries is how one less visible constraint on that margin ambition eventually resolves.
That constraint is exactly what the full narrative for Flair Writing Industries lays bare, showing how Flair Writing Industries could turn today’s margin ceiling into an accelerating cash engine.

TeamLease Services (NSEI:TEAMLEASE)
TeamLease Services is one of India’s better known human resource platforms, with its general staffing, contractual staffing and payroll support lines generating the recurring cash flows that anchor its place in an undervalued cash flow screen. General Staffing brings in about ₹110.1b, with Specialised Staffing at roughly ₹7b and Other HR Services at about ₹2.5b, under a stock valued by the market at around ₹20.1b.
TeamLease Services operates at the intersection of recurring staffing cash flows and a long list of HR add-ons, and that mix is what makes the business notable for a screen that focuses on undervalued cash generators rather than headline stories.
"The rapid growth of apprenticeship adoption, accelerating government skilling initiatives, and TeamLease's unique partnerships with 22 universities position it as the clear national leader in work-integrated learning, paving the way for a new, high-growth, higher-margin revenue stream that is underappreciated in current earnings estimates."
The key variable for TeamLease Services is how one relatively quiet shift in how clients source and automate labour ultimately influences future margins.
That quiet shift in client behaviour is exactly what the full narrative for TeamLease Services unpacks, revealing how TeamLease Services could convert overlooked staffing cash flows into a more dynamic earnings engine.

Seeking Alternatives Before The Crowd
Fresh opportunities do not sit still. While attention chases yesterday’s breakout, new ideas gain momentum under the radar for now. Before the next wave starts flying, consider getting in early.
- Filter for resilient balance sheets and steady cash engines with a curated list of solid balance sheet and fundamentals (199 results) before others notice the gap between fundamentals and market pricing.
- Explore the next infrastructure buildout by scanning curated 39 power grid technology and infrastructure stocks while valuations still reflect yesterday’s demand and not tomorrow’s network upgrades.
- Seek focused exposure to potential monetary hedges through a hand picked set of 36 elite gold producer stocks before crowded flows compress the opportunity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com