


Dillard's (DDS) Following Choppy Trading Faces Fresh Questions Over Valuation
Dillard's (DDS) has drawn investor attention after its latest trading session, with the stock closing at US$645.66. These short-term moves sit against a longer backdrop of mixed return figures across different time frames.
Recent trading has been choppy rather than directional, with the share price slipping 0.7% on the day and edging higher over the past month, while still holding an 11.1% 90-day share price gain and a much stronger multi year total shareholder return profile for Dillard's.
Scan how Dillard's compares with other retailers showing strong recent moves and financial resilience by checking the hand picked list of solid balance sheet and fundamentals (23 results).
After a multi year run and a recent stretch of choppy trading, the question for Dillard's now is simple: Is most of the share price gain already behind it, or does valuation still suggest room ahead?
Price-to-Earnings of 14.8x: Is it justified?
Dillard's now trades on a P/E of 14.8x, which sits below the wider US market but above its closer peer group and the modelled fair level.
The P/E ratio compares the current share price to earnings per share and helps you see how much investors are paying for each dollar of profit. For a retailer like Dillard's, where earnings can move with consumer spending and store performance, this yardstick is often a primary lens for comparing it with rivals.
On one side, Dillard's P/E is below the broader US market level of 18.2x. This suggests investors are not paying a market premium for the stock. On the other side, it is higher than the peer average of 12.1x and above the estimated fair P/E of 10.1x. This points to a richer valuation than both similar retailers and the level our fair ratio model suggests the market could move toward.
Explore the SWS fair ratio for Dillard's.
Result: Price-to-Earnings of 14.8x (OVERVALUED)
Still, the recent decline in annual net income, alongside a P/E above both peers and the modelled fair level, could leave Dillard's exposed if earnings weaken further.
Find out about the key risks to this Dillard's narrative.
Another View on Dillard's Valuation
A second lens tells a slightly different story. Our DCF model puts Dillard's future cash flow value at $639.85 per share, a touch below the current $645.66 price. That points to the stock trading a little above this cash flow based estimate and leaves you asking how much margin of safety really exists.
Look into how the SWS DCF model arrives at its fair value.
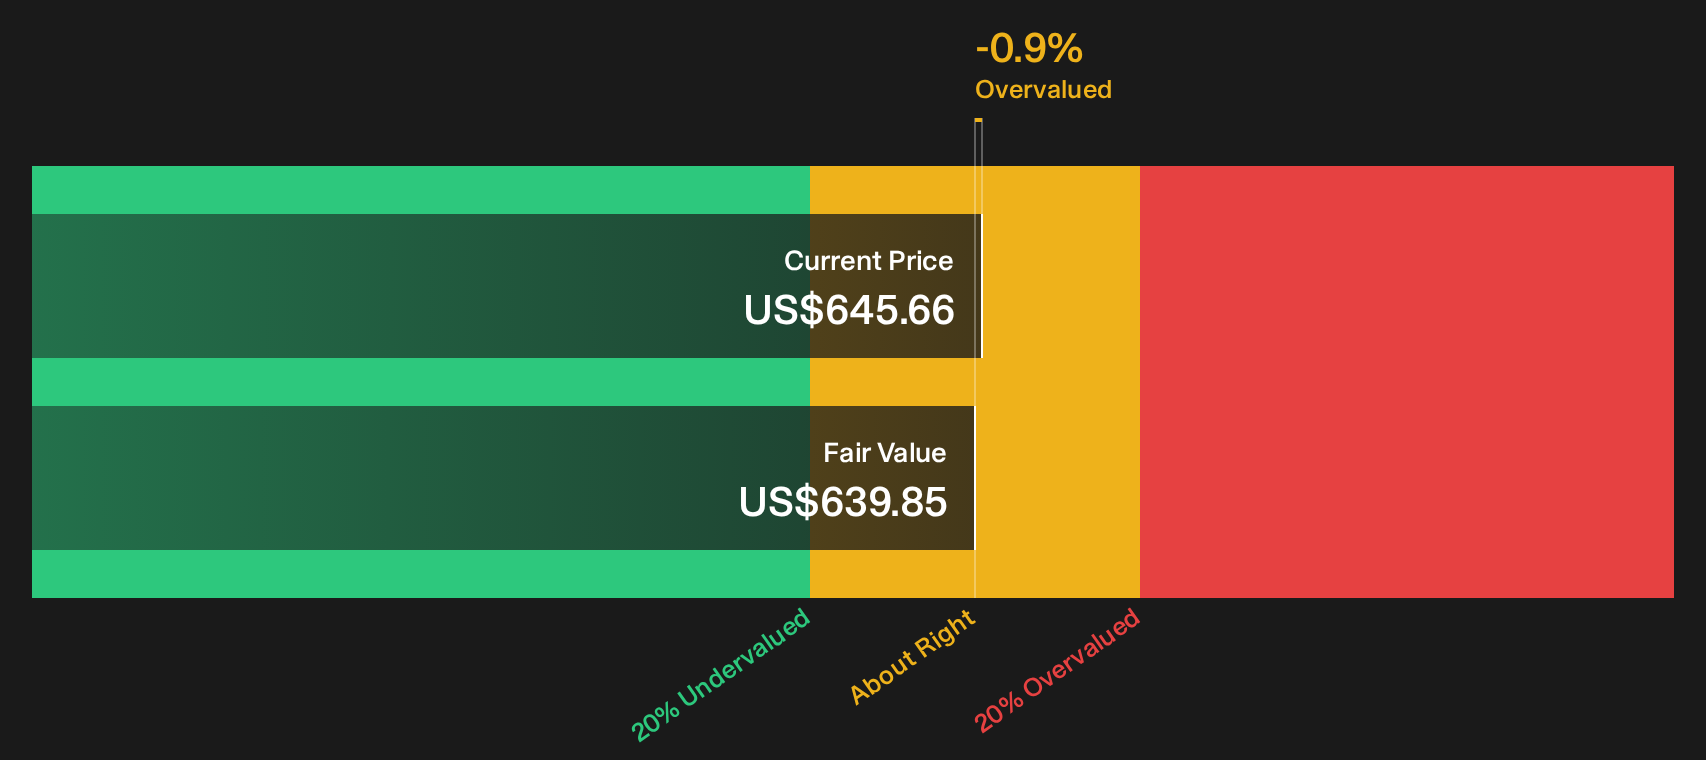
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dillard's for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the mixed signals on Dillard's valuation story? Act while the data is fresh and make your own call by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dillard's?
If Dillard's has you thinking harder about valuation and risk, do not stop there. The strongest portfolios usually come from casting a wider net.
- Target reliable compounding by scanning companies that look attractively priced on both quality and valuation through the 30 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with resilient cash flows and yields using the 7 dividend fortresses.
- Dial down portfolio stress by focusing on financially robust companies screened through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com