


Cochlear (ASX:COH) Has Investors Asking A Bigger Question
Cochlear (ASX:COH) has just put its dividend policy under the spotlight, with a total payout of A$0.47 per share and a dividend payout ratio of 1.99, which signals that distributions currently exceed earnings.
Recent trading has been choppy for Cochlear, with the share price now at A$142.8 and a 90 day share price return of 20.99%, but a year to date share price return that is down 45.29%. The 1 year total shareholder return has declined 48.81%, suggesting that recent momentum has picked up after a much tougher stretch for longer term holders.
Compare Cochlear's dividend squeeze with other resilient payers by scanning our hand picked 3 dividend fortresses for alternatives with higher yields and sturdier coverage ratios.
Cochlear shares have jumped over the past three months after a tough year, which presents a simple fork in the road for you: lean into the rebound now, or wait for a cleaner valuation reset next.
Most Popular Narrative: 104% Overvalued
Cochlear is trading at A$142.8 against a narrative fair value of A$70, which frames the recent rebound as rich rather than cheap on this view.
Despite the substantial fall in the share price, the company still does not appear obviously cheap given the uncertainty that remains. The price-to-earnings ratio remains above 20 times downgraded earnings, while some discounted cash flow models suggest fair value may sit materially below current prices.
See why 14 investors see Cochlear as 104% overvalued.
Result: Fair Value of A$70 (OVERVALUED)
Still, any recovery in surgery volumes or a softer Australian dollar could quickly challenge the view that Cochlear is priced well above fair value.
Find out about the key risks to this Cochlear narrative.
Another View: Our DCF Model Flips The Story
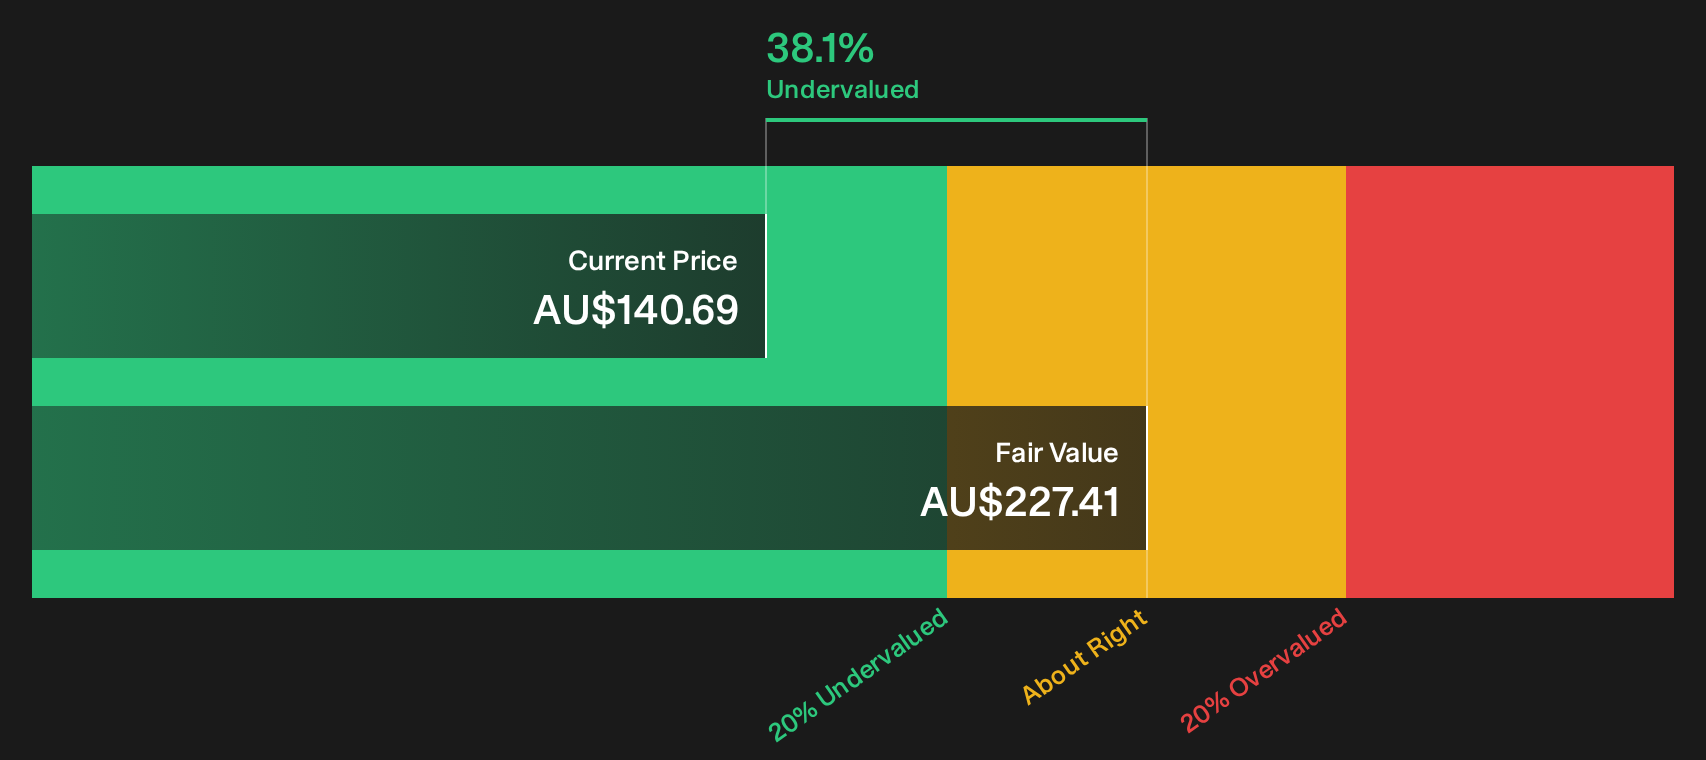
The earlier narrative-based fair value suggested Cochlear was overpriced, yet the SWS DCF model tells a very different story. On that math, A$142.8 is trading about 37% below an estimated future cash flow value of A$227.65, which points to undervaluation instead.
This kind of split screen between headline multiples and long range cash flows forces a simple question for any Cochlear holder: Which lens matters more when the market eventually picks a side?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cochlear for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The split between Cochlear's overvaluation narrative and the DCF upside flag makes the picture messy, which is exactly why you should move quickly to inspect the evidence yourself and then decide where you stand using the 2 key rewards and 2 important warning signs.
Looking for more Cochlear sized opportunities?
If Cochlear has you thinking harder about valuation and dividend strength, do not stop here. Broader idea hunting now could be just as important.
- Target resilient upside potential by scanning our 6 high quality undervalued stocks that blend solid fundamentals with prices that still look compressed on traditional metrics.
- Prioritise capital preservation first and sift through a 7 resilient stocks with low risk scores that focuses on sturdier balance sheets and more measured volatility profiles.
- Hunt for future leaders early by reviewing a 16 high quality undiscovered gems before the crowd fully turns its attention their way.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com