


Butterfield Bank (NTB) Stock Trades At A Discount To Earnings
Bank of N.T. Butterfield & Son has seen its share price move sharply over recent years, which naturally raises the question of whether the current tag reflects what its earnings can support. With that backdrop, many investors are now focusing less on the headline gains and more on what the underlying profit stream really justifies.
- Over the past 3 years the stock has returned about 149.6%, which puts a lot of weight on whether the earnings profile has kept pace with the rising expectations baked into Bank of N.T. Butterfield & Son's valuation.
- KBRA's decision to place Butterfield's ratings on watch for downgrade after the planned US$1.8b CIBC Caribbean acquisition highlights how a larger balance sheet, higher credit risk and lower capital ratios can reshape what investors are willing to pay for the bank's profit base.
- There is a second opinion on Bank of N.T. Butterfield & Son worth weighing. See what analysts think Bank of N.T. Butterfield & Son's shares could be worth.
The issue now is whether Bank of N.T. Butterfield & Son's current share price can be explained by its earnings when viewed through this lens.
If you want to test the same earnings based valuation question that hangs over Bank of N.T. Butterfield & Son across a wider opportunity set, start with 30 high quality undervalued stocks.
Does Bank of N.T. Butterfield & Son Look Undervalued on Earnings?
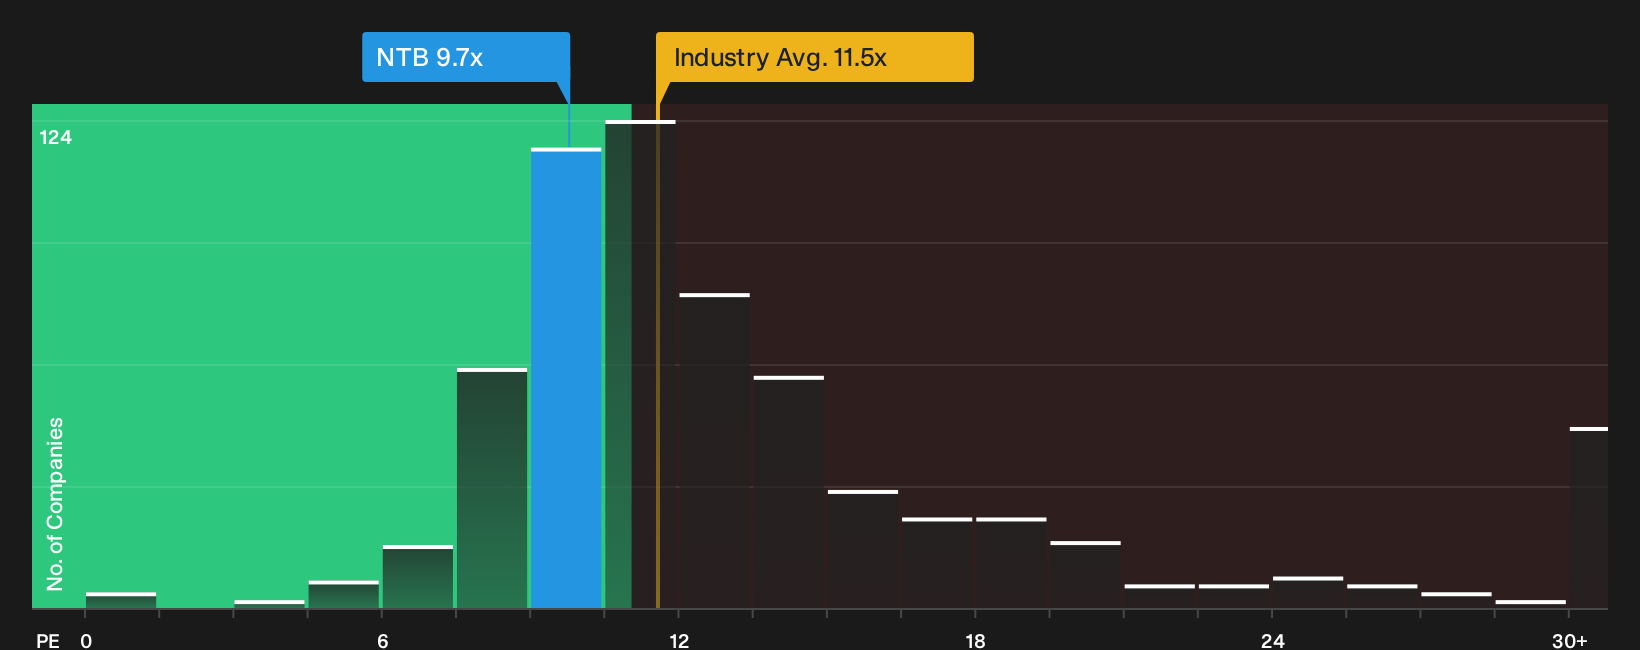
The P/E ratio fits Bank of N.T. Butterfield & Son because earnings are still the main yardstick investors use to judge a lender’s profit engine. On this measure, the stock trades on about 9.7x earnings, which is below both the broader banks sector on roughly 11.5x and a peer group closer to 13.5x. For a reader, that means the market is currently paying less per dollar of profit here than for many comparable institutions.
Because the recent CIBC Caribbean deal has put the bank’s credit profile and capital ratios under closer scrutiny, this discount comes despite fresh attention on the enlarged group’s risk mix. The valuation model suggests that, given Bank of N.T. Butterfield & Son’s own economics and risk profile, a higher P/E would be consistent with its fundamentals. As a result, the present multiple screens as undervalued relative to that tailored benchmark. For investors, the key question is whether the earnings stream after the acquisition will justify a re rating closer to that implied level. Explore the numbers behind Bank of N.T. Butterfield & Son's P/E valuation.
The Bank of N.T. Butterfield & Son Narrative: What Would Justify Today's Price?
Narratives for Bank of N.T. Butterfield & Son pick up where the valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for today’s share price to look either generous or conservative. Each scenario ties a specific fair value range to a concrete story about potential catalysts and risks, so you can track over time which version of events lines up with what the bank actually delivers on Simply Wall St’s Community page.
One of the top community narratives on Bank of N.T. Butterfield & Son: 6% undervalued
"Expansion in global wealth management and private trust services, paired with digital transformation, supports diversified, stable fee-based revenue and improved operational efficiency..."
Discover why this Narrative puts Bank of N.T. Butterfield & Son at 6% undervalued.
One more angle on Bank of N.T. Butterfield & Son that could change the story
The people steering Bank of N.T. Butterfield & Son, and how their pay packets line up with your interests, can matter as much as any P/E ratio. See who runs Bank of N.T. Butterfield & Son and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com