


Disco (TSE:6146), What Is Drawing Fresh Attention Now?
Disco (TSE:6146) is back on investor screens after analysts lifted their consensus earnings forecasts over the past 3 months, a sentiment shift that often draws fresh attention to the stock.
Short-term momentum for Disco has cooled, with the share price down 12.64% over the past month and 32.45% over 90 days. However, the current ¥53,030 level still reflects a 3.78% year to date share price gain and a very large 5 year total shareholder return of 443.11%. This indicates that long term holders have seen strong compounding, while recent trading points to more cautious sentiment around the upgraded earnings outlook.
Spot similar earnings upgrade stories to Disco by scanning our hand-picked list of 75 high quality undiscovered gems that have strong fundamentals but still fly under most investors' radar.Disco now trades at a sharp discount to analyst targets after that steep pullback. Are investors rightly sceptical, or has caution pushed the valuation too far down?
Price-to-Earnings of 39.4x: Is it justified for Disco?
On earnings, Disco currently trades on a P/E of 39.4x, which puts a rich valuation on the ¥53,030 share price compared with several reference points.
The P/E ratio compares the current share price to earnings per share. For a specialist equipment maker like Disco in the semiconductor supply chain, this measure is often used as a shorthand for what investors are willing to pay today for each unit of current profit.
At 39.4x earnings, the market is putting a steep premium on Disco compared to the JP Semiconductor sector average of 21x. That indicates investors are paying a higher multiple of current earnings than is typical across the broader industry. The company is also trading above the Fair P/E Ratio estimate of 29.8x, so the market price is meaningfully higher than a level some models indicate it could gravitate toward over time.
Explore the SWS fair ratio for Disco.
Result: Price-to-Earnings of 39.4x (OVERVALUED)
Still, Disco faces real pressure points, including reliance on a single precision systems segment and the risk that analyst optimism fades if earnings momentum slows again.
Find out about the key risks to this Disco narrative.
Another View on Disco’s Value
The SWS DCF model tells a different story for Disco. On this framework, the estimated future cash flow value sits at ¥23,148.05 per share, while the current price is ¥53,030. That points to an overvalued outcome and raises a simple question for you: Which signal matters more, earnings multiples or cash flow?
Look into how the SWS DCF model arrives at its fair value.
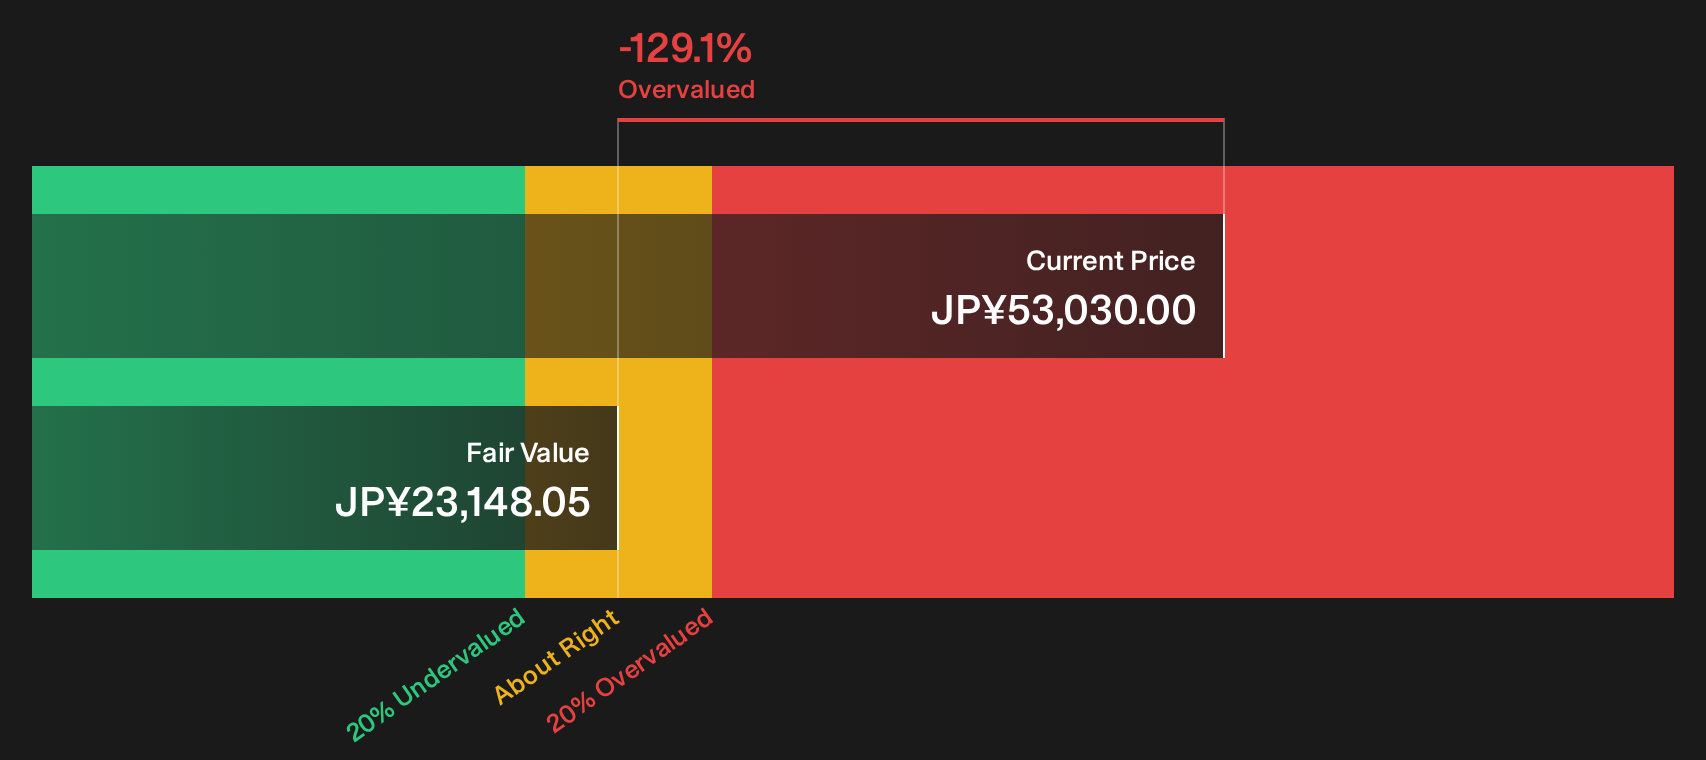
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Disco for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Disco is mixed, with upgraded forecasts on one side and valuation questions on the other. Move quickly and test the data against your own expectations. To see the full balance of risks and upsides before you decide where you stand, review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Disco?
Do not park all your attention on Disco. Use this moment to broaden your watchlist with other opportunities that match the style of portfolio you want.
- Target potential mispricing by checking companies that screen as high quality yet undervalued through the 18 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that feature in the 14 dividend fortresses.
- Dial down volatility risk by concentrating on resilient companies highlighted in the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com