


Castle Biosciences (CSTL) Opens Scottsdale Lab As Growth Narrative Keeps Valuation In Focus
Castle Biosciences (CSTL) just opened a 55,000 square foot laboratory and office facility in Scottsdale, Arizona, expanding its presence in the Phoenix area and giving investors additional context for the stock’s recent performance.
The Scottsdale expansion comes after a busy stretch for Castle Biosciences, with September’s Barrett’s esophagus study update and other product news, alongside a 90 day share price return of 52.25% and a 1 year total shareholder return of 53.86%. The 5 year total shareholder return remains down 46.20%, which indicates strong recent momentum but a still mixed longer term record.
Capitalize on Castle Biosciences' recent momentum by lining up similar healthcare stories with 38 healthcare AI stocks across the sector.That recent surge in Castle Biosciences, backed by new lab capacity and fresh Barrett’s data, could signal a business inflection or just hotter sentiment. How does the current valuation line up with those fundamentals?
Most Popular Narrative: 21% Undervalued
Analysts following Castle Biosciences see a fair value of $44.00 per share against a last close of $34.88, which frames the recent lab expansion as part of a broader long term thesis rather than a one off story.
Castle's rapid expansion of its test menu, especially into high-growth, underpenetrated indications like gastrointestinal diagnostics (TissueCypher) and new pipeline areas such as atopic dermatitis, positions the company to tap into substantially larger patient populations and diversify revenue streams, directly supporting long-term revenue growth.
See why 4 investors see Castle Biosciences as 21% undervalued.
The most followed narrative uses a 7.108% discount rate and a set of explicit assumptions on revenue, margins and earnings to reach that $44.00 figure. It ties the Scottsdale build out, Barrett’s esophagus data and broader test menu to a path where annual revenue growth of about 9.2% and a shift from losses toward profitability underpin the analyst price target range.
At the same time, the story leans heavily on execution around reimbursement and payer coverage. The same narrative highlights risks such as the noncoverage policy for DecisionDx SCC, heavier reliance on external funding and lower gross margins in some non dermatology tests, any of which could challenge the long term margin profile that sits behind the valuation work.
For investors, the gap between the $34.88 share price and the $44.00 narrative fair value frames a clear homework list. The key questions are whether Castle Biosciences can convert its clinical data, expanding lab footprint and experienced board and management team into sustainable earnings, while handling reimbursement pressure and competition in molecular diagnostics.
Result: Fair Value of $44.00 (UNDERVALUED)
Still, the narrative can crack if reimbursement for key tests like DecisionDx SCC remains constrained, or if lower margin assays such as TissueCypher weigh on profitability.
Find out about the key risks to this Castle Biosciences narrative.
Another View On Castle Biosciences’ Valuation
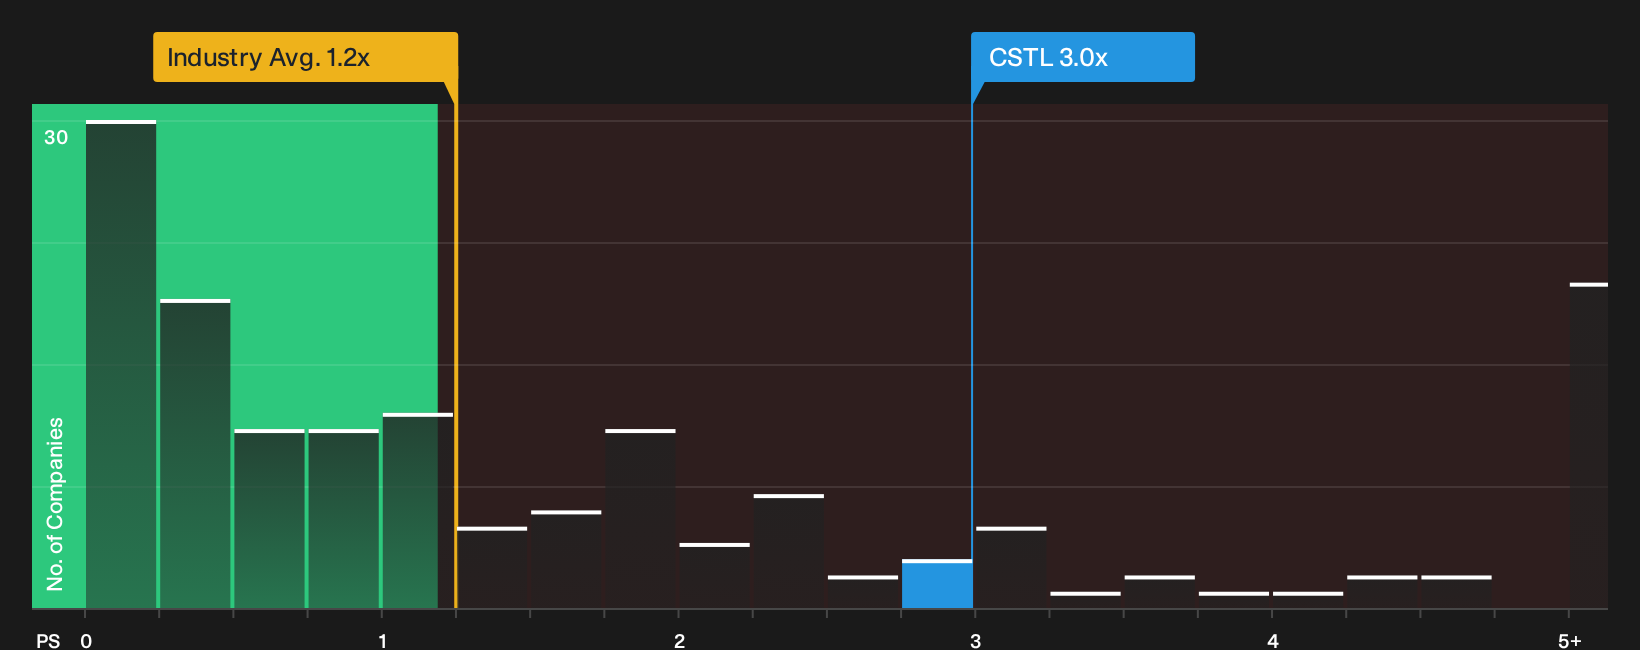
The earlier fair value work around $44.00 leaned on growth and margin forecasts. A simple P/S lens provides a different way to look at the price tag. Castle Biosciences trades at about 3x sales, compared with 0.9x for peers and 1.2x for the wider US Healthcare group, while the fair ratio sits closer to 3.2x. That mix implies investors are already paying a premium to the sector, even though the stock still sits slightly under the fair ratio. This raises the question of whether this is early in a rerating or already pricing in a lot of positive expectations.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Castle Biosciences is clear, with both risk flags and upside drivers on the table. Move quickly, dig into the details, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Castle Biosciences investment ideas?
If Castle Biosciences has you thinking harder about opportunities in healthcare and beyond, use that momentum and widen your search now with a few focused screens.
- Target resilient compounding potential by scanning a 30 high quality undervalued stocks that filters for quality and pricing support.
- Prioritize stability and sleep-better-at-night holdings through a 31 resilient stocks with low risk scores that keeps risk scores front and center.
- Hunt for tomorrow’s quiet winners by reviewing a 16 high quality undiscovered gems with strong fundamentals before the crowd gets there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com