


Western Union (WU) Stock Could Be Undervalued On Its Efficiency Program
Western Union has seen its share price under pressure in recent years, and the slide has sharpened again in 2026, which puts the focus squarely on whether the current valuation is still supported by its earnings power. With the market reacting to shifting business economics and new efficiency plans, the key issue for you is how much of Western Union's profit profile is already reflected in a US$6.09 share price.
- Over the past 5 years, Western Union stock has fallen 55%, which puts more weight on the question of how resilient its earnings base really is relative to what you are paying today.
- Recent margin pressure from a move toward more digital transactions, alongside a cost cutting program that targets US$50 million in savings, can influence how much sustainable profit the company may generate from its existing business model.
- Your read on Western Union is one view; the desks covering it have another. See what analysts think Western Union's shares could be worth.
For investors, the debate is whether Western Union's current earnings and their outlook are strong enough to justify the price implied by the stock today.
If Western Union's recent 5 year slide has you reassessing what you pay for an earnings story, a focused stock screen can be a useful second reference point in your research, especially 30 high quality undervalued stocks
Does Western Union Look Undervalued on Earnings?
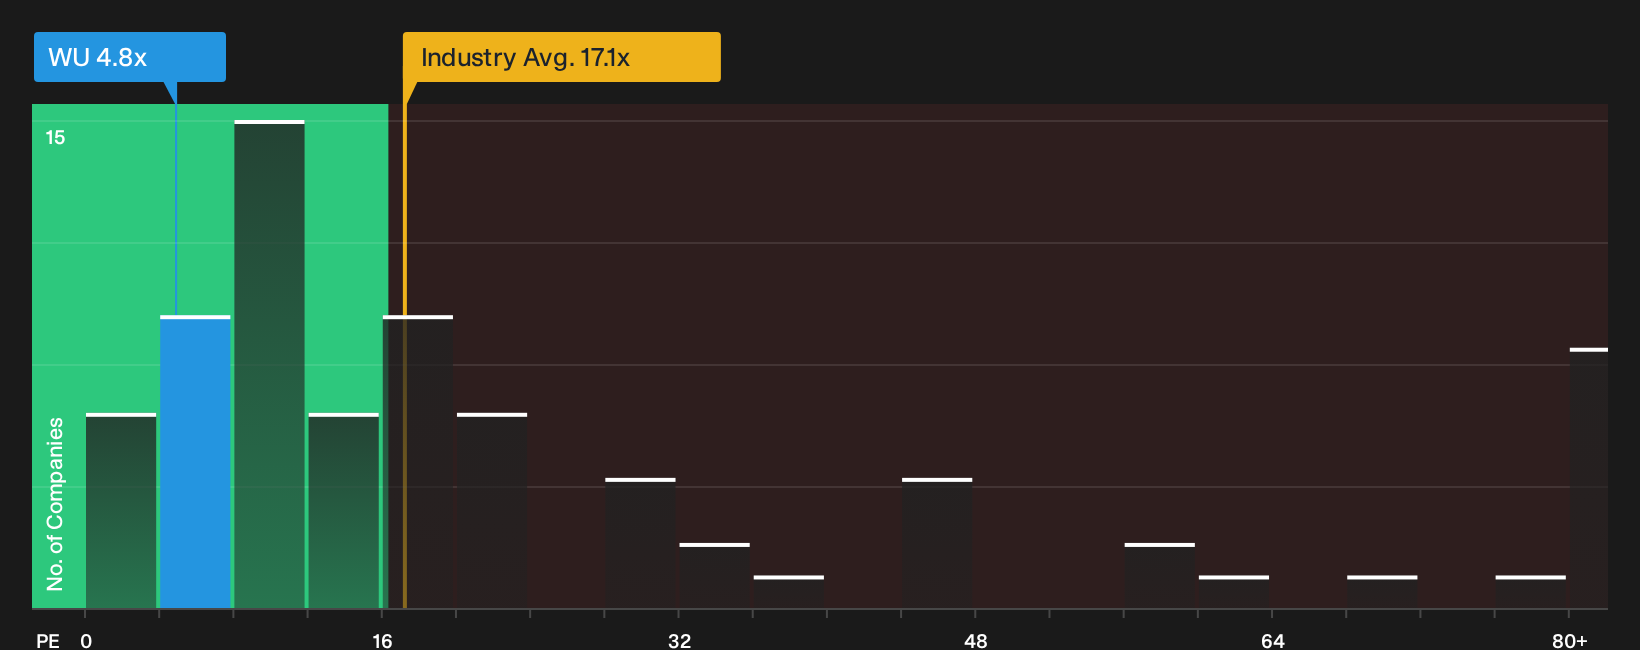
A P/E ratio fits Western Union because earnings still sit at the center of how holders judge this mature payments business. On current numbers, the stock trades on about 4.8x earnings, which is far below the diversified financial industry average of 17.1x and also well under a peer group closer to 44.4x. That is a large gap for a company that still reports positive net income and has a long operating history in money transfers.
Because the fair P/E implied by Western Union's own fundamentals screens higher than the market multiple, the shares currently look undervalued on this metric. The Q2 2026 update showed revenue and EPS under some pressure as customers shift toward digital channels. Yet the P/E still prices Western Union at a marked discount to both the tailored fair level and to sector norms, which leaves the earnings stream looking cheap relative to how similar businesses are valued. Explore the numbers behind Western Union's P/E valuation.
The Western Union Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Western Union's low P/E puzzle leaves off by setting out the specific paths for future growth, margins and earnings that would need to play out for the stock to be worth materially more or less than today’s market price. They sit on the Community page so you can see the story investors are debating.
Instead of giving a single output from a ratio or valuation model, Narratives unpack the underlying future that number depends on so you can watch in real time whether Western Union's actual progress lines up with that scenario or drifts away from it.
One of the top community narratives on Western Union: 14% undervalued
"Early strategic engagement with stablecoins and on-chain settlement technologies offers the potential to materially lower capital requirements and accelerate settlement speed..."
Discover why this Narrative puts Western Union at 14% undervalued.
One more angle on Western Union that could shift how you see the stock
The executives steering Western Union and the way their pay is structured can either reinforce or cut across the story implied by the current share price. See who runs Western Union and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com