


Life360 (ASX:360) Shares Look Reasonable Against Current Earnings Power
Life360 has been through a sharp reset in the share price, and the question now is whether what you pay today lines up with what the business actually earns. After such a volatile stretch, the focus naturally shifts to how much profit power the company’s current valuation assumes.
- Over the past 3 years, Life360 has delivered a total shareholder return of 121.5%, which puts a lot of past optimism about its earnings power under the microscope.
- The business model leans heavily on converting a large user base into recurring subscription and services income, which can be critical for how reliably earnings justify the current multiple applied to the stock.
- The analysts covering Life360 have run their own numbers. See what analysts think Life360's shares could be worth.
The issue now is whether the current A$19.23 share price is reasonably explained by Life360’s earnings when compared with the Fair Ratio benchmark.
If you want a wider earnings-focused watchlist alongside Life360, a simple next step is to scan for 6 high quality undervalued stocks as another starting point for research.
Is Life360 a Bargain on Earnings?
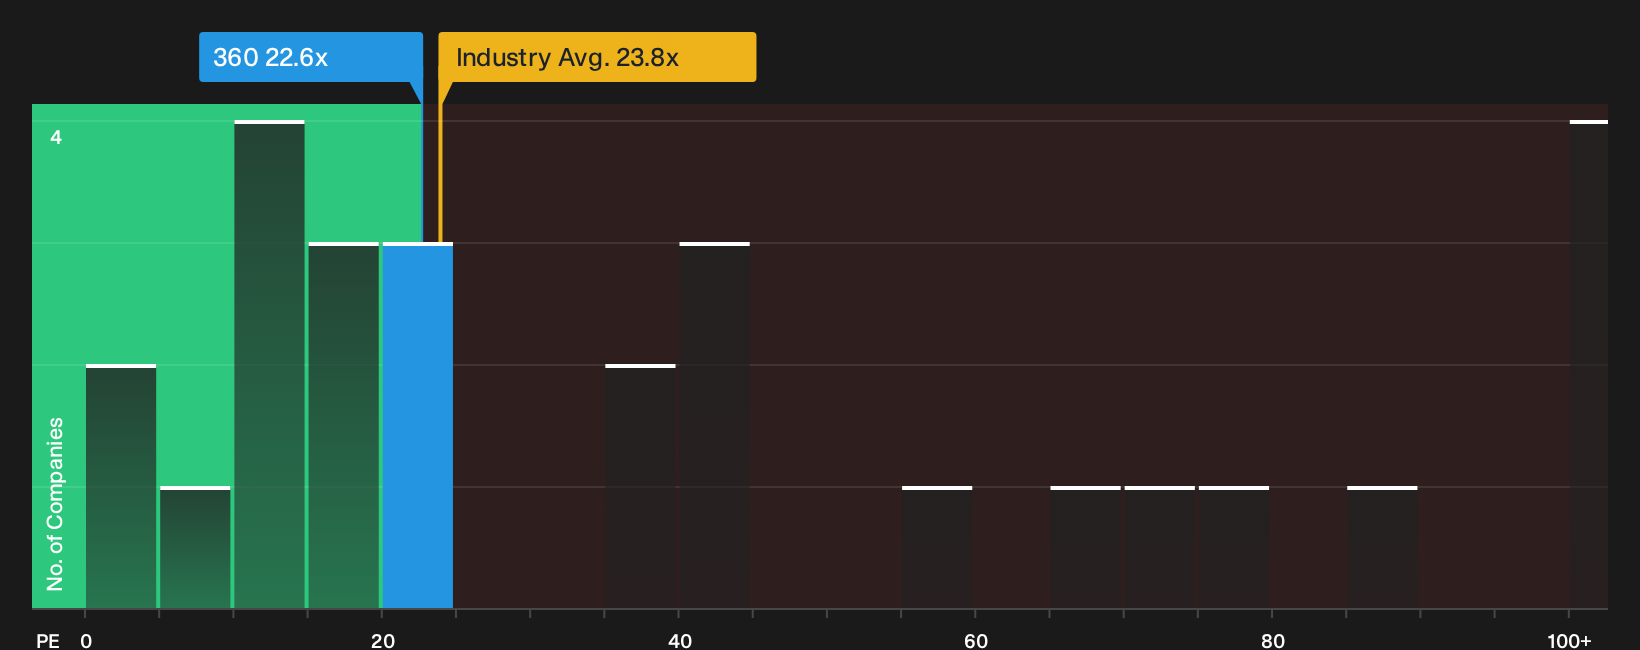
The P/E ratio works well for Life360 because the market is already keying off earnings rather than just revenue or assets. At the current A$19.23 share price, the stock trades on a P/E of about 22.6x, which is slightly below the broader software industry average of roughly 23.8x and well under the peer group on about 48.9x.
The Fair Ratio, which reflects what investors might typically pay given Life360’s growth profile, profitability, size and risk, sits above the present multiple, so the shares screen as undervalued on this framework. For anyone weighing whether the recent pullback has pushed Life360 to a more attractive entry point on earnings, it may be useful to focus on the gap between today’s P/E and that tailored benchmark as the key number to explore further. Explore the numbers behind Life360's P/E valuation.
The Life360 Narrative: What Would Justify Today's Price?
Life360’s Simply Wall St Narratives pick up where the P/E puzzle leaves off by spelling out which paths for revenue growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today’s price, and they sit on the company’s Community page. Rather than stopping at a single valuation output, they describe the future that number quietly relies on so you can watch how the real business lines up against it over time.
One of the top community narratives on Life360: 38% undervalued
"New premium services and integrated hardware deepen Life360's value proposition, increase member engagement, and create higher conversion to paid tiers..."
Discover why this Narrative puts Life360 at 38% undervalued.
One more angle on Life360 that deserves a closer look
Valuation only tells part of the story, and Life360 also has a set of risk checks that our research has flagged for closer review, which can materially shape how you weigh everything else you have just read. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com