


Toast (TOST) Is Back In The Spotlight, What Is Driving Attention?
Toast’s new partnerships put automation and multi-unit adoption in focus
Toast (TOST) drew fresh attention this month as Presto Phoenix joined its partner ecosystem and Kung Fu Tea agreed to roll out Toast hardware and payments across more than 330 locations.
Both deals point investors toward a simple question: How much value might come from deeper ties with restaurant chains that are leaning into automation and standardized point of sale setups at scale.
Toast’s recent partnerships arrive after a choppy run, with the share price at US$29.81 and a 30 day share price return down 18.8%, a 90 day share price return up 15.7%, and a 3 year total shareholder return of 59.7%. This points to momentum that has cooled in the short term, while the longer record remains stronger.
Scan beyond Toast and size up other restaurant and automation beneficiaries with the hand picked 94 robotics and automation stocks that is powering order efficiency and back-of-house workflows.
Toast trades about 26% below one intrinsic value estimate and roughly 31% under the average analyst target after a sharp pullback. Is that discount a margin of safety, or a warning that the market’s caution is warranted?
Most Popular Narrative: 23% Undervalued
Toast’s most followed narrative pegs fair value at $38.92, above the recent $29.81 close, which sets up a clear valuation gap for investors to weigh against execution risks in restaurant tech and automation.
The rapid adoption of integrated digital payment and ordering solutions, including mobile and contactless experiences, continues to expand Toast's addressable market. This positions the company to capture increased transaction volume and higher recurring fintech and software revenues as restaurants upgrade from legacy systems.
See why 80 investors see Toast as 23% undervalued.
Result: Fair Value of $38.92 (UNDERVALUED)
Still, Toast’s story can change quickly if restaurant spending softens further or if hardware costs and tariffs squeeze the already tight device economics.
Find out about the key risks to this Toast narrative.
Another View on Toast’s valuation
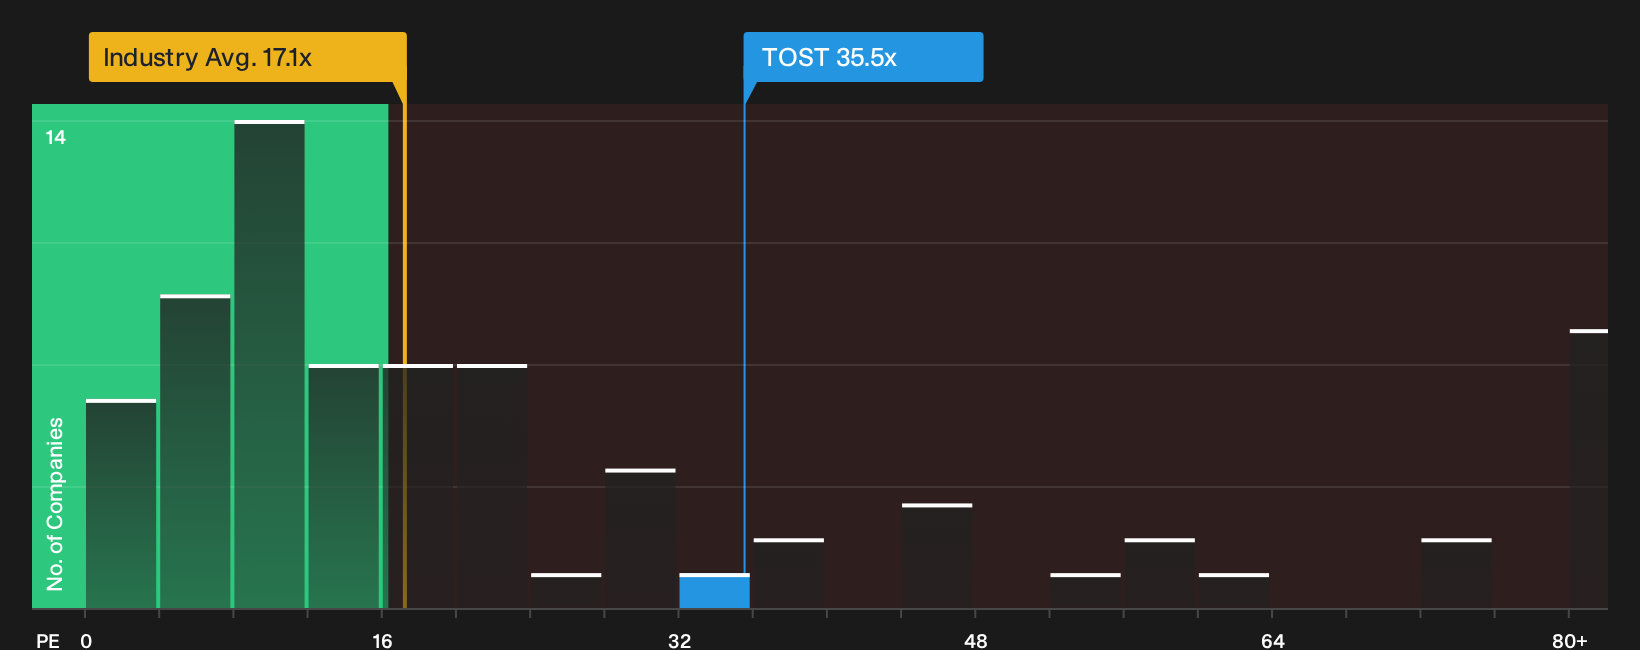
On simple price charts and one intrinsic value estimate, Toast looks underpriced at $29.81. The P/E ratio tells a very different story. At 35.5x earnings, the stock trades well above the US Diversified Financial industry on 17.1x and peers on 15.9x, and even its own fair ratio of 21.6x.
If the market moved closer to that 21.6x fair ratio, the current price would imply far less potential than headline discounts suggest. That leaves you weighing which signal matters more right now: the discounted cash flow view, or the richer earnings multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If Toast’s mixed signals leave you on the fence, move quickly to review the underlying drivers and decide where you stand on its upside. To see what the optimism is built on, start with the 4 key rewards.
Looking for more investment ideas beyond Toast?
Do not stop your research with Toast. Give yourself more options by scanning other opportunities that match your risk comfort and return goals.
- Target dependable income by reviewing companies in the 7 dividend fortresses that focus on steady cash returns.
- Hunt for potential mispricing by scanning the 30 high quality undervalued stocks that filters for quality fundamentals at compressed prices.
- Protect your downside by prioritizing resilience with the 31 resilient stocks with low risk scores that highlights businesses with stronger risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com