


How New ETF Funds At State Street (STT) Has Changed Its Investment Story
- State Street expanded its MyIncome ETF suite with three new actively managed target maturity bond ETFs and announced senior leadership changes across Alpha, enterprise operations, and Asia Pacific, all now in effect.
- The combination of fresh ETF product supply and a reorganized operating structure signals management attention on fee-based income, execution quality, and large-scale technology and AI programs across the platform.
- We will now explore how State Street's refreshed MyIncome ETF shelf could influence the existing investment narrative built around scale and efficiency.
State Street Investment Narrative Recap
To own State Street, you need to be comfortable with a fee based model that leans on sheer scale in custody, ETFs, and platforms like Alpha, while using technology and AI to keep costs in check. The near term story still hinges on execution against margin targets and the ability to keep extracting efficiencies from a very large operating base.
The biggest near term swing factor remains whether operating leverage holds up as ETF fee pressure and tech spending continue. Recent leadership changes around Alpha and enterprise operations look aimed at execution, but do not fundamentally change the main risk that costs, loss events, or weaker sentiment could challenge the margin narrative.
The leadership reshuffle around Alpha and enterprise operations is the clearest operational signal in the recent updates. Mostapha Tahiri taking full responsibility for Alpha and Charles River Development, while also chairing Asia Pacific, concentrates accountability for State Street’s core platform and a key growth engine inside one role.
At the same time, Ann Fogarty stepping into the enterprise COO seat ties the technology modernization and AI program directly to firmwide operations. For investors watching catalysts, the focus now is on whether this structure keeps the cost program on track, supports service quality across a US$57.9t AUC/A base, and limits operational risk as new products such as the expanded MyIncome ETF suite scale.
What The Current State Street Forecasts Assume
State Street's narrative projects US$17.5b revenue and US$4.7b earnings by 2029. This implies 5.3% yearly revenue growth and an earnings increase of about US$1.5b from US$3.2b today.
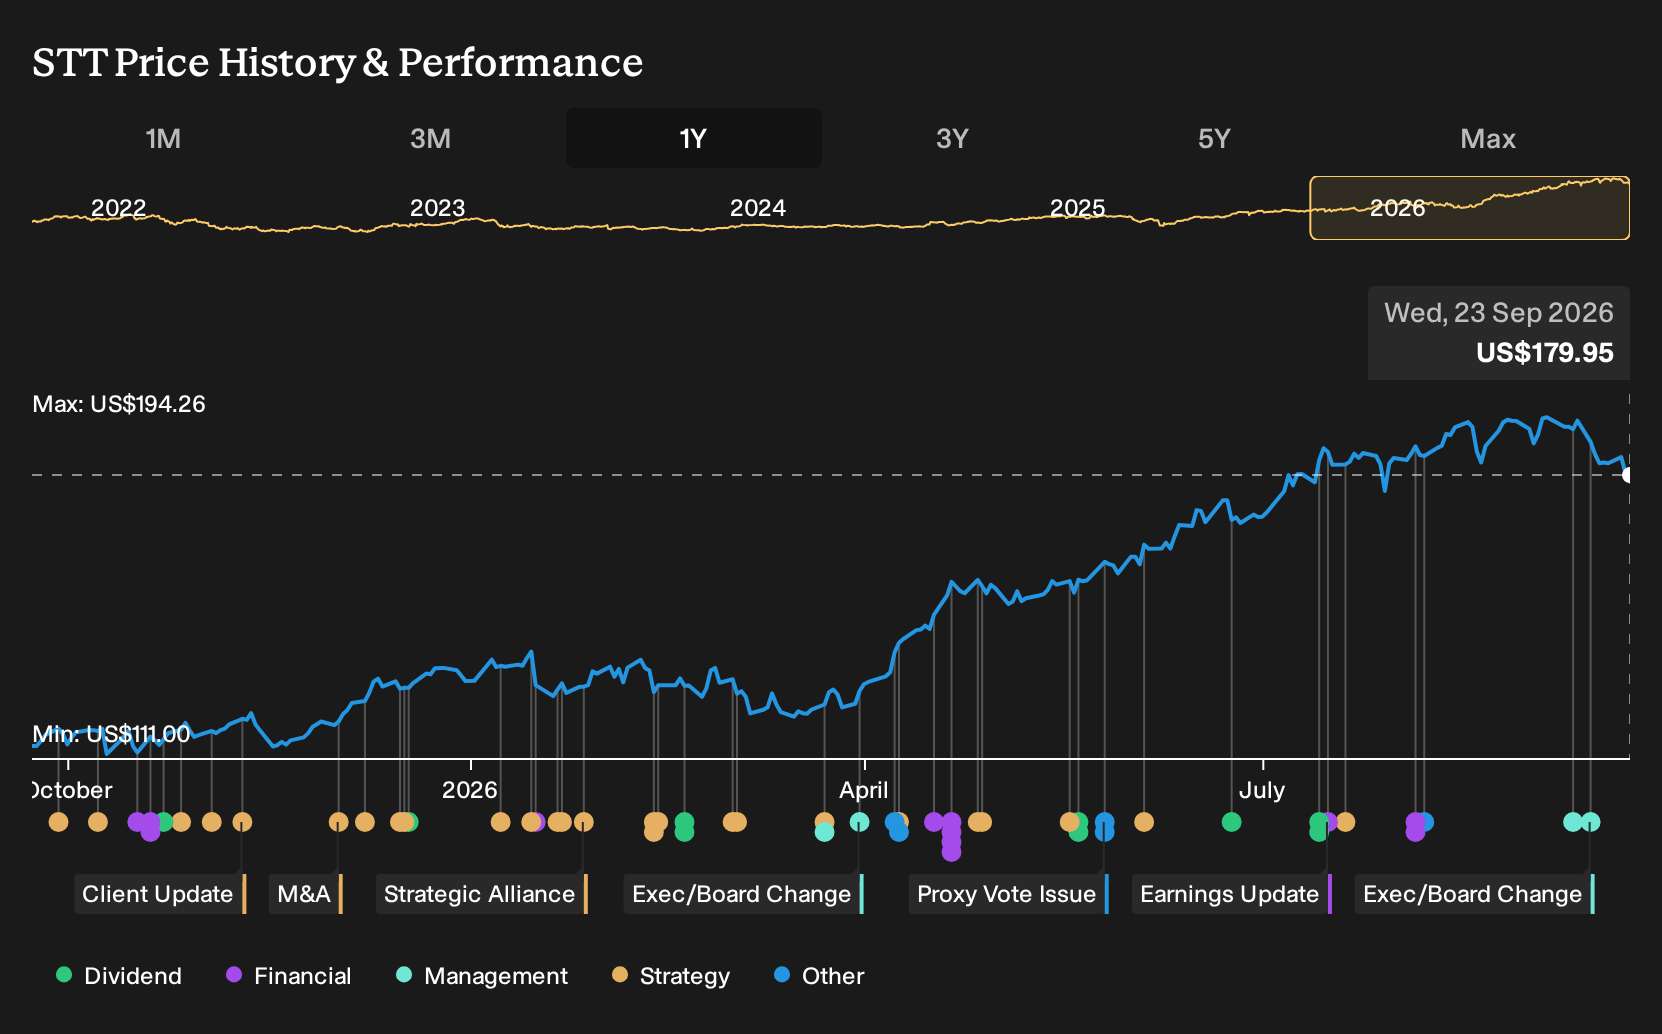
Discover how State Street's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fee risk around the expanded MyIncome ETF shelf is where the lowest State Street analysts lean hardest. They worry that higher costs for Alpha, digital assets and wealth projects leave less room to absorb thinner ETF pricing. This is why their 2029 view sits closer to US$17.4b revenue and US$4.3b earnings. Those estimates, set before these leadership moves, show how far opinions can stretch. Use that spread as a prompt to explore both the cautious and more upbeat cases yourself as this new information filters into future forecasts.
Explore 2 other State Street fair value estimates, including one that suggests it could be worth just $183.49.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your State Street research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for State Street. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate State Street's overall financial health at a glance.
Looking for more investment ideas beyond State Street?
Once you have a handle on where State Street fits in your plan, it can help to scan a wider field of companies that share the kind of balance sheets, cash flows, or income profiles you want in your portfolio.
- If you want potential mispricing plus quality, start with a curated group of 30 high quality undervalued stocks that pair fundamentals with disciplined financial profiles.
- For investors who care most about resilience, check out a focused 31 resilient stocks with low risk scores that aims to keep volatility in the background rather than the headline.
- To widen the opportunity set without sacrificing financial strength, use a 16 high quality undiscovered gems that highlights lesser known businesses with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com