


Is MARA Holdings (MARA) Getting Too Expensive For Its Sales?
MARA Holdings has seen its share price swing sharply in recent years, which puts a fresh spotlight on a simple question for investors who care about fundamentals. Is the current valuation of the stock really supported by the sales the business is generating today?
- Over the past 3 years the stock has gained 66.7%, which raises the question of whether the underlying sales base can carry that kind of share price journey.
- The company recently bought 1,292 Bitcoin worth about US$98.64 million, a move that may affect how much of its value investors tie to mining driven revenue versus the sales of newly produced coins over time.
- The analysts covering MARA Holdings have run their own numbers. See what analysts think MARA Holdings's shares could be worth.
The issue now is whether MARA Holdings' current share price at around US$13.35 is reasonable when stacked up against the sales its business is producing.
If you want to test the same sales driven valuation question beyond MARA Holdings, compare it against a wider universe of 30 high quality undervalued stocks.
Is MARA Holdings Getting Expensive on Sales?
P/S is a useful yardstick for MARA Holdings because investors often focus more on revenue and asset value than on near term profits for Bitcoin exposed businesses.
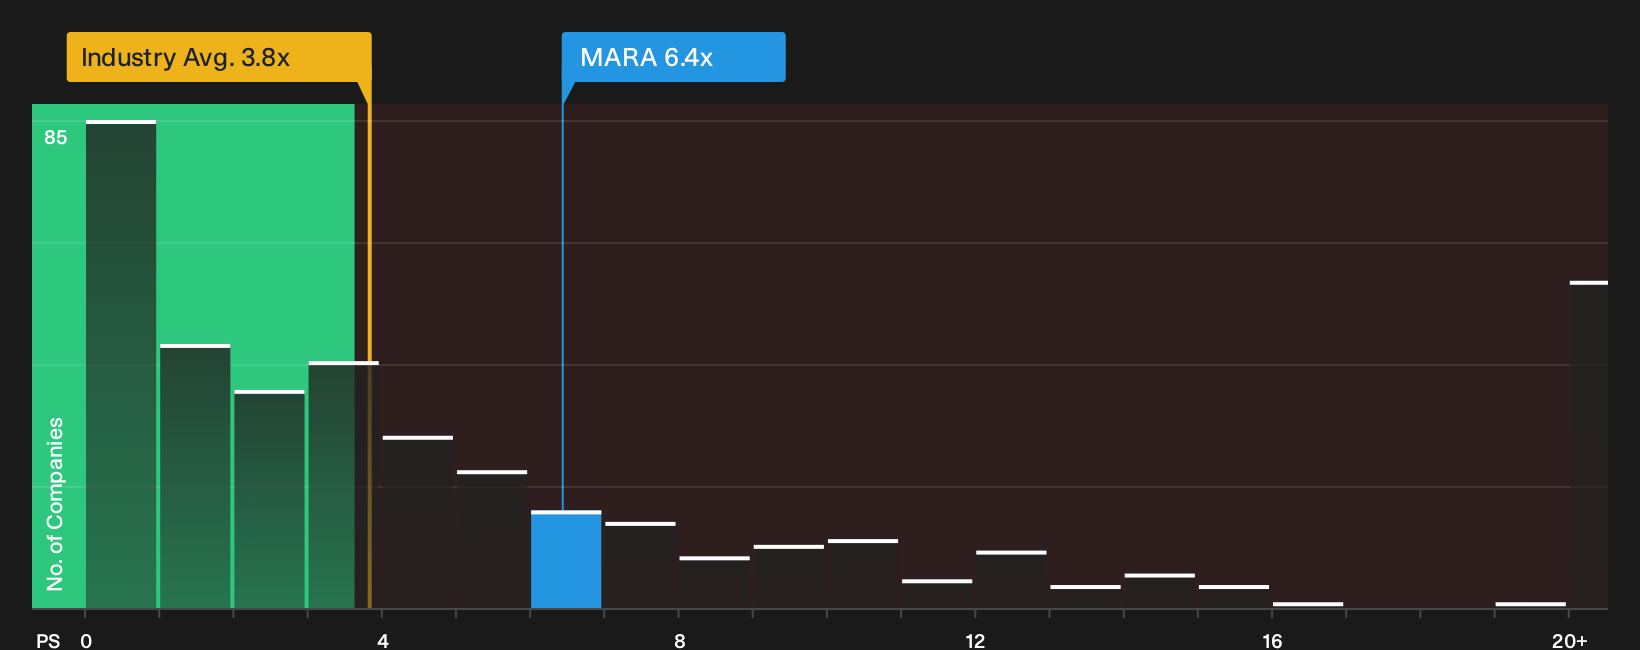
The stock trades on a P/S of about 6.4x, which is higher than the broader Software industry average of roughly 3.8x but lower than the peer group average of around 15.4x. The tailored fair multiple from the model sits well below the current 6.4x, which flags MARA Holdings as overvalued on this framework. Because the fair benchmark is so much lower, the gap suggests the model is heavily penalising the company for its current losses, risk profile and the quality of its revenue, rather than pointing to a precise target level for the shares.
Despite the recent US$98.64 million Bitcoin purchase adding to the asset base and attracting attention, the valuation still prices MARA Holdings at a relatively high P/S level compared with what this model implies for its fundamentals. Explore the numbers behind MARA Holdings's P/S valuation.
The MARA Holdings Narrative: What Would Justify Today's Price?
Narratives on MARA Holdings pick up where the P/S puzzle leaves off by outlining which paths for future growth, profitability and earnings power would align with a meaningfully higher or lower share price than today, and they sit on Simply Wall St's Community page. Each scenario connects its number to a specific view on how revenue expansion, margin strength and business risk might evolve, giving you a reference point you can revisit as fresh information comes through.
Views on MARA Holdings split between investors who see the Texas power build out as underpriced and those who think the Bitcoin exposure still carries too much risk.
Bull case: 26% undervalued
"A robust pipeline of 3+ gigawatts for global infrastructure projects and deliberate investment in proprietary R&D solidify MARA's ability to launch new solutions ahead of peers..."
Discover why this Narrative puts MARA Holdings at 26% undervalued.
Bear case: 21% overvalued
"MARA Holdings' heavy reliance on Bitcoin mining exposes it to extreme volatility in Bitcoin prices and potential long periods of price decline..."
Explore why this Narrative puts MARA Holdings at 21% overvalued.
Before deciding on MARA Holdings, there is one more angle to check
Current pricing only tells you what the market is paying today, while professional models sketch where they think this business could be a few years from now. This gives you a different benchmark to compare with the present picture. Explore where analysts expect MARA Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com