


Tourmaline Oil (TSX:TOU) Sells Topaz Shares And Lifts Dividend, Is The Stock Undervalued?
Tourmaline Oil (TSX:TOU) just paired a CA$287.5 million sale of 10 million Topaz Energy shares with a 5% bump to its quarterly base dividend, putting capital returns firmly in focus for shareholders.
At a share price of CA$61.16, Tourmaline Oil has seen a 1-day share price return of 2.09% and a 90-day share price return of 1.90%. The 1-year total shareholder return is 0.56%, and the 5-year total shareholder return is 102.90%. This indicates that short-term momentum is modest, while the longer-term track record is significantly stronger.
Scan other Canadian energy plays built around disciplined cash returns with our curated list of 1 dividend fortresses.
Bulls view Tourmaline Oil’s move to sell Topaz, repurchase its own shares, and increase the dividend as evidence that the current valuation is too low. Skeptics highlight commodity risk and recently muted returns. Which side do the numbers appear to support?
Most Popular Narrative: 14% Undervalued
Tourmaline Oil’s most followed valuation view pegs fair value at CA$71.45, above the last close of CA$61.16. This puts recent buybacks and dividend moves in a different light for anyone tracking upside versus current pricing.
Increasing international demand for lower-carbon energy is creating new export opportunities for Canadian natural gas. Tourmaline's long-term LNG supply agreement with Uniper and secured firm transportation to the U.S. Gulf Coast will provide direct access to premium global markets and pricing, increasing future revenues and cash flow.
See why 102 investors see Tourmaline Oil as 14% undervalued.
Result: Fair Value of CA$71.45 (UNDERVALUED)
Still, the whole Tourmaline Oil narrative leans heavily on volatile natural gas pricing and large, long-term capital commitments that could pressure future cash returns.
Find out about the key risks to this Tourmaline Oil narrative.
Another View: Tourmaline Oil Looks Expensive On Earnings
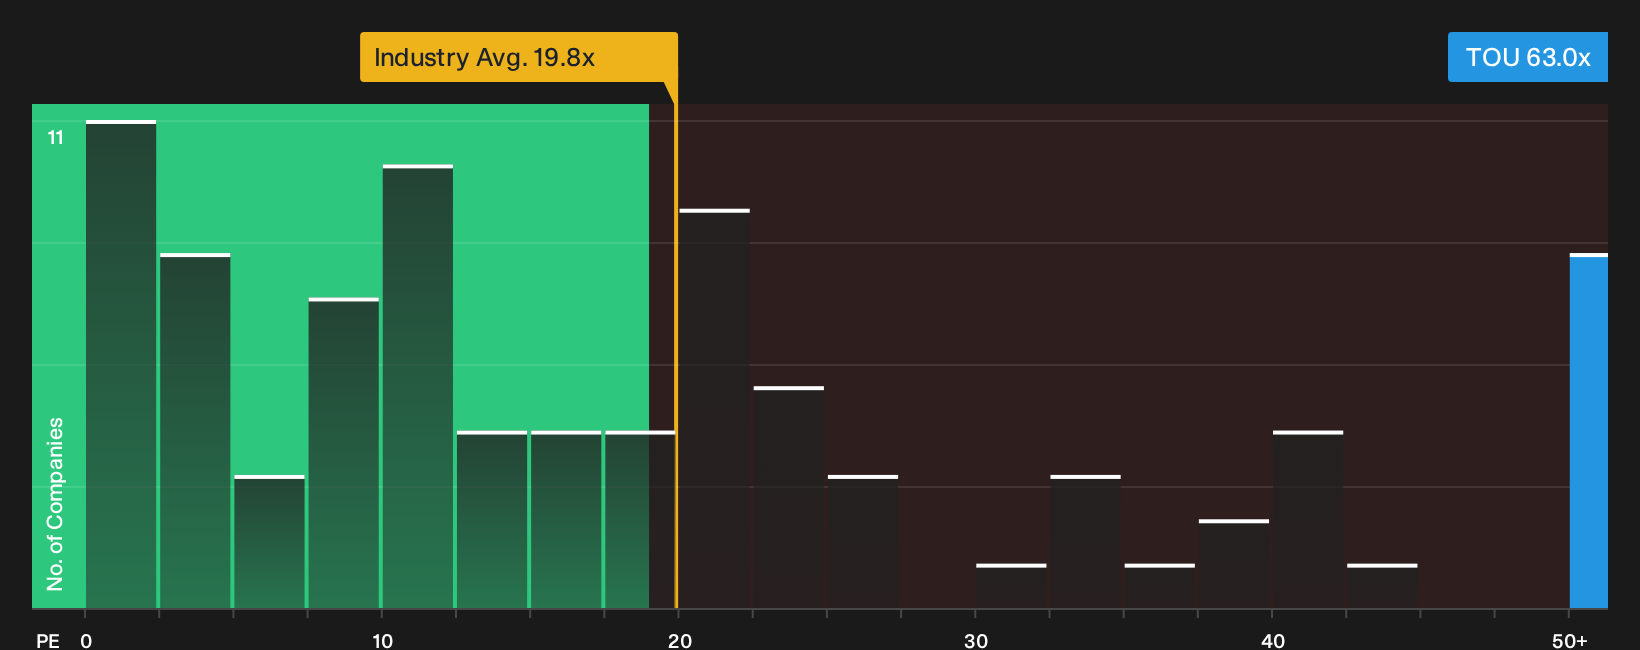
Tourmaline Oil screens very differently once you switch from analyst fair value estimates to the current P/E ratio. The stock trades at 63x earnings compared with about 19.8x for the Canadian oil and gas group and a fair ratio of 25.5x, which suggests a lot of good news is already priced in. If the share price ever drifted closer to that fair ratio, how comfortable would you feel owning the downside risk from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Tourmaline Oil currently sits between a potential valuation upside story and concerns about risk. If you want to move quickly and form your own view, start by weighing the stock's 2 key rewards and 3 important warning signs.
Ready for more ideas beyond Tourmaline Oil?
If Tourmaline Oil has you thinking harder about value and risk, do not stop here. Use targeted screens to spot fresh opportunities before the crowd moves.
- Zero in on resilient balance sheets by reviewing a curated list of solid balance sheet and fundamentals (7 results) that filters for financial strength and staying power.
- Hunt for mispriced quality by scanning a focused 6 high quality undervalued stocks built around strong fundamentals and supportive valuations.
- Target income-focused opportunities by checking a handpicked 1 dividend fortresses that screens for higher-yield payouts with supporting financial metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com