


Ambarella (AMBA) Could Be 24% Undervalued On Its Edge AI Platform Expansion
Ambarella (AMBA) expanded its Developer Zone on 15 September 2026, adding a cloud-hosted IDE, agentic AI tools on Google Cloud and deeper ties with ZEDEDA and Ultralytics for edge AI deployment.
Recent product updates and partnerships appear to be feeding into sentiment around Ambarella, with the 7-day share price return of 7.73% and 90-day share price return of 5.47% contrasting with a year-to-date share price decline of 10.03% and a 1-year total shareholder return decline of 20.15%. This suggests that near term momentum is firming, while longer term performance remains pressured.
Scan how Ambarella’s edge AI push compares with other chip makers by reviewing our hand picked 85 AI infrastructure stocks in the sector.
Ambarella shares have rebounded in recent days, yet still trade at a sizeable gap to analyst targets and some intrinsic value estimates. Is that discount compensation for risk, or a genuine mispricing?
Most Popular Narrative: 24% Undervalued
Against Ambarella's last close of $67.62, the most widely followed valuation narrative points to a fair value of $89.36 using an 11.22% discount rate. That gap puts the spotlight firmly on whether edge AI design wins can justify the implied step up in earnings power.
Sharply increasing demand for AI-powered edge devices including portable video, robotics (notably aerial drones), and edge infrastructure has led to a rapid expansion of Ambarella's addressable markets, as evidenced by record edge AI revenue and multiple recent, diversified design wins. This is catalyzing strong, sustained revenue growth and positions Ambarella to benefit further as additional vertical applications for edge AI proliferate.
See why 40 investors see Ambarella as 24% undervalued.
Result: Fair Value of $89.36 (UNDERVALUED)
Still, Ambarella’s reliance on IoT demand and concentrated Asian distribution partners means any order cuts or regional disruptions could quickly challenge that view of the shares being 24% undervalued.
Find out about the key risks to this Ambarella narrative.
Another View: Ambarella Through Sales Multiples
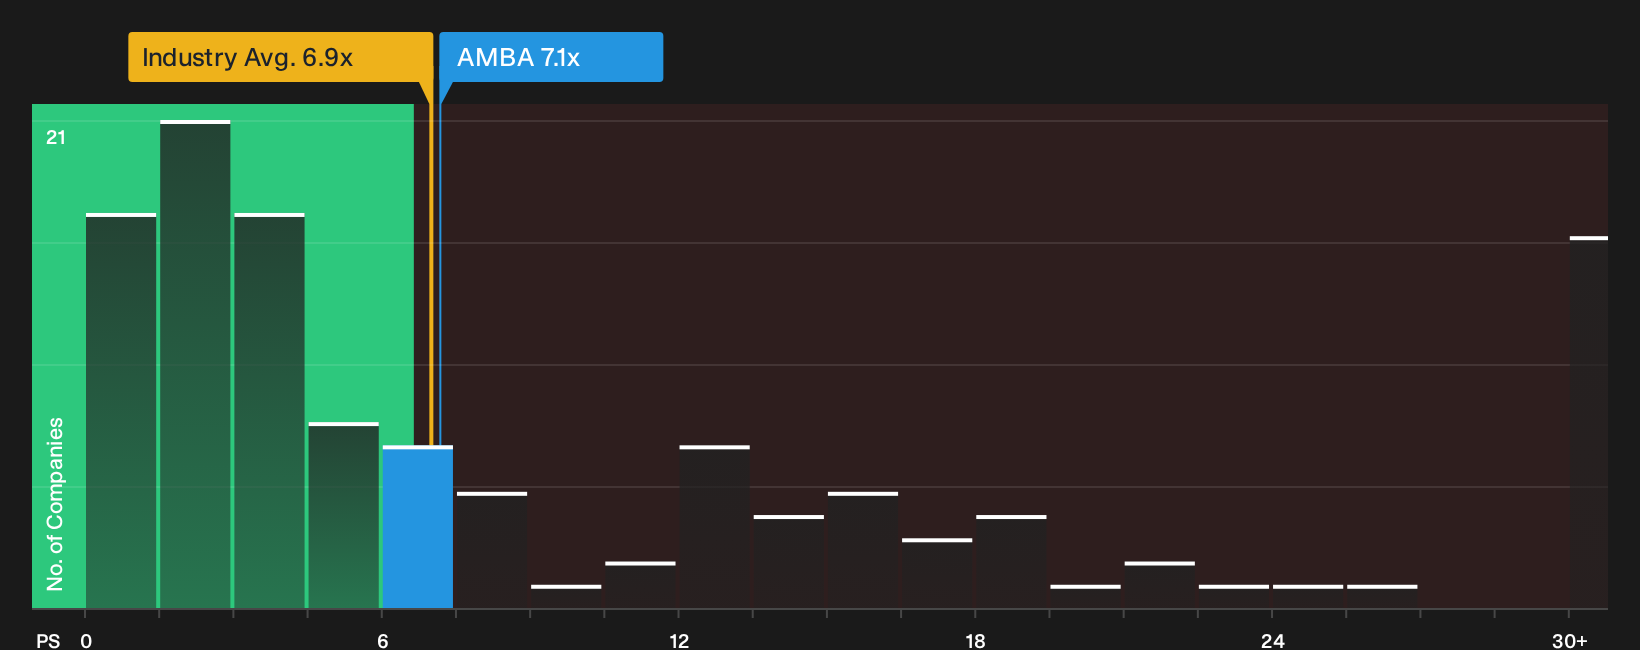
While the leading Ambarella narrative leans on a fair value of $89.36, the market’s own yardstick sends a different signal. On a P/S of 7.1x, the stock trades richer than the US Semiconductor industry at 6.9x, peers at 4.3x, and a fair ratio of 5.4x. That gap points to higher expectation risk, so how comfortable are you paying a premium today?
See what the numbers say about this price in more detail with our valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through the Ambarella story so far, the mix of cautious signals and upside arguments is hard to ignore, so act while the data is fresh and test the thesis yourself. To weigh both sides properly, start with a clear view of the 2 key rewards and 3 important warning signs.
Looking for more Ambarella style investment ideas?
Do not stop with Ambarella. Use the Simply Wall Street Screener to scan fresh opportunities, compare quality and risk, and pressure test your watchlist against new ideas.
- Target quality at a discount and see which companies look mispriced on fundamentals through the 30 high quality undervalued stocks.
- Prioritise resilience and focus on businesses with sturdier finances by running your filters against the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential standouts early and track under-the-radar prospects using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com