


Paycom (PAYC) Stock Looks Fully Priced Following Strong Q2 Results
Paycom Software has delivered a strong year to date share price gain, yet over the past 5 years the stock has lagged sharply, which puts fresh focus on whether the current valuation still lines up with its earnings power. Recent upbeat news on the business has stirred interest again, and the core issue for investors is how much of that optimism is already reflected in the price.
- The share price has fallen 54.0% over 5 years, which raises the question of how closely the current market value tracks the company’s underlying earnings profile over that period.
- Management recently reported higher revenue and stronger profitability than many analysts had expected, which can support arguments that earnings may justify a fuller valuation if those trends prove durable.
- There is a second opinion on Paycom Software worth weighing. See what analysts think Paycom Software's shares could be worth.
For investors, the debate is whether Paycom Software's current share price around US$221.68 is appropriately supported by the earnings the business is generating today.
If you want to balance Paycom Software's story with other possibilities, a focused stock screen can be a useful second lens. You can start with 30 high quality undervalued stocks.
Does Paycom Software Look Fairly Valued on Earnings?
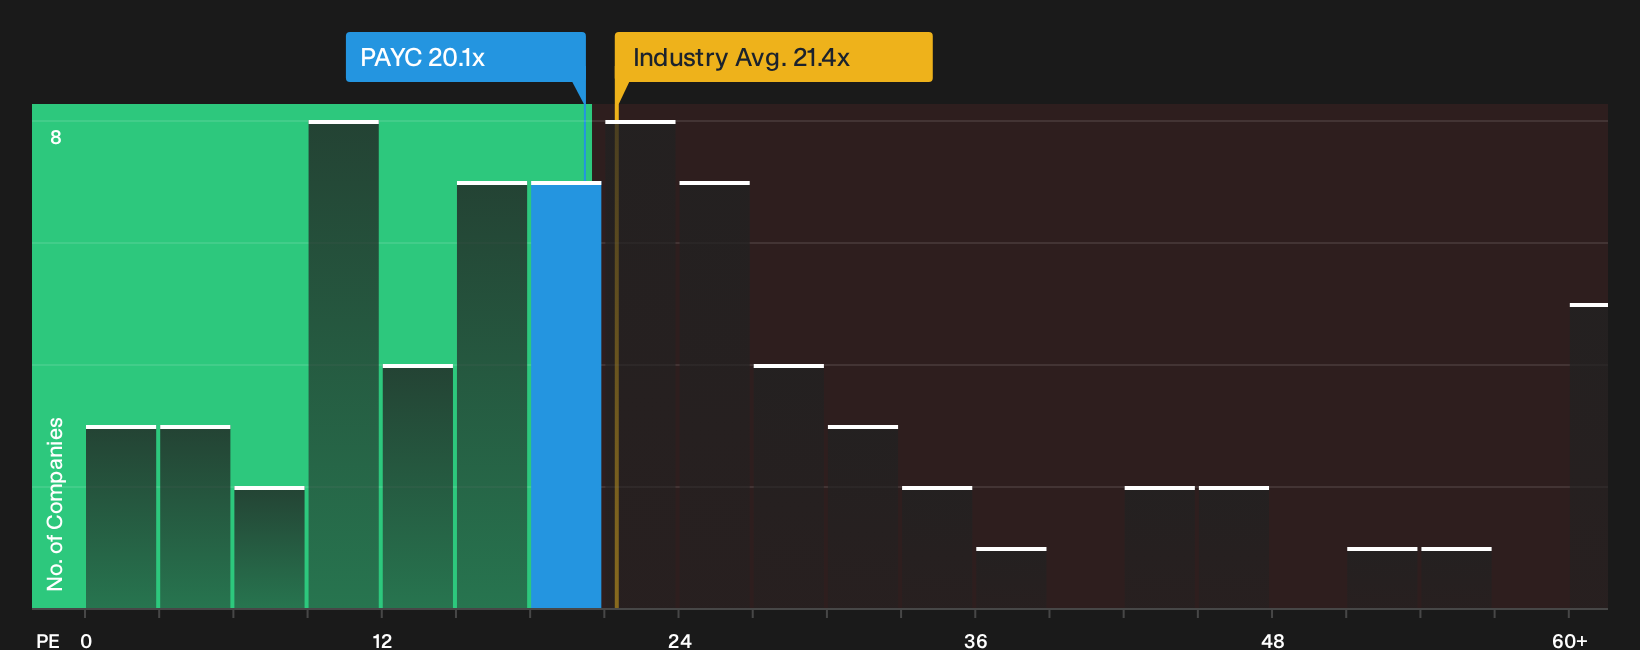
The P/E ratio suits Paycom Software because earnings are a key driver of how investors frame its value today. On this metric, the stock trades on a P/E of 20.1x compared with a Professional Services industry average of about 21.4x and a peer group around 17.3x. That leaves the shares priced slightly below the broad sector but somewhat richer than closer peers.
The Fair Ratio model, which blends factors such as profitability profile, market size and risk, points to a P/E level that is close to where Paycom Software is currently trading. Because the strong Q2 earnings beat has already pushed the share price higher, the current multiple suggests the recent good news is largely recognised, rather than the stock sitting at a clear discount or premium on earnings. Explore the numbers behind Paycom Software's P/E valuation.
The Paycom Software Narrative: What Would Justify Today's Price?
Narratives for Paycom Software pick up where this valuation puzzle leaves off by explaining which expectations on growth, margins and earnings would need to hold for the stock to appear meaningfully higher or lower than today. This is done using a set of scenarios on Simply Wall St's Community page. Each one treats Paycom Software's fair value as a thesis about how the business could develop that you can revisit over time, rather than a one off snapshot.
Community views on Paycom Software split between a rerating story driven by automation and a more cautious take on how much is already priced in.
Bull case: 22% undervalued
"Automation across service, support and G&A, reflected in a 20% to 30% year over year decline in internal tickets and call volume, points to a structure that can support higher scale without a similar increase in headcount…"
Discover why this Narrative puts Paycom Software at 22% undervalued.
Bear case: 39% overvalued
"Although command driven automation through IWant and Beti is reducing service tickets by 20% to 30% and improving client ROI, competitors are likely to fast follow with similar capabilities…"
Explore why this Narrative puts Paycom Software at 39% overvalued.
The Paycom Software price is only one piece of the decision
Before you treat Paycom Software as a simple story about earnings and multiples, it is worth checking the specific business risks that recent analysis has flagged for closer inspection. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com