


What Banco BPM Stockholders Should Know About Its Green Bond Refinancing
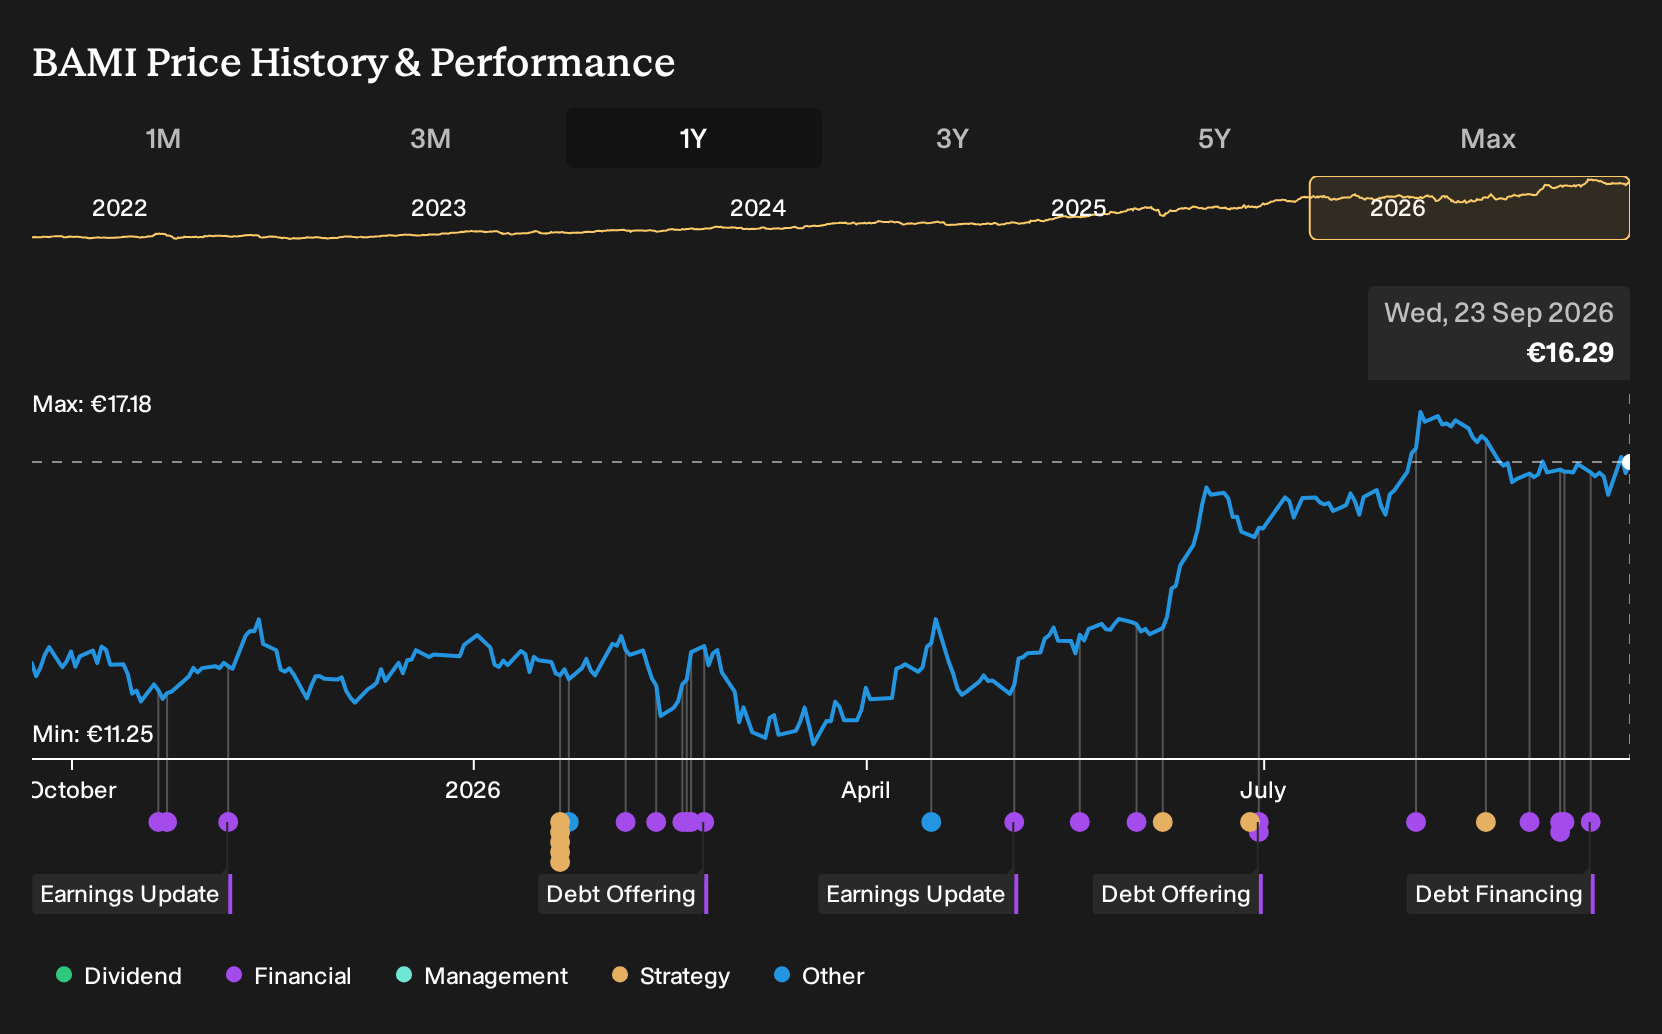
- Banco BPM completed a refinancing of its €500,000,000 fixed rate social senior preferred notes due November 29, 2027, buying back €263,498,000 via tender while issuing €750,000,000 in callable fixed to floating senior non preferred European green bonds due September 2032.
- The move shifts a large portion of funding into a green bond format and lengthens maturities. This reshapes Banco BPM's funding mix, interest profile and sustainability credentials at the same time.
- We will now examine how Banco BPM's new callable green bond funding and partial note buyback could reshape its longer term investment narrative.
Banco BPM Investment Narrative Recap
To hold Banco BPM stock, you need to be comfortable with a traditional Italian bank that leans heavily on fee income, cost efficiency work and improved credit quality to support earnings. The recent refinancing, including the new €750,000,000 callable green bond, mainly affects the liability side and does not materially alter that operating story by itself.
In the near term, the key debate still sits around how durable fee based revenue is after past M&A and how far cost savings and digital projects can go before they level off. The main operational risk remains credit, given a 2.2% bad loan ratio and a relatively low 6% allowance for those exposures.
The green bond and partial buyback link most directly to funding costs and capital flexibility. Management has replaced a portion of shorter dated social senior preferred notes with longer dated senior non preferred paper, which may influence the interest line and future buffers but leaves the core lending and fee engines untouched.
For catalysts, investors are still watching the same things: execution on wealth and asset management integration, keeping the cost/income ratio in the low to mid 40s, and maintaining asset quality with NPL and coverage metrics consistent with recent levels. Those factors appear likely to matter more to Banco BPM’s equity story than this single refinancing step.
What The Earnings Path Implies For Banco BPM
Banco BPM's analyst narrative points to forecast revenue of €6.8 billion and earnings of €2.3 billion by 2029. That outlook assumes revenue grows at 8.3% per year and earnings rise by about €0.4 billion from €1.9 billion today.
Uncover why Banco BPM's fair value suggests Banco BPM is fairly valued at its current price.
Exploring Other Perspectives
Fair value estimates for Banco BPM from three members of the Simply Wall St Community cluster in a tight €15.88 to €17.20 range, which still leaves room for very different conclusions about upside or downside. When you set that against risks around fee income durability, cost efficiency and digital competition, you start to see why opinions can diverge sharply. Explore several of these Community viewpoints before deciding how this refinancing fits your own thesis.
Explore 2 other Banco BPM fair value estimates, including one that suggests it could be worth just €15.88.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco BPM research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banco BPM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco BPM's overall financial health at a glance.
Looking For More Banco BPM Style Ideas?
If the Banco BPM story has sharpened your thinking on funding, risk and valuation, it can help to compare it with a wider set of opportunities. The Simply Wall St Screener lets you line up other stocks against the same checklist you are using here and see which ones truly fit your approach.
- If you want potential value with quality metrics in mind, scan a 173 high quality undervalued stocks that already pass a high bar on fundamentals.
- For investors who care most about balance sheet strength and resilience, filter for a list of solid balance sheet and fundamentals (198 results) that may better match your risk tolerance.
- If you are hunting for less followed ideas with strong underlying numbers, start with a 620 high quality undiscovered gems that might not yet be widely discussed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com