


Asian Value Picks Trading Below Estimated Worth In September 2026
In September 2026, Asian markets are navigating a complex landscape marked by fluctuating oil prices and central bank rate hikes, as seen with Japan's recent monetary policy adjustments. Despite these challenges, opportunities arise for discerning investors to identify undervalued stocks that may be trading below their estimated worth. In such an environment, a good stock might be one that demonstrates strong fundamentals and resilience amidst broader economic uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wacom (TSE:6727) | ¥842.00 | ¥1594.89 | 47.2% |
| Shizuki Electric (TSE:6994) | ¥1208.00 | ¥2298.73 | 47.4% |
| Rakus (TSE:3923) | ¥1082.00 | ¥2062.22 | 47.5% |
| PAL GROUP Holdings (TSE:2726) | ¥1486.00 | ¥2879.71 | 48.4% |
| Niterra (TSE:5334) | ¥7218.00 | ¥13807.45 | 47.7% |
| Kingnet Network (SZSE:002517) | CN¥16.38 | CN¥31.44 | 47.9% |
| Ichikoh Industries (TSE:7244) | ¥565.00 | ¥1073.63 | 47.4% |
| China Coal Energy (SEHK:1898) | HK$10.49 | HK$20.09 | 47.8% |
| Cheil Worldwide (KOSE:A030000) | ₩17680.00 | ₩33796.80 | 47.7% |
| AK Medical Holdings (SEHK:1789) | HK$4.905 | HK$9.53 | 48.5% |
Below we spotlight a couple of our favorites from our exclusive screener.
Shinhan Financial Group (KOSE:A055550)
Overview: Shinhan Financial Group Co., Ltd. offers a range of financial products and services across South Korea, Vietnam, and Japan, with a market cap of ₩51.31 trillion.
Operations: The company generates revenue from several segments including Banking (₩9.77 billion), Securities (₩1.88 billion), Credit Card (₩1.68 billion), Insurance (₩889.09 million), and the Specialized Department of Women (₩156.31 million).
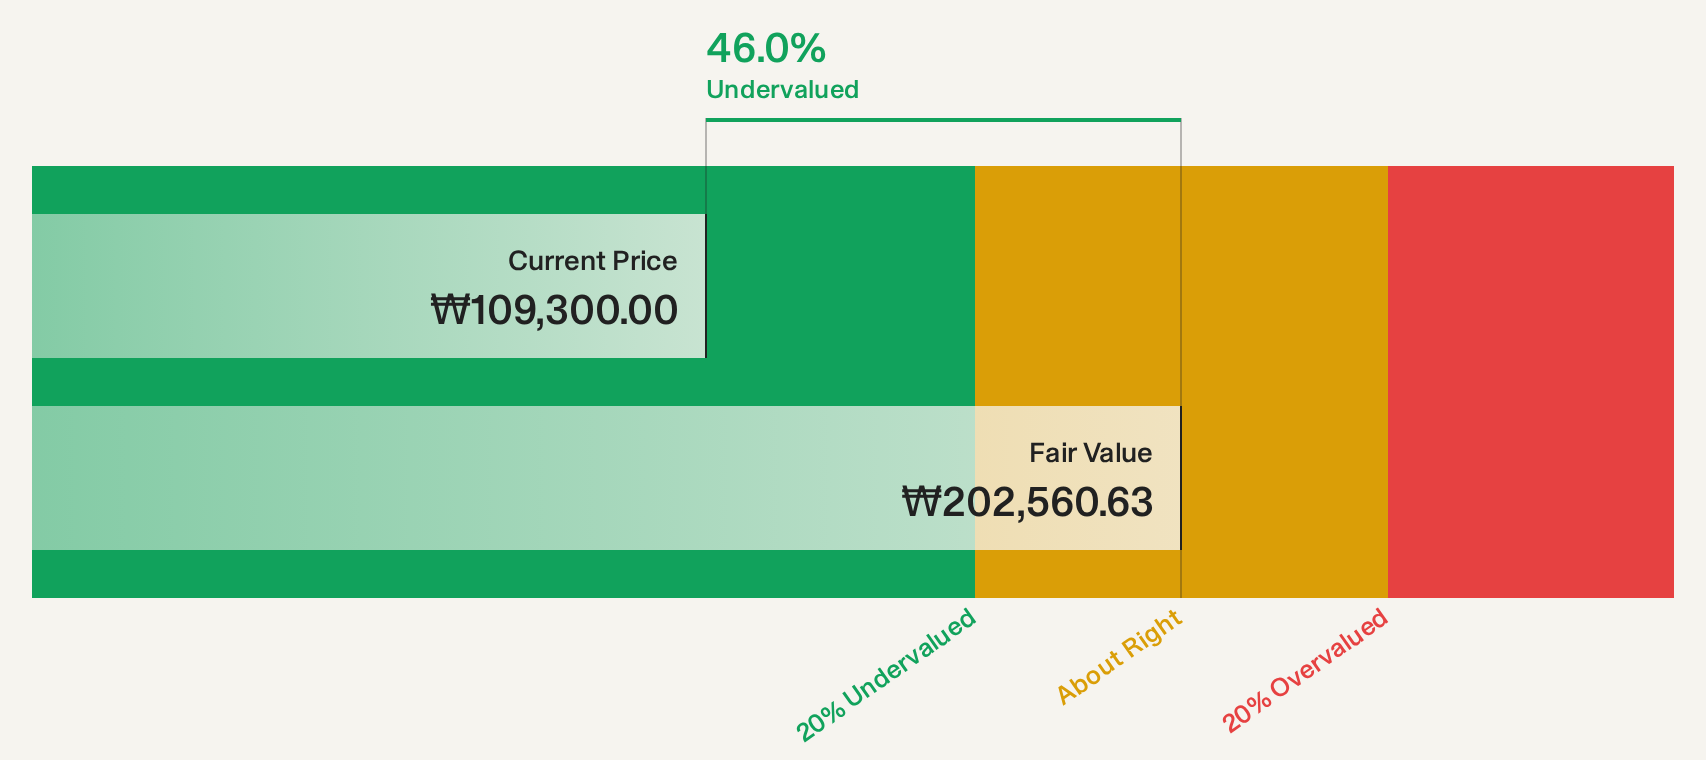
Estimated Discount To Fair Value: 46%
Shinhan Financial Group appears undervalued based on cash flows, trading at 46% below its estimated fair value of ₩202,560.63 per share. Despite a forecasted earnings growth of 8.1% annually, slower than the market average, Shinhan's strategic initiatives include a share buyback program and potential acquisition of Lotte Non-Life Insurance to enhance competitiveness. Although revenue is expected to decline by 2.8% annually over three years, analysts anticipate a stock price rise by 21.6%.
- Our growth report here indicates Shinhan Financial Group may be poised for an improving outlook.
- Delve into the full analysis health report here for a deeper understanding of Shinhan Financial Group.
China Coal Energy (SEHK:1898)
Overview: China Coal Energy Company Limited, along with its subsidiaries, is involved in the production and sale of coal both domestically in China and internationally, with a market cap of approximately HK$192.22 billion.
Operations: The company's revenue is primarily derived from coal production and sales, generating CN¥117.78 billion, followed by its chemical segment at CN¥19.73 billion, financial services contributing CN¥1.96 billion, and coal mining equipment at CN¥8.59 billion.
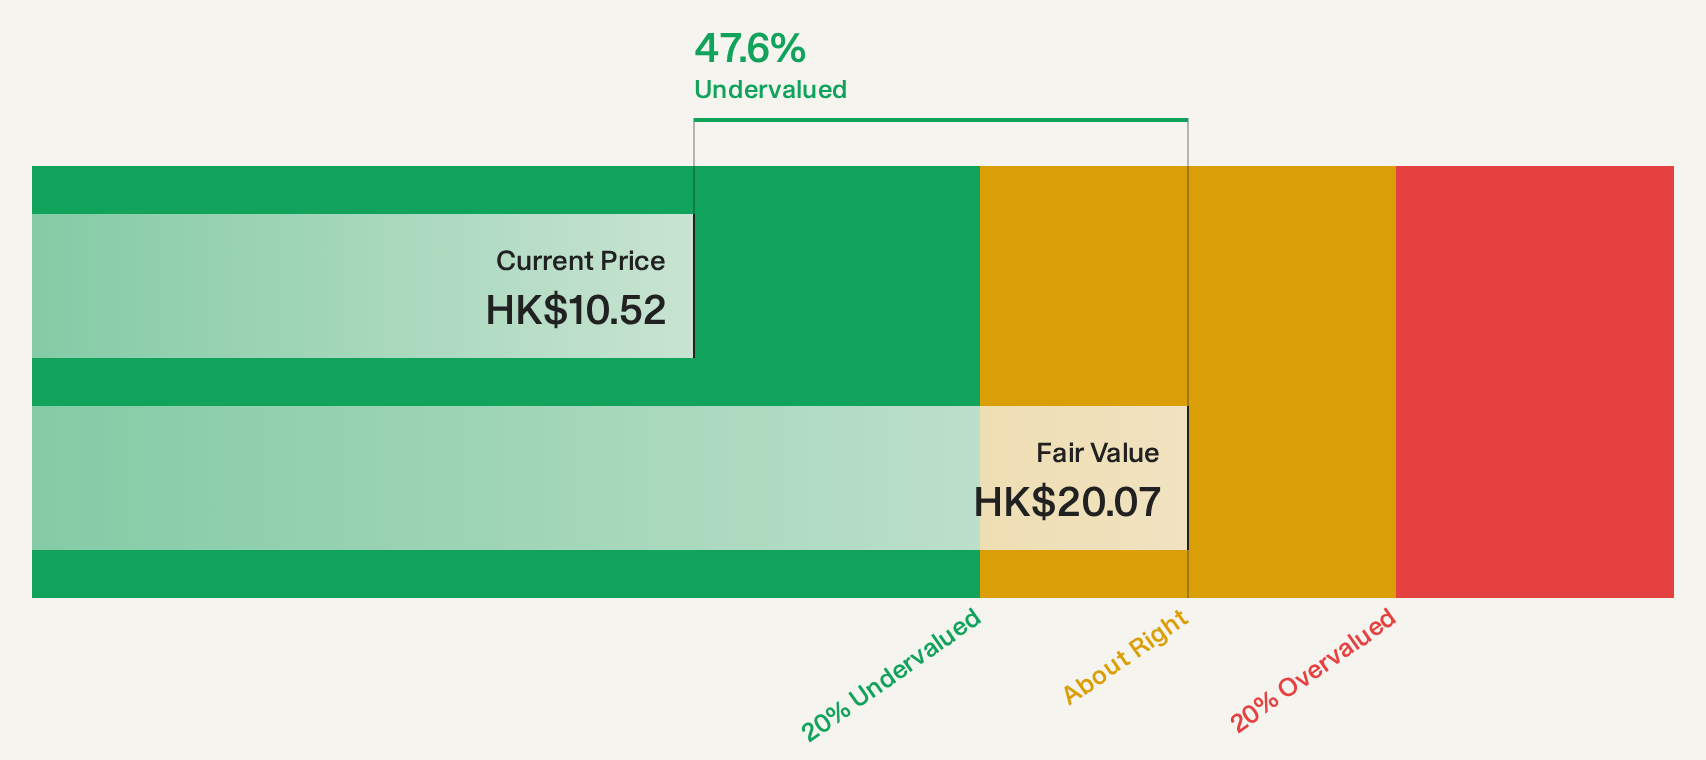
Estimated Discount To Fair Value: 47.8%
China Coal Energy is trading at HK$10.49, significantly below its estimated cash flow value of HK$20.09, indicating it is highly undervalued by more than 20%. Despite a 6.6% earnings increase over the past year, future earnings are expected to decline by an average of 2.3% annually over the next three years. The company declared an interim dividend of RMB 0.184 per share, but its dividend history remains unstable and return on equity is forecasted to be low at 9.2%.
- The growth report we've compiled suggests that China Coal Energy's future prospects could be on the up.
- Click to explore a detailed breakdown of our findings in China Coal Energy's balance sheet health report.
Ningbo Deye Technology Group (SHSE:605117)
Overview: Ningbo Deye Technology Group Co., Ltd. operates in China, focusing on the research, design, development, production, sale and servicing of solar inverter systems, frequency conversion control systems, environmental electrical appliances and heat exchangers with a market cap of CN¥99.33 billion.
Operations: The company's revenue is derived from its activities in solar inverter systems, frequency conversion control systems, environmental electrical appliances, and heat exchangers.
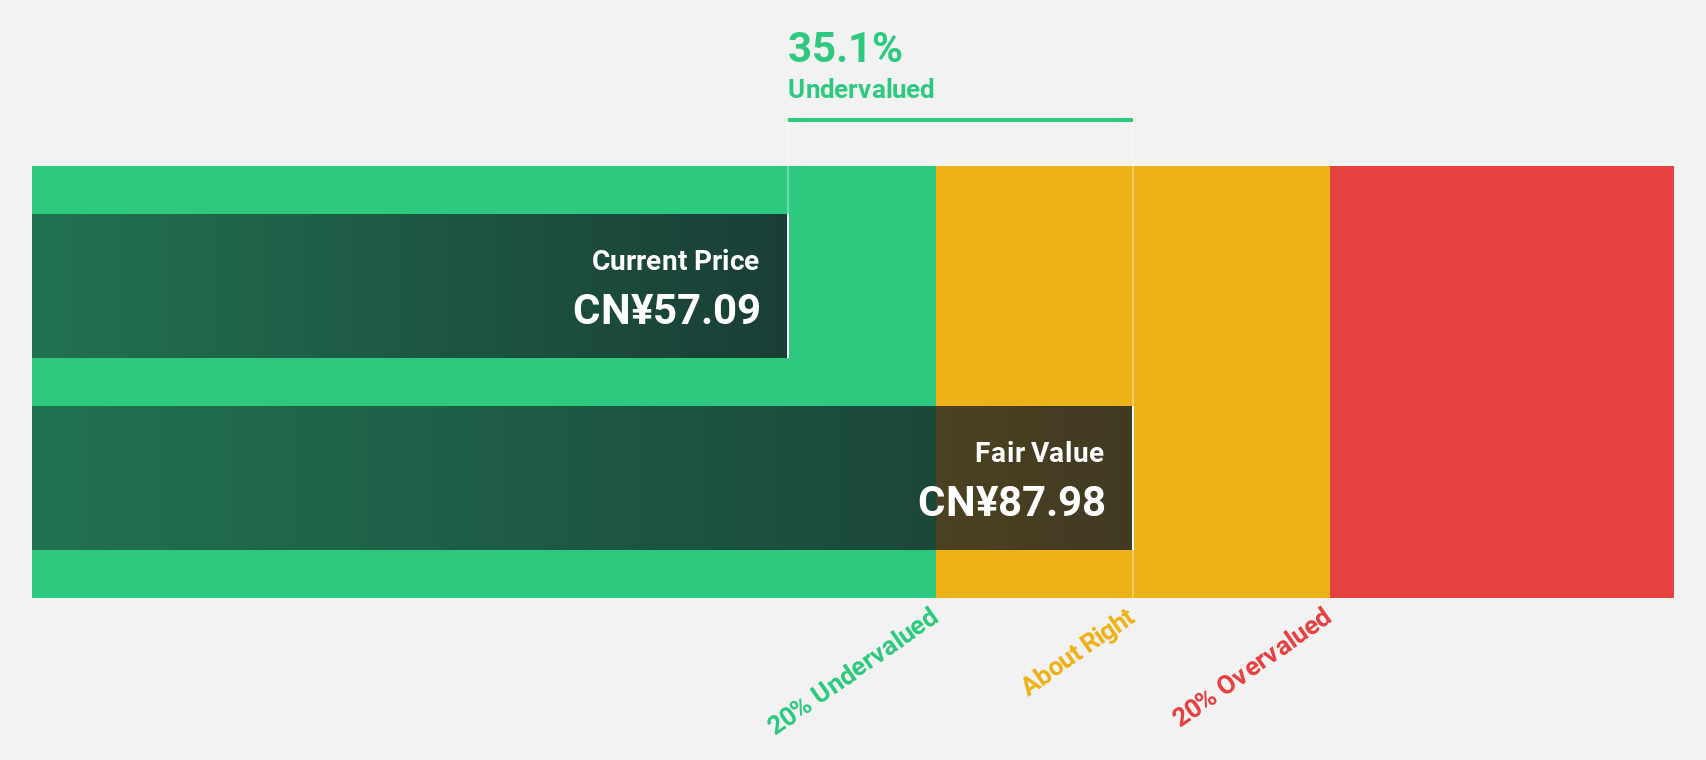
Estimated Discount To Fair Value: 38.4%
Ningbo Deye Technology Group, trading at CN¥78.01, is significantly undervalued compared to its estimated future cash flow value of CN¥126.67, with a 38.4% discount to fair value. The company's earnings grew by 34.5% last year and are forecasted to grow significantly over the next three years despite slower profit growth than the market average. A recent share repurchase program of up to CN¥200 million could enhance shareholder value further through equity incentives or employee stock ownership plans.
- Insights from our recent growth report point to a promising forecast for Ningbo Deye Technology Group's business outlook.
- Dive into the specifics of Ningbo Deye Technology Group here with our thorough financial health report.
Make It Happen
- Click this link to deep-dive into the 78 companies within our Undervalued Asian Stocks Based On Cash Flows screener.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com