


Record Revenue Might Change The Case For Investing In Manchester United Stock (MANU)
- Manchester United reported fourth quarter sales of £157.5 million and a net loss of £28.72 million, and issued fiscal 2027 revenue guidance of £740 million to £760 million.
- Record full year revenue, a shift back to operating profit, and land secured for a planned 100,000 seat stadium signal a wider business reset beyond the latest quarterly loss.
- We will now look at how Manchester United's record full year revenue changes the investment narrative built before this announcement.
Scan how Manchester United's reset story compares with other clubs and consumer businesses targeting a similar rebound by checking our hand picked list of 16 high quality undiscovered gems.
Manchester United Investment Narrative Recap
To own Manchester United, you need to believe that record full year revenue and the return to operating profit can eventually outweigh the current losses in individual quarters. The near term hinge point is whether cost discipline and squad reshaping can turn that £28.72 million quarterly loss into cleaner, more predictable earnings without eroding on pitch competitiveness.
The biggest immediate risk is financial strain meeting football reality. High wages, injury issues and reliance on transfer income already pressure cash generation, and guidance of £740 million to £760 million for 2027 puts a clear bar in front of management execution rather than fundamentally changing that risk reward balance today.
The most relevant piece of context here is that Manchester United still reported record full year revenue and swung back to operating profit despite a poor Premier League start and no UEFA income. That indicates the commercial engine, from sponsorships to media and matchday, remains powerful enough to support a reset even while the team underperforms.
New long term deals with Betway and SumUp, plus land for a 100,000 seat stadium, connect directly to potential future catalysts. Execution around that stadium plan, and the ability to keep signing partners on attractive terms while carrying high wage commitments and less than one year of cash runway, will heavily influence whether the current rebuild turns into durable value.
Analyst consensus for Manchester United points to revenue of £858.3 million and earnings of £95.3 million by 2029, which assumes 7.8% yearly top line growth and an earnings swing of about £113 million from the current £18.1 million loss.
Uncover why Manchester United's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
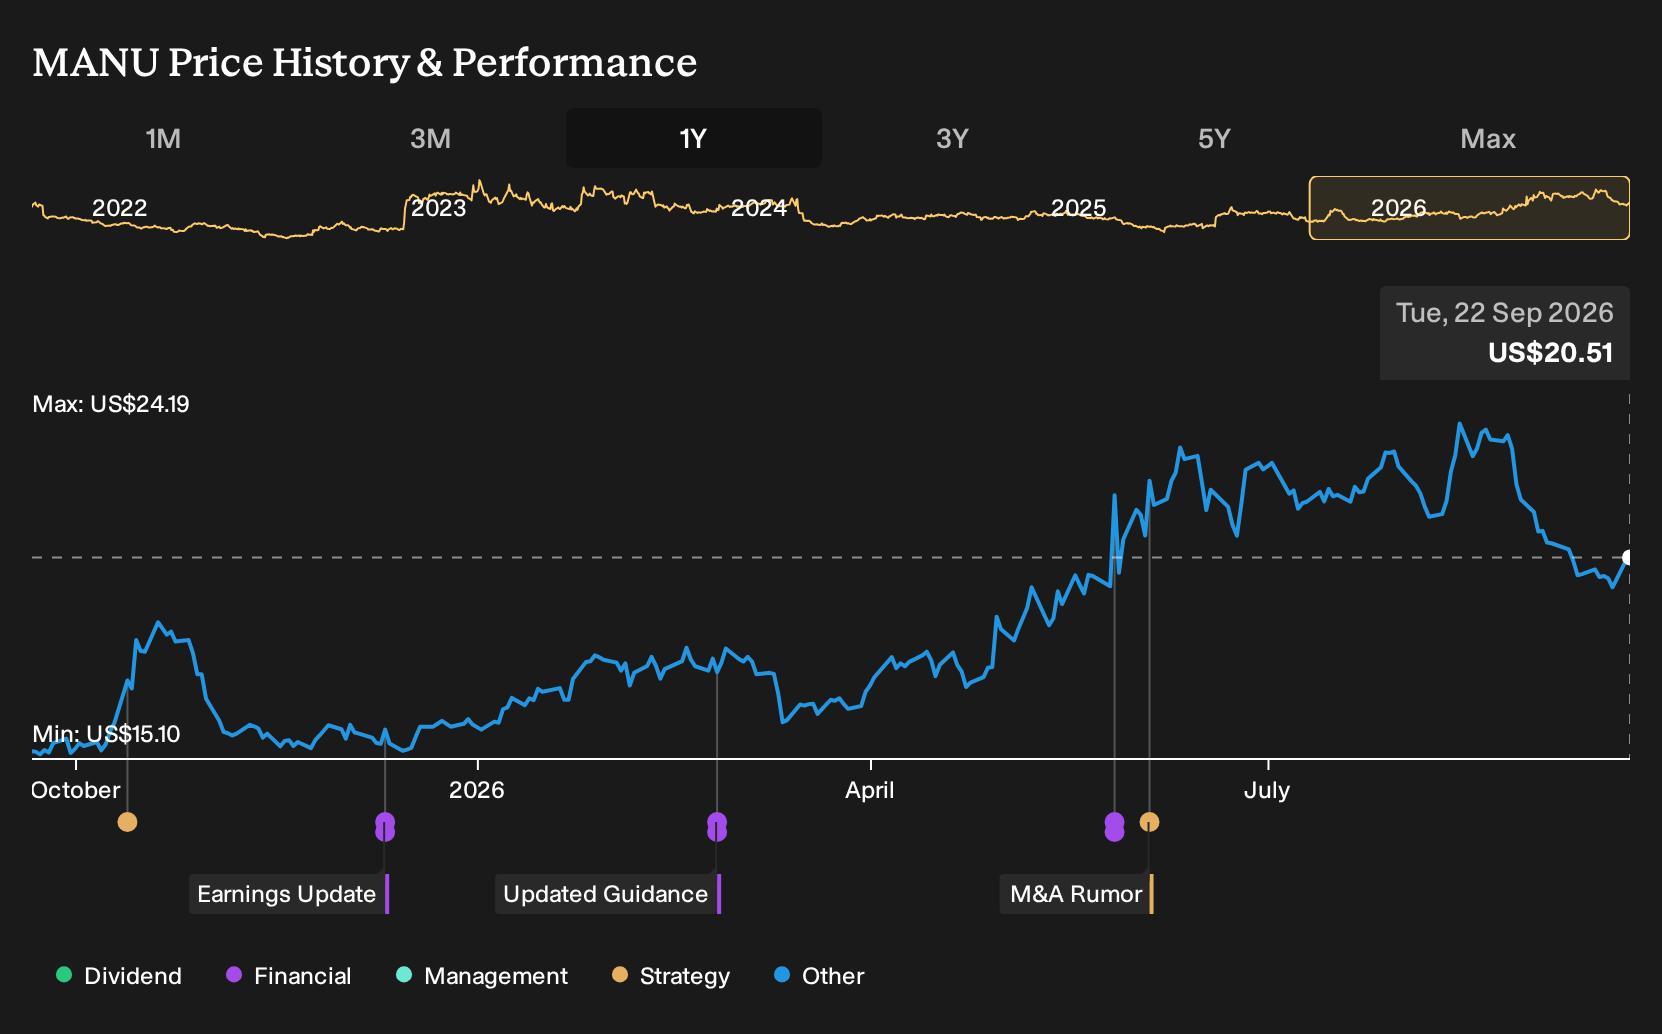
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between £23.65 and £37.45 per share, so you are looking at a wide spread of opinion from private investors rather than a single anchor. When you set that beside Manchester United's 2027 revenue guidance and the current rebuild risks and catalysts, it becomes clear that investor views can diverge sharply. Explore those different takes before deciding how this reset story fits into your own portfolio thinking.
Explore 2 other Manchester United fair value estimates, including one that suggests as much as 83% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Manchester United research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Manchester United. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Manchester United's overall financial health at a glance.
Looking For More Ideas Beyond Manchester United?
Once you have a handle on where Manchester United fits in your portfolio, it can help to line it up against other opportunities that offer different risk and income profiles. The Simply Wall St Screener lets you scan for companies that match the kind of return, balance sheet strength or dividend profile you want, instead of just chasing the next headline.
- If you want potential upside with tighter risk controls, filter for companies highlighted in our 30 resilient stocks with low risk scores and compare their profiles with Manchester United.
- For investors focused on resilient cash flows and balance sheets, start with the list of solid balance sheet and fundamentals (23 results) to see which businesses pair stronger finances with more predictable operations.
- If you are hunting for mispriced opportunities with room for a re-rating, scan the 29 high quality undervalued stocks to find candidates that might deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com