


Sun Life Financial (TSX:SLF) Stock Looks Above Fair Value After 115% Run
Sun Life Financial has delivered a powerful run over the past few years, and the stock now trades at a level that naturally raises a question about what its earnings really support. With that backdrop, investors are asking whether the recent share price puts too much weight, or not enough, on the cash the insurer can generate from its core operations.
- Over the past 5 years, Sun Life Financial has returned 115.4%, which puts real pressure on the current share price to be supported by equally robust earnings power.
- The new Commitment to Canadian Infrastructure Initiative, which targets $5b of investment over 5 years, can influence how quickly Sun Life Financial converts capital into earnings and how investors think about the durability of those profits.
- The analysts covering Sun Life Financial have run their own numbers. See what analysts think Sun Life Financial's shares could be worth.
The issue now is whether Sun Life Financial's current share price is adequately explained by the earnings it produces today and what investors expect those profits to look like over time.
If you are weighing whether Sun Life Financial's recent 43.0% 1 year return is fully backed by its earnings power, it can help to compare that question across 7 high quality undervalued stocks.
Has Sun Life Financial Run Too Far on Earnings?
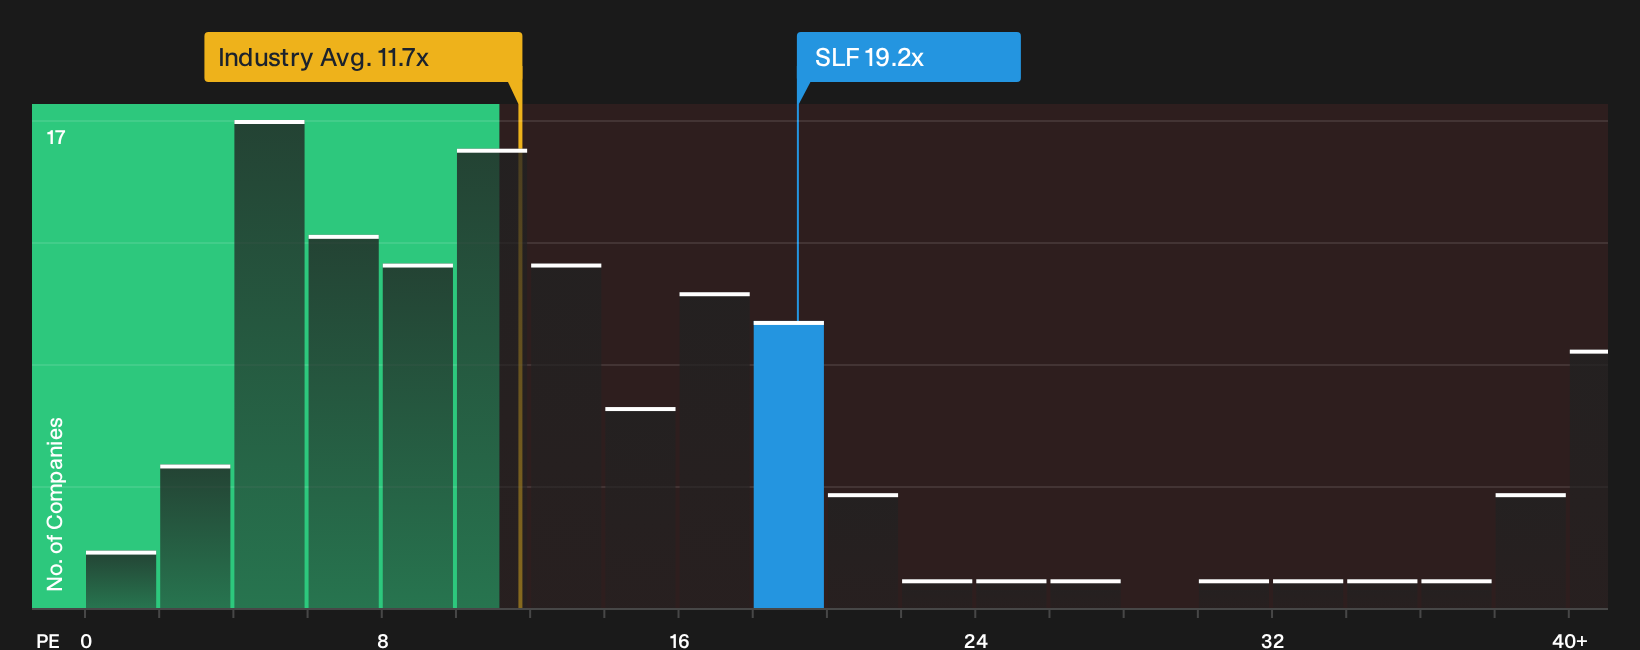
The P/E ratio suits Sun Life Financial because earnings sit at the centre of how investors judge an insurer. On this lens the stock trades on about 19.2x, compared with an Insurance industry average of roughly 11.7x and a peer group around 18.8x. That puts the shares on a richer multiple than the typical insurer, and slightly above similar companies in the same peer set.
Because the Commitment to Canadian Infrastructure Initiative is a large, multi year plan, the market may be giving Sun Life Financial extra credit for the earnings it could point toward over time. Even so, the current P/E stands above the multiple implied by a more tailored fair value framework that weighs its profitability profile, growth outlook, size and risks. On this measure the stock screens as overvalued. For investors, the key question is whether Sun Life Financial can keep delivering the level and quality of earnings that would justify paying this premium. Explore the numbers behind Sun Life Financial's P/E valuation.
The Sun Life Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Sun Life Financial valuation puzzle leaves off by spelling out which combinations of future growth, margins, and earnings would need to hold for the stock to trade meaningfully above or below today's level, and they sit on the Community page. Each one treats Sun Life Financial's implied worth as a specific, testable idea about how the business develops over time rather than a one off snapshot.
Community views on Sun Life Financial are split between one group that sees extra upside and another that thinks the current valuation already reflects most of the story.
Bull case: 9% undervalued
"Rising demand for retirement savings and wealth solutions is feeding into Sun Life Financial's Canadian wealth platform, which has reached $286b in assets under management and administration…"
Discover why this Narrative puts Sun Life Financial at 9% undervalued.
Bear case: roughly fairly valued
"Persistent U.S. Dental and asset management challenges, regulatory risks, and goodwill impairments threaten Sun Life's earnings stability, margin growth, and long-term business resilience…"
Explore why this Narrative puts Sun Life Financial at roughly fairly valued.
One More Factor Sun Life Financial Investors Should Check
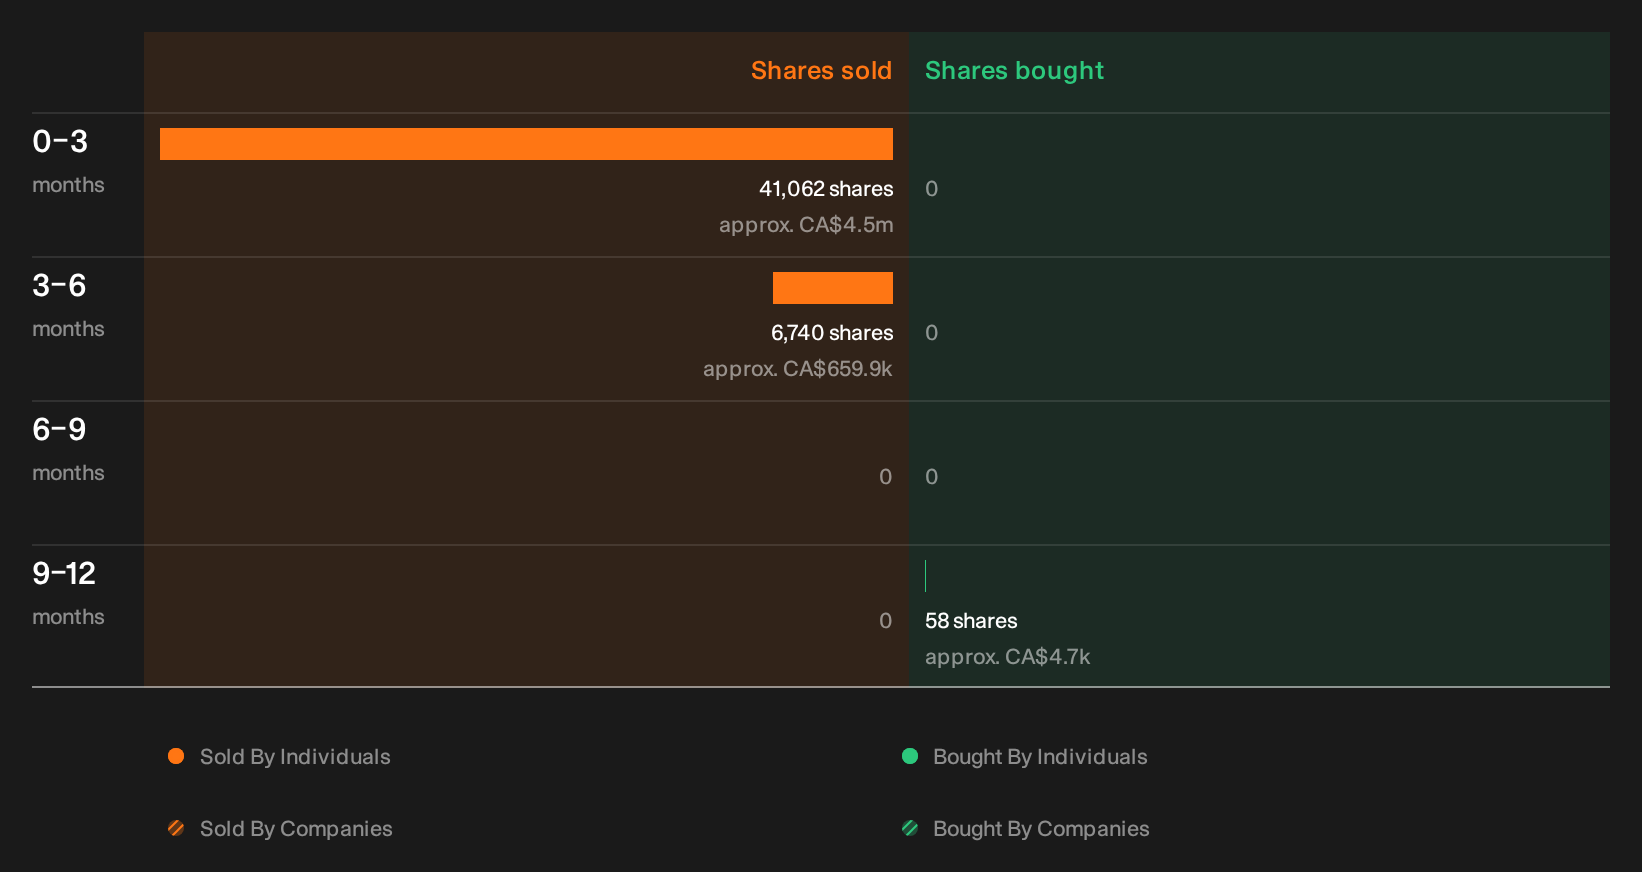
Before you decide how Sun Life Financial's valuation stacks up for you, it is worth looking at what recent insider share sales might signal about confidence inside the business. See the recent insider selling flagged for Sun Life Financial.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com