


AXT (AXTI) After S&P 600 Inclusion With Valuation Questions Still In Focus
AXT (AXTI) rose as much as 16.4% in intraday trading following its official inclusion in the S&P 600 index, a move that can reshape attention from institutional investors and index-linked funds.
AXT has been on a sharp run, with a 7 day share price return of 34.82% and a year to date share price gain of 364.14%, while the 1 year total shareholder return is extremely high. This points to strong momentum that the latest S&P 600 inclusion and recent co packaged optics commentary appear to have reinforced.
Scan how AXT's momentum compares with other semiconductor plays by running through the hand picked 85 AI infrastructure stocks in the same high-speed data and AI infrastructure supply chain.
AXT now combines a rapidly improving business profile with a stock that has already rerated significantly on inclusion news and co-packaged optics interest. The key question is whether the current price still offers fair value.
Most Popular Narrative: 15% Undervalued
Against AXT's last close of $77.79, the most followed narrative framework points to a fair value of $91.60. This leaves a valuation gap that investors are trying to judge against execution risk and AI upside.
Accelerating global demand for high-speed data center connectivity and AI infrastructure is driving increased adoption of indium phosphide substrates, where AXT is a top supplier with 40% share. As export permit headwinds ease, this pent-up demand is expected to produce sharp revenue growth and improved utilization of manufacturing capacity.
See why 40 investors see AXT as 15% undervalued.
Result: Fair Value of $91.60 (UNDERVALUED)
Still, reliance on Chinese customers and ongoing export permit uncertainty could quickly challenge the bullish AXT narrative if orders slow or if shipments face renewed disruption.
Find out about the key risks to this AXT narrative.
Another View: AXT Looks Expensive On Sales
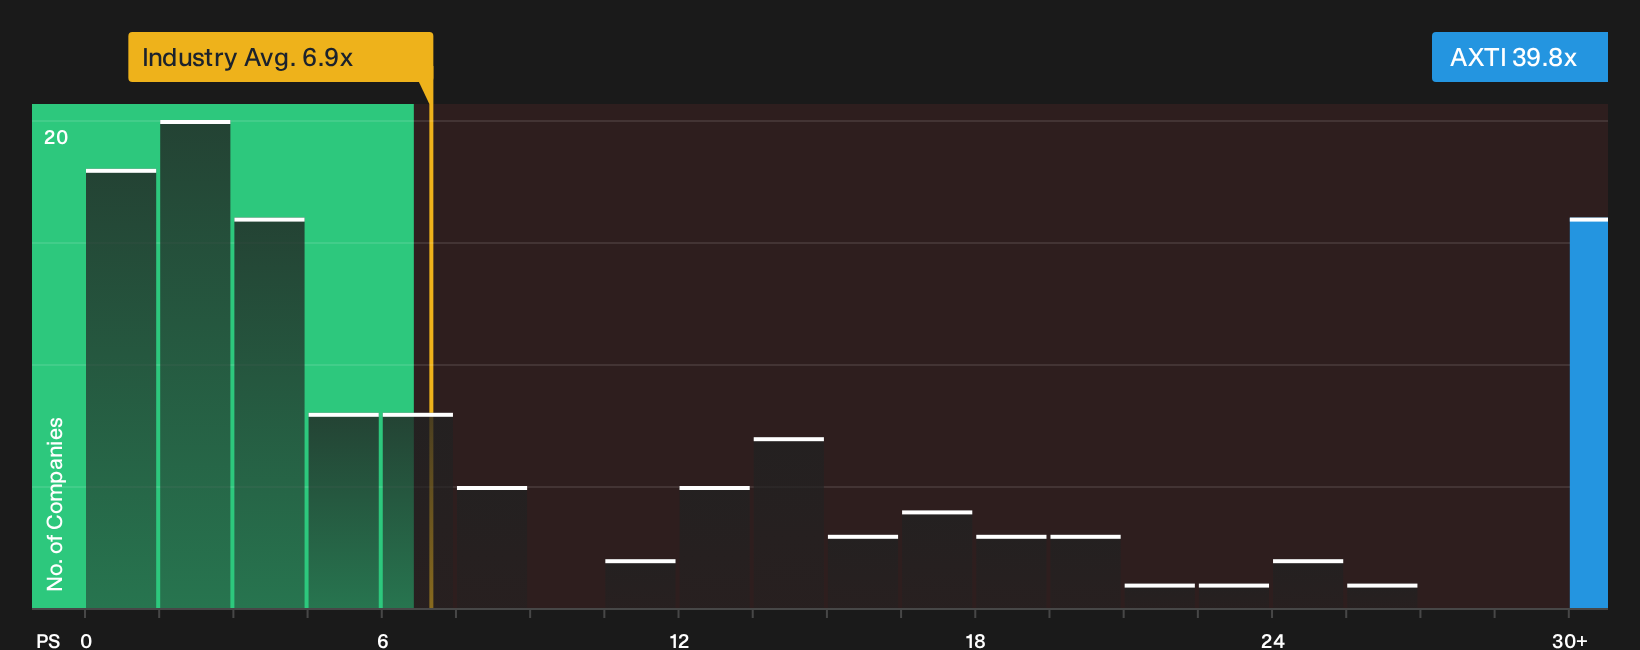
One widely followed narrative tags AXT as around 15% undervalued based on future earnings assumptions. On a simple P/S yardstick, the picture is very different. AXT trades on 39.8x sales, well above the US Semiconductor industry at 6.9x and its own fair ratio of 25.8x, which points to meaningful valuation risk if sentiment cools.
That kind of gap means investors are paying a heavy premium today for future execution, so the open question is how much optimism you are comfortable underwriting at $77.79.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around AXT is divided, with both meaningful concerns and potential upside in view, so review the underlying data promptly and stress test your own thesis using the 2 key rewards and 3 important warning signs.
Looking for more AXT investment ideas?
If you only stop at AXT, you risk missing other opportunities that fit your style, so put a few minutes into scanning the wider market with targeted tools.
- Start with quality and value together by checking the 29 high quality undervalued stocks that blend strong fundamentals with prices that still appear reasonable on multiple measures.
- Prioritise resilience by reviewing the 30 resilient stocks with low risk scores that score well on balance sheet strength and business stability to help reduce downside shocks.
- Hunt for early stage potential by scanning the 16 high quality undiscovered gems that combine solid metrics with limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com