


Bank of America (BAC) Warns Oil Could Surge Above $150 Per Barrel
- Bank of America (NYSE:BAC) strategists warned this week that oil prices could climb above US$150 per barrel if Middle East supply disruptions continue.
- The research team highlighted that extended outages from key regional producers could tighten global crude markets and strain inventories.
- Analysts at the bank flagged that a spike toward US$150 oil would likely feed directly into higher fuel costs and broader inflation pressures.
- This potential surge in oil above US$150 is important, but it should not dominate every decision you make on Bank of America. We have also flagged 5 other big wins for Bank of America.
Rising focus on energy security and infrastructure makes it worth examining companies tied to grid reliability and transmission, starting with 39 power grid technology and infrastructure stocks.
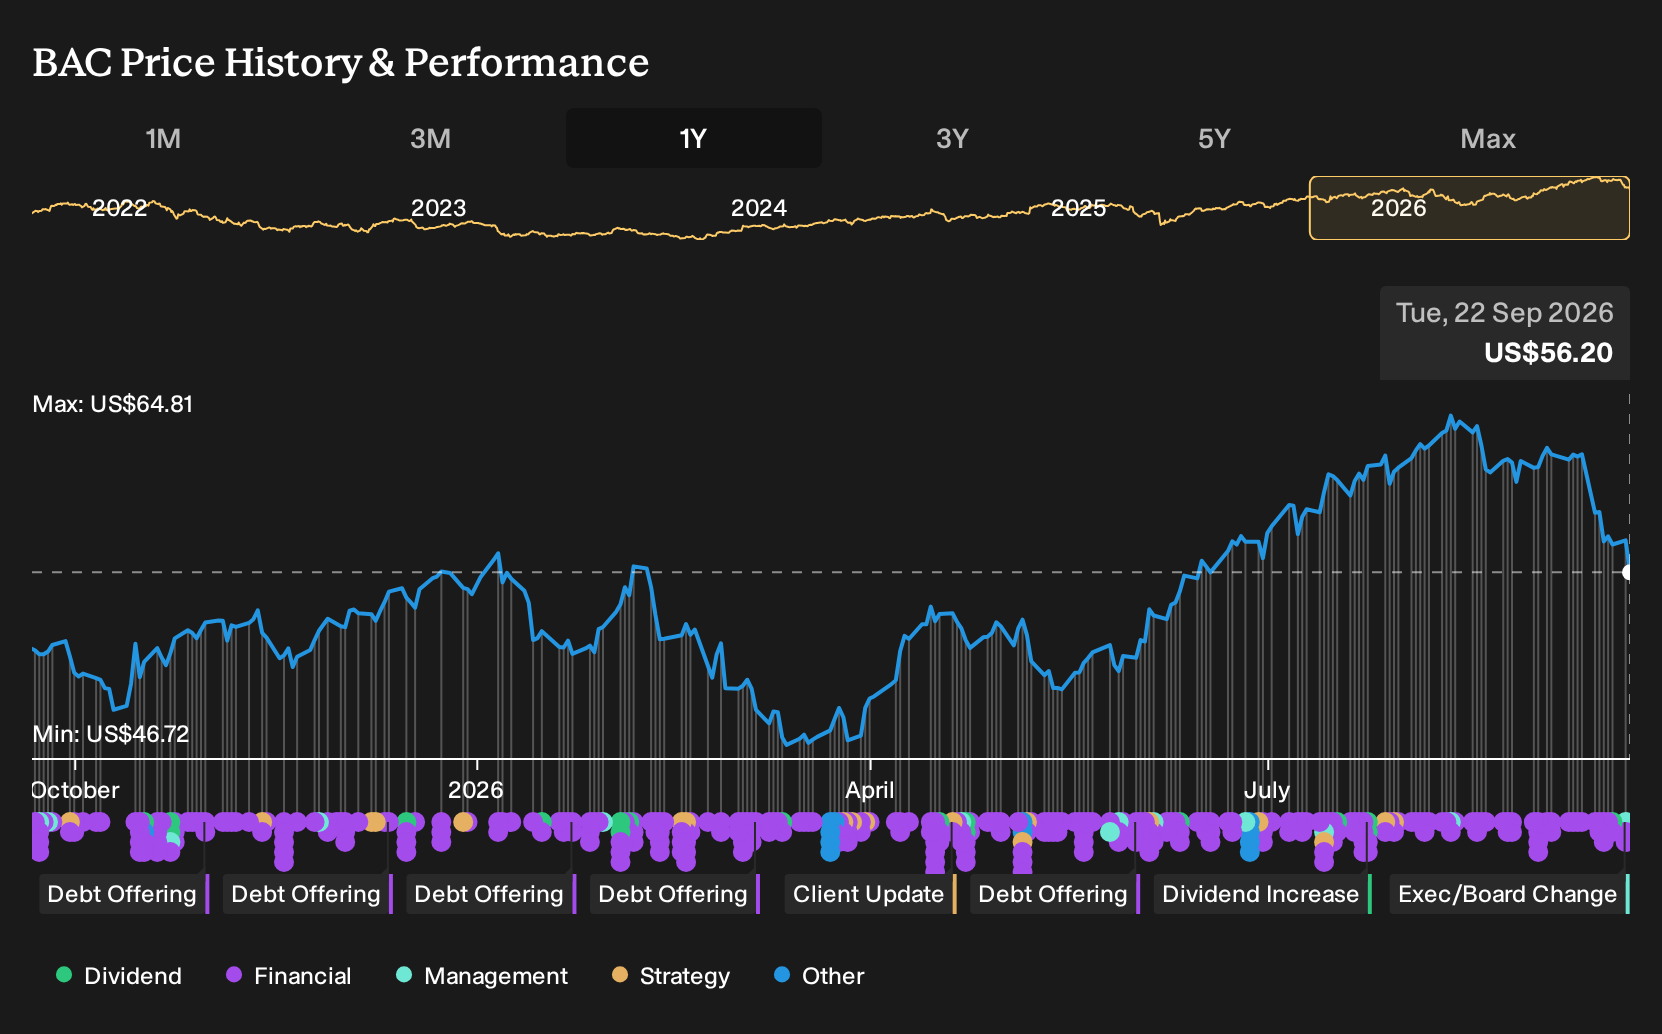
Bank of America, a US bank with a market value of about US$405.3b, runs a large global markets and institutional business that closely tracks commodity trends because these markets influence funding costs, lending conditions, and corporate risk management for its worldwide clients.
See which insiders are buying and selling Bank of America following this latest news.
What a US$150 oil scenario really tests in the Bank of America Narrative
The investment story around Bank of America is that a higher-for-longer rate backdrop and a diversified balance sheet give the bank room to handle economic shocks while leaning on digital scale and lending to drive earnings, rather than relying on smooth markets.
"Strategic actions around asset repricing and interest rate management, including fixed-rate asset re-pricing and cash flow hedge benefits, could improve net interest income, supporting future earnings growth..."
See how the full story points towards a $68.11 fair value for Bank of America.
The oil-call matters less as a commodity prediction and more as a signal of how Bank of America reads risk for its own clients. A team that is publicly stress-testing US$150 crude is also stress-testing credit quality, deposit behaviour and funding costs under that scenario, which directly links to the Narrative focus on asset repricing and interest rate management.
For investors, the question is whether this kind of macro work simply supports the existing higher-for-longer, capital-markets-friendly story or stretches it. If prolonged energy shocks tighten credit and squeeze consumers, the Narrative’s rewards around loan growth, digital engagement and high-quality credit portfolios run squarely into the flagged risks on deposit competition and policy uncertainty.
The update only really matters once you decide whether your Bank of America story is about resilient balance-sheet earnings through volatility or about a cleaner, more benign cycle that makes those oil scenarios less central.
The valuation question on Bank of America that headlines skip
News coverage circles the stories and risks around Bank of America, but it rarely pauses on one simple check: what the stream of cash coming off this business suggests the whole thing might reasonably be worth next to today’s share price. Find out exactly what Bank of America is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com