


CleanSpark (CLSK) Stock Looks Stretched As It Lands Major Data Center Financing
CleanSpark has logged a very large 3 year share price gain, which puts a spotlight on a simple question for anyone looking at the stock today. Is the current market value of CleanSpark really grounded in what the business is generating from its sales?
- Over the past 3 years the stock has returned about 308.1%, which makes it important to check how that share price move lines up against the revenue base that supports it.
- The recent US$2.276b senior secured notes tied to the Sandersville data center and long term lease with a Meta unit may support more predictable cash inflows over time, while also adding meaningfully to the capital structure that those future sales need to service.
- Your read on CleanSpark is one view; the desks covering it have another. See what analysts think CleanSpark's shares could be worth.
The stock's next move may depend on whether CleanSpark's current share price can be justified by its sales when set against the Fair Ratio benchmark.
If you are evaluating CleanSpark in the context of AI and data center infrastructure, it may be useful to compare it with other listed companies in similar infrastructure by scanning 85 AI infrastructure stocks.
Has CleanSpark Run Too Far on Sales?
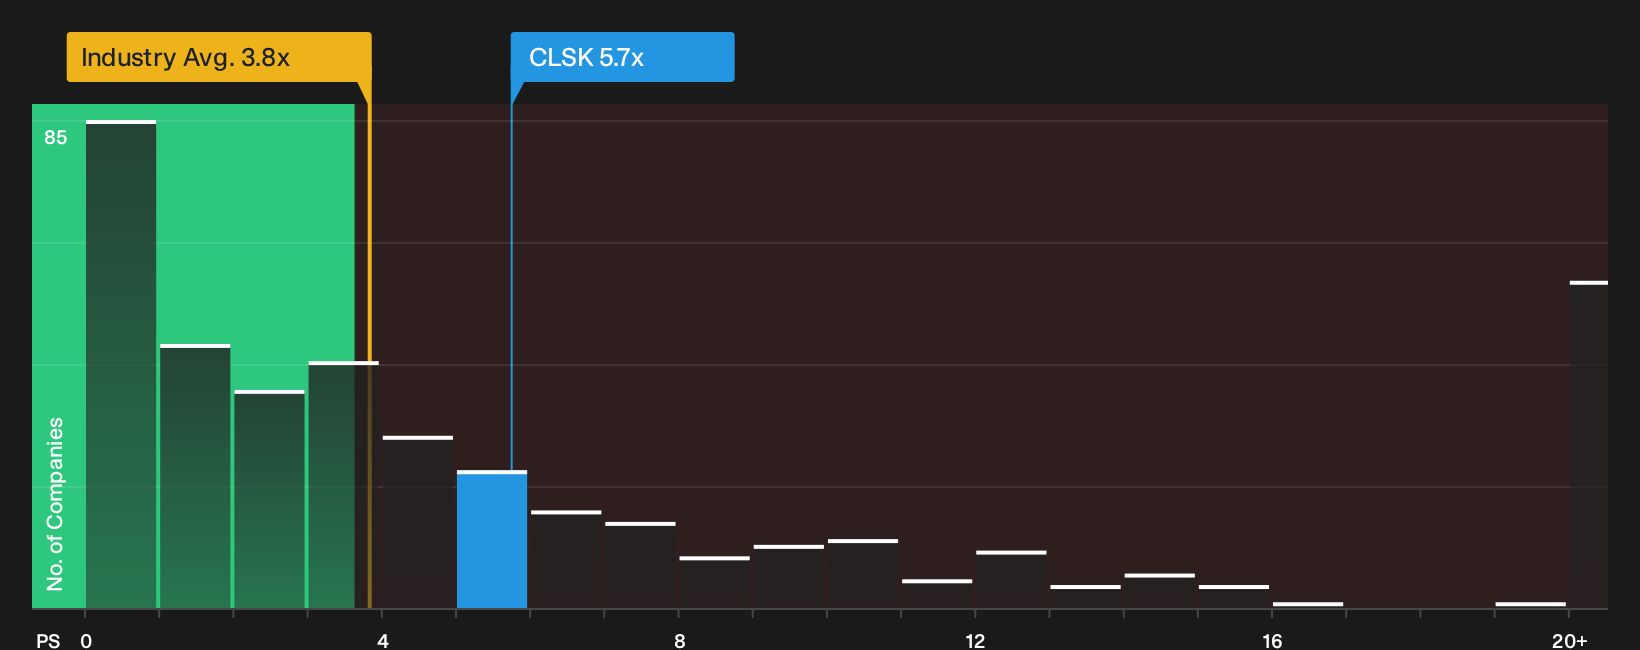
P/S often fits a business like CleanSpark, where investors focus on revenue and contracted demand rather than current profits. On that measure, CleanSpark trades on a P/S of 5.7x, which is below the peer average of about 6.9x but above the broader software industry on roughly 3.8x. The stock therefore prices in a richer revenue tag than the typical software listing, yet not the highest level in its closer peer set.
Recent news around the US$2.276b senior secured notes and the 20 year Sandersville lease with a Meta unit helps explain why the market is prepared to pay a premium to the sector for each dollar of CleanSpark sales. The Fair Ratio framework, which blends factors like growth expectations, margins, size and risk profile into one benchmark, indicates that the current 5.7x P/S sits on the expensive side for those fundamentals. For anyone weighing the share price against revenue alone, that gap is the key question to explore further. Explore the numbers behind CleanSpark's P/S valuation.
The CleanSpark Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the CleanSpark valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to end up worth meaningfully more or noticeably less than today’s price on the Community page. Rather than relying on a single multiple or one model output, each scenario lays out the key drivers behind its fair value so you can track those assumptions against future results as they appear.
One of the top community narratives on CleanSpark: 36% undervalued
"Industry consolidation, with less efficient or capital constrained miners exiting or pivoting to non Bitcoin compute, is increasing CleanSpark's market share..."
Discover why this Narrative puts CleanSpark at 36% undervalued.
CleanSpark's valuation still leaves one big piece of the puzzle unanswered
Everything so far has focused on what CleanSpark looks like today, but broker models sketch out where they think this miner could be a few years from now, which gives you a separate yardstick to compare with the current pricing. Explore where analysts expect CleanSpark to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com