


Franco-Nevada (TSX:FNV) Posted Record First Half Results, Is Most Of The Upside Priced In?
Franco-Nevada (TSX:FNV) grabbed investor attention after reporting record first half 2026 results, with Q2 revenue up 57% and adjusted EBITDA up 45%, even as Cobre Panamá uncertainty and softer cash flow growth temper the headline story.
That strong first half story is feeding directly into the tape, with Franco-Nevada’s share price up 25.8% over the past 90 days and 31.4% year to date. The 3-year total shareholder return of 114.1% and 5-year total shareholder return of 138.5% underline how recent momentum builds on a longer period of solid compounding.
Compare Franco-Nevada’s momentum and risk profile against a hand-picked shortlist of royalty, streaming, and materials peers through the 8 resilient stocks with low risk scores, which prioritises resilient balance sheets and fundamentals.
After a 25.8% move in 90 days and record first half 2026 numbers, is Franco-Nevada still pricing in more runway, or has most of the easy upside already been claimed ahead of the valuation work?
Most Popular Narrative: 2% Undervalued
On the current figures, the prevailing narrative puts Franco-Nevada’s fair value at about CA$384 per share, only slightly above the CA$376.04 last close. This leaves a very narrow gap for investors to interpret.
Recent and ongoing acquisitions of high-quality, long-life assets (e.g., Cote Gold, Arthur/AngloGold's Nevada projects, Yanacocha, Western Limb) have substantially diversified the portfolio, decreasing operational risk and supporting a more stable trajectory for revenues and cash flow. The company's balance sheet, cash flow generation, and conservative financial management may help it respond to market dislocations and pursue distressed or strategic royalty/streaming deals, which could support net margins over time.
See why 47 investors see Franco-Nevada as 2% undervalued.
Result: Fair Value of CA$384.02 (ABOUT RIGHT)
Still, concentrated exposure to assets such as Candelaria and Cobre Panamá, along with legal disputes like Karma, could quickly challenge the Franco-Nevada upside story.
Find out about the key risks to this Franco-Nevada narrative.
Another View: Franco-Nevada Looks Expensive On Earnings
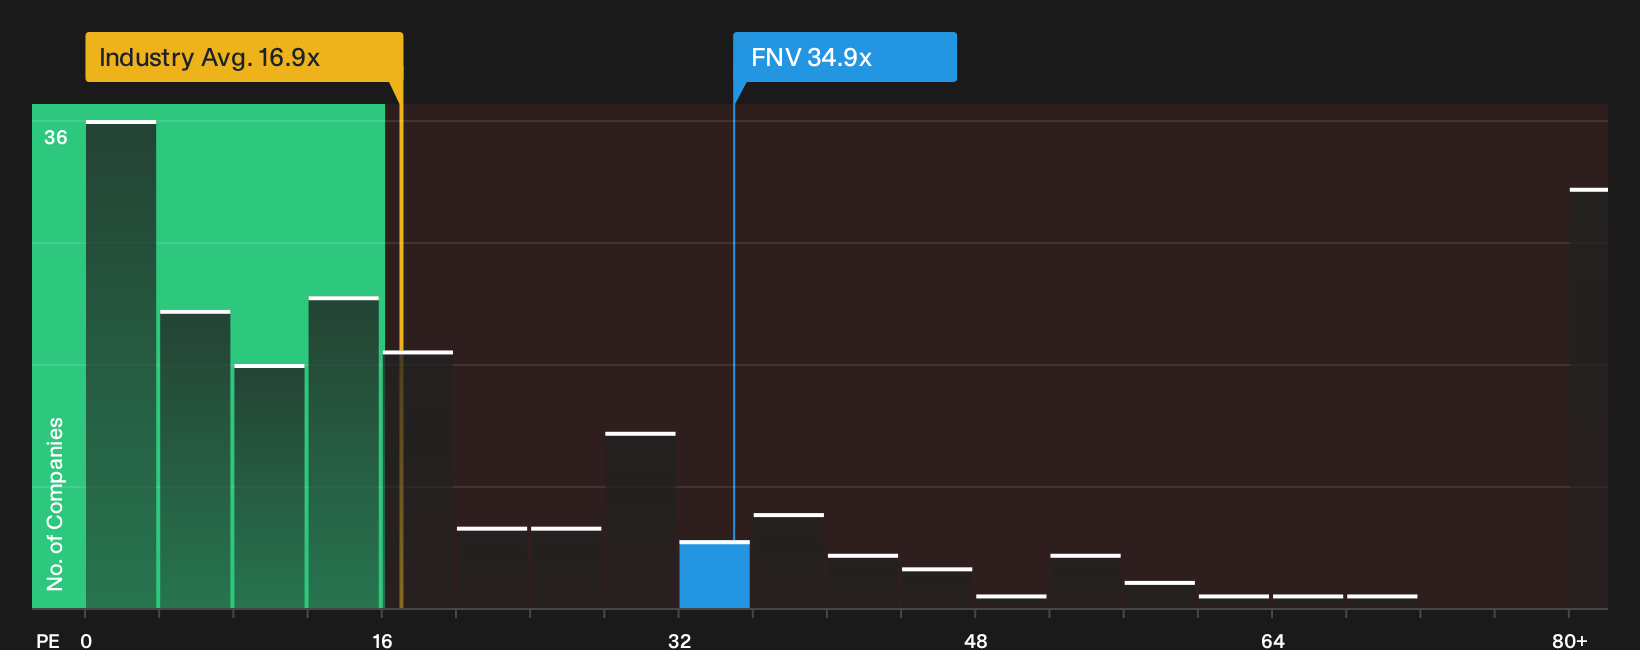
Analysts see Franco-Nevada as roughly fairly priced around CA$384 on their fair value work. On plain earnings maths, the picture is less forgiving. The stock trades on a P/E of 34.9x, almost double the Canadian Metals and Mining average of 16.9x and well above its own fair ratio of 18.5x.
That gap means investors are paying a steep premium today for Franco-Nevada relative to peers and to where the fair ratio suggests the multiple could drift over time. Is that extra price tag really the trade off you want for a royalty business with forecast growth in the low double digits?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split between fair value and a rich P/E, it makes sense to review Franco-Nevada’s numbers yourself and decide quickly where you stand. To see which potential upsides are on the table, review the 2 key rewards.
Looking for more investment ideas beyond Franco-Nevada?
If Franco-Nevada has sharpened your interest, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target value with discipline by scanning a curated 7 high quality undervalued stocks that couples solid fundamentals with prices that may not fully reflect them.
- Strengthen your income stream by reviewing a focused 1 dividend fortresses designed for investors who want yield with business resilience.
- Get ahead of the crowd by tracking a 9 high quality undiscovered gems that highlights quality companies the broader market may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com