


DraftKings (DKNG) Is Back In The Spotlight, What Is Driving The Attention?
DraftKings (DKNG) is back under the microscope after a New York Times investigation claimed the sportsbook uses AI to identify gamblers most likely to lose, raising fresh questions about ethics, regulation, and long term business risk.
Recent trading has been rough for DraftKings, with the share price down 11.5% over the past week and 16.7% over 30 days, contributing to a 38.9% year to date share price decline and a 49.6% slide in 1 year total shareholder return as investors weigh regulatory risk, rising competition from prediction markets, and upcoming appearances like the Wells Fargo consumer conference against the longer term story.
Scan beyond DraftKings and compare how other listed bookmakers and gaming platforms are priced and positioned using a curated set of 16 high quality undiscovered gems in this corner of the market.
DraftKings has built a broad betting and iGaming platform, yet the share price has fallen hard on regulatory worries and fresh controversy. So at about $21.80 a share, is a strong business now a mispriced one?
Most Popular Narrative: 4% Overvalued
DraftKings trades at $21.80 while the most followed narrative, according to CentryResearch, pegs fair value at $20.97. The market is still pricing in a small premium despite the sell off.
The industry's next chapter may look different. As legalization slows, competition intensifies, state tax rates rise, and new prediction market platforms such as Kalshi and Polymarket begin competing for users, DraftKings may find sustaining its growth increasingly difficult. We believe the market may be underestimating the structural headwinds that could emerge over the coming years.
See why 7 investors see DraftKings as 4% overvalued.
Result: Fair Value of $20.97 (OVERVALUED)
Still, DraftKings could surprise skeptics if regulatory outcomes prove less restrictive than feared, or if prediction markets fail to pull away its highest value users.
Find out about the key risks to this DraftKings narrative.
Another View On DraftKings Valuation
The CentryResearch narrative sees DraftKings as 4% overvalued at $21.80 versus a $20.97 fair value. A very different picture comes from our DCF model, which estimates the future cash flow value at $95.71. That gap frames a simple question for investors: Is the market overly cautious or is the model too generous?
Look into how the SWS DCF model arrives at its fair value.
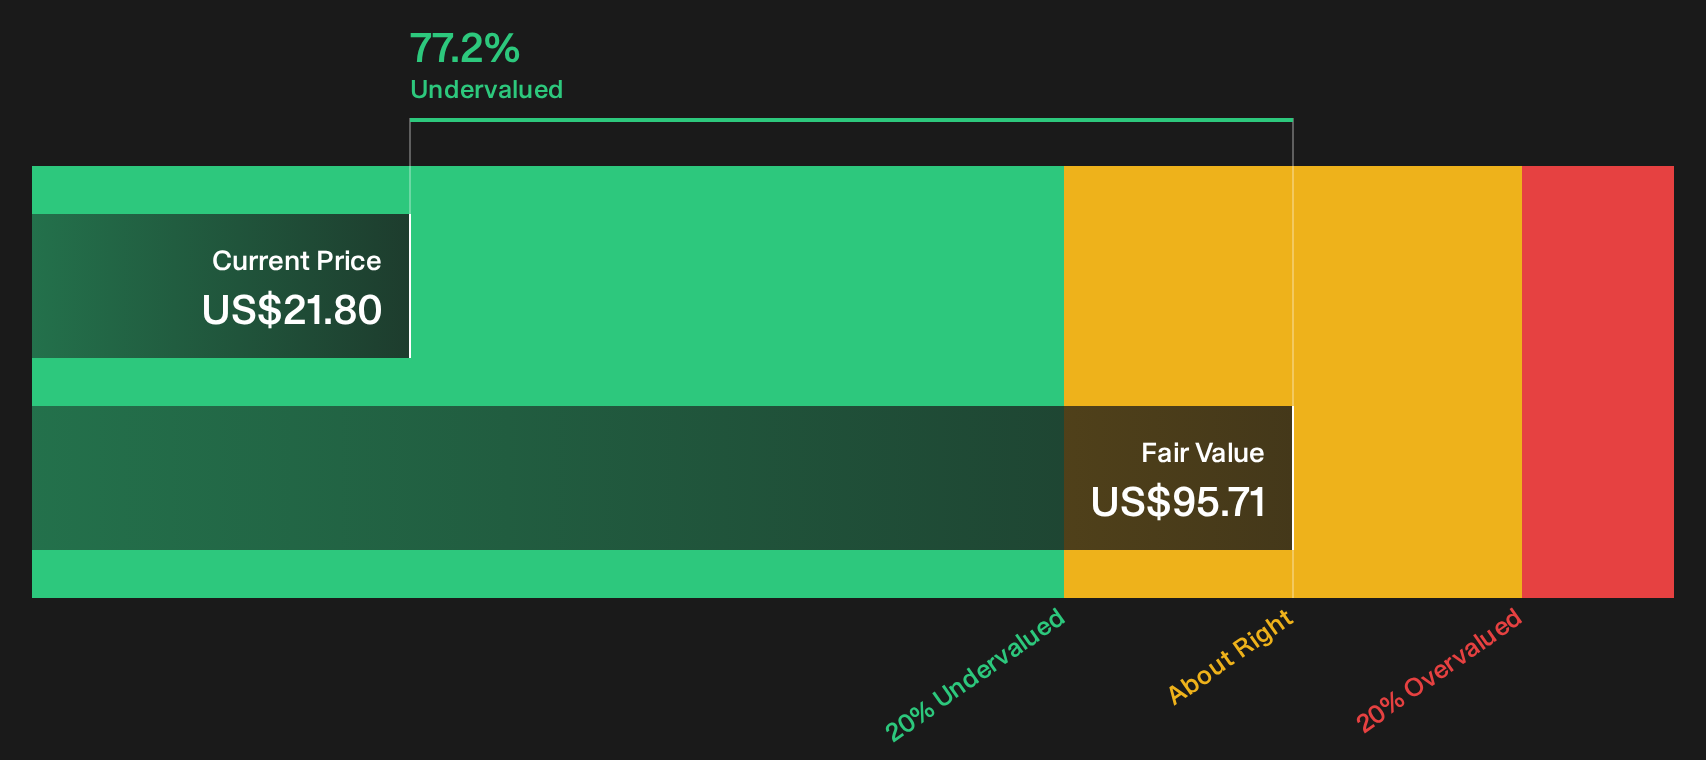
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DraftKings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That mixed sentiment around DraftKings only goes so far without your own homework, so move quickly, review the upside signals, and stress test the 3 key rewards.
Looking for more DraftKings sized ideas?
Do not stop your research with DraftKings. Broaden your watchlist now using focused stock ideas from the Simply Wall St Screener so you are not late to the next move.
- Target resilient income streams by reviewing 7 dividend fortresses that can help anchor your portfolio when growth stories wobble.
- Hunt for asymmetry in your favor by scanning 29 high quality undervalued stocks that combine quality metrics with compressed expectations.
- Protect your downside first by focusing on a list of solid balance sheet and fundamentals (23 results) so weak finances do not quietly erode your returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com