


This Analyst Just Downgraded Netflix Stock, And YouTube May Be to Blame
Netflix (NFLX) shares ended lower on Tuesday after senior HSBC analyst Mohammed Khallouf said investors shouldn’t bet on a swift recovery in the streaming giant.
Khallouf downgraded NFLX in his latest research note to “Hold” and lowered his price target to $76, which does not represent any meaningful upside from current levels.
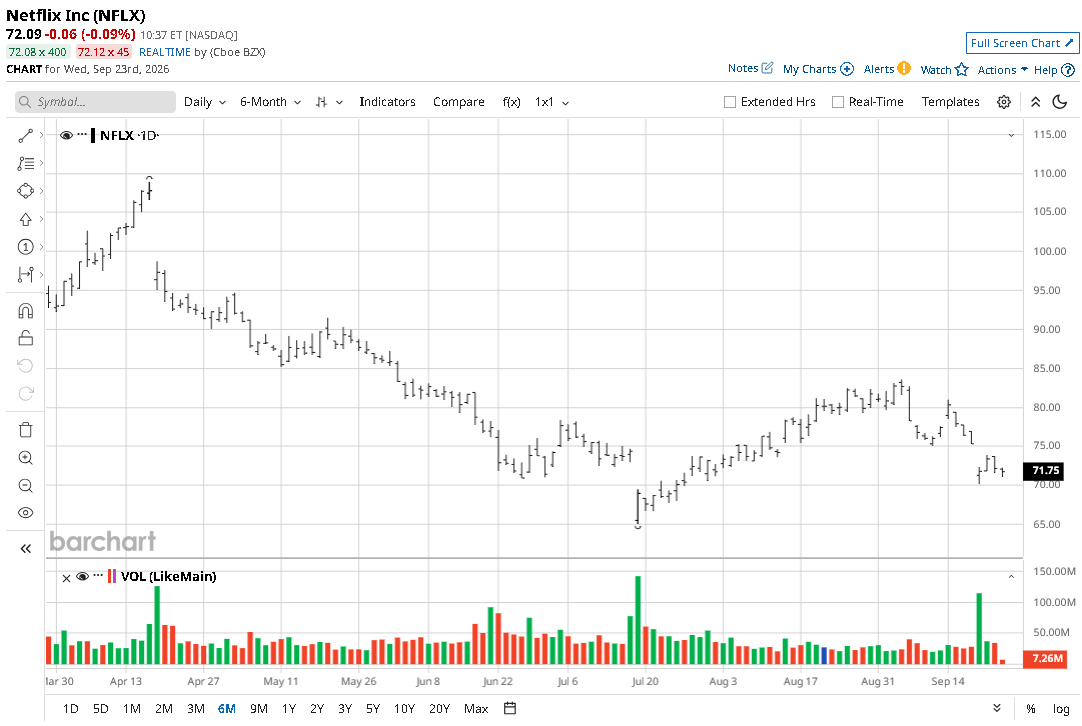
Note that Netflix stock has already been in a sharp downtrend in since mid-April, currently down more than 30% versus its year-to-date high.
What Made HSBC Downgrade Netflix Stock?
HSBC’s core concern centers on YouTube rapidly seizing market share on connected televisions.
In July, the video sharing platform captured a record 14.2% of total U.S. television viewing time, whereas Netflix saw its share shrink to a multi-year low of 7.8%.
YouTube’s massive scale is fueled by an estimated $23 billion in 2026 creator payouts, outstripping NFLX’s planned $20 billion cash content budget.
As YouTube refines its interface to incorporate TV-like episodic layout and incentive programs for creators, viewers are increasingly defecting to free streaming content.
This structural shift threatens to erode Netflix’s long-standing pricing power, ad tier momentum, and core subscriber retention metrics.
What Else Could Hurt NFLX Shares?
Beyond competitive threat from YouTube, analyst Mohammed Khallouf highlighted a meaningful decline in audience enthusiasm for Netflix’s current slate of original programming.
Total viewing hours for English-language titles on the platform’s weekly Top 10 lists tanked about 17% on a year-over-year basis in July and August.
In response to engagement headwinds, HSBC increased its 2027 and 2028 cash content spending estimates by 2% while simultaneously cutting its earnings-per-share (EPS) expectations for those years by 6% to 9%.
Note that insiders have mostly unloaded Netflix shares in the trailing 12 months, which serves as another major red flag for potential investors.
What’s the Consensus Rating on Netflix?
Investors should note, however, that not all Wall Street firms are nearly as bearish on NFLX stock as HSBC.
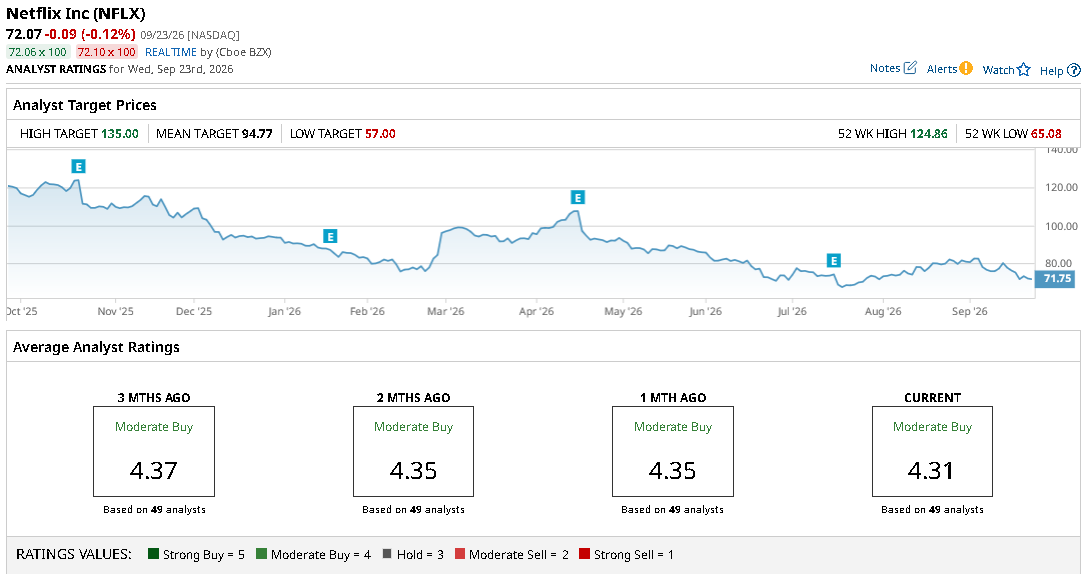
The consensus rating on Netflix remains at “Moderate Buy” – according to Barchart – with the mean price target of nearly $95 indicating potential upside of nearly 30% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.