


Shake Shack (SHAK) Faces Pressure Following Q2 Miss, Is It Still 27% Below Fair Value?
Shake Shack (SHAK) is back in focus after below-expected Q2 earnings and rising costs weighed on results, setting the backdrop for a recent 1.98% daily share price move to $58.09.
The recent move in Shake Shack's share price comes after a tougher stretch, with the stock down 23.38% on a 30 day share price return and its 1 year total shareholder return falling 40.73%. This suggests momentum has faded, even though the 3 year total shareholder return is slightly positive at 1.33%.
Scan how Shake Shack's recent pullback compares with other consumer stocks under pressure from costs and softer sentiment by checking the hand picked 29 high quality undervalued stocks.
Bulls point to Shake Shack's revenue and net income growth, while bears focus on the sharp share price slide and rising costs. Which side does the current valuation lean toward?
Most Popular Narrative: 27% Undervalued
On Simply Wall St's most followed narrative, Shake Shack's fair value sits at $79.70 against a last close of $58.09. This frames the recent share price slide as a valuation gap rather than a clean verdict on the business.
The shift to omnichannel sales and a culture of brand responsibility and sustainability (e.g., community engagement, eco-friendly packaging), combined with stepped-up top-of-funnel marketing, enhances Shake Shack's ability to capture incremental sales, build brand equity with younger, urban-centric consumers, and consolidate share as weaker competitors exit, supporting long-term revenue and margin expansion.
See why 15 investors see Shake Shack as 27% undervalued.
Result: Fair Value of $79.70 (UNDERVALUED)
Still, rising beef and commodity costs, alongside heavier marketing and build-out spending, could squeeze Shake Shack’s margins and weaken confidence in its long term targets.
Find out about the key risks to this Shake Shack narrative.
Another View on Shake Shack's Valuation
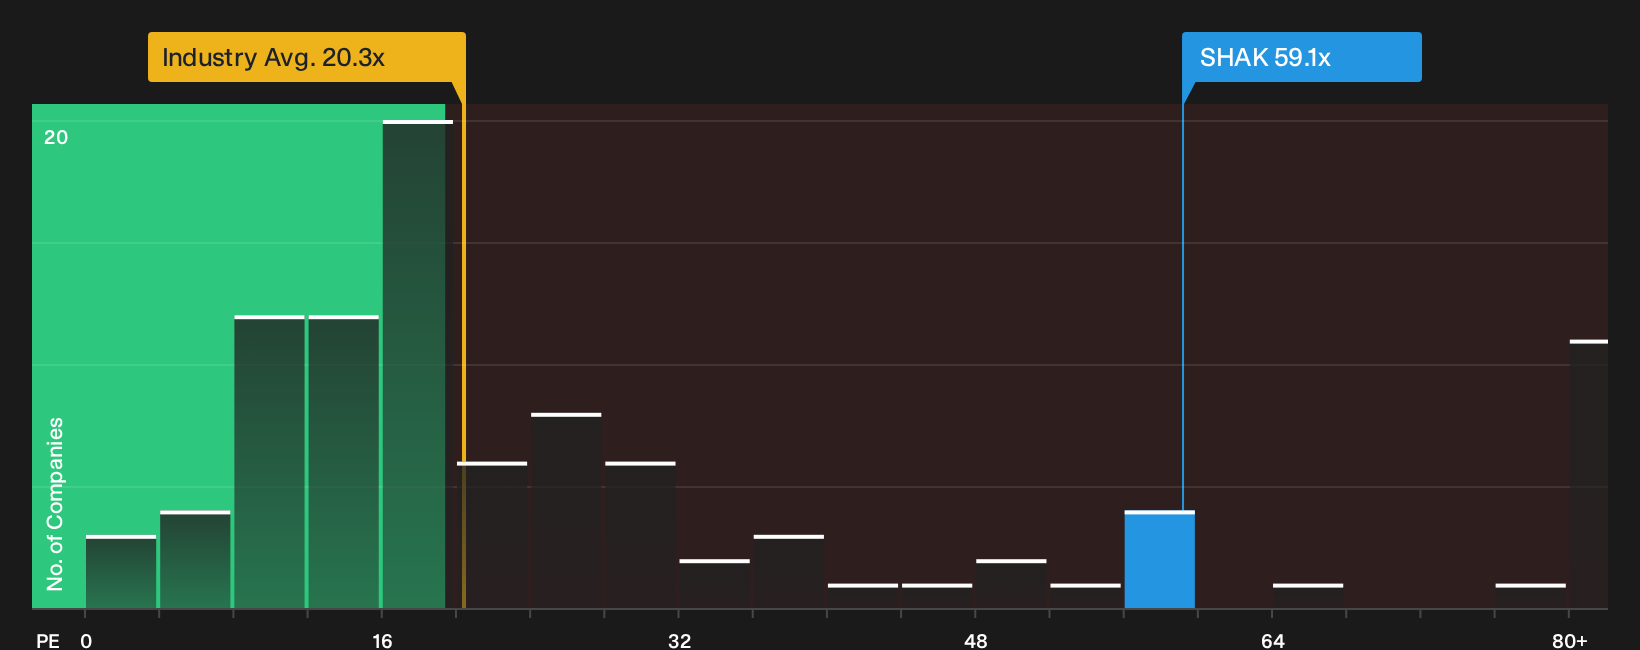
While the Simply Wall St fair value narrative frames Shake Shack as 27.7% undervalued, the P/E lens paints a very different picture. The shares trade on roughly 59.1x earnings, compared with a fair ratio of 23.1x, the US Hospitality average of 20.2x, and a peer group near 18.6x. That kind of premium raises a simple question for investors: Is the current price rewarding future progress early, or just stretching the margin for error?
See what the numbers say about this price in more detail in our valuation breakdown, then weigh how that premium sits with your own risk tolerance and time horizon See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Shake Shack is split, which creates both pressure and opportunity if you move before the next round of information settles in. To weigh that optimism against your own expectations, start with the 3 key rewards.
Looking for more investment ideas beyond Shake Shack?
If Shake Shack has you rethinking your watchlist, it may be worth casting the net wider. Fresh ideas now can help reshape your portfolio well before the next earnings season.
- Look for potential turnaround stories early by scanning the 9 elite penny stocks with strong financials, which combine smaller market caps with stronger underlying financials than you might expect.
- Focus on quality at a discount by reviewing the 29 high quality undervalued stocks, which pair resilient balance sheets with pricing that may lag underlying fundamentals.
- Prioritise resilience by assessing the 30 resilient stocks with low risk scores, which score well on measures of financial health and business stability when conditions are tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com