


Coca Cola Consolidated (COKE) Could Be 24% Undervalued On Strike Disruption
Teamsters have escalated an unfair labor practice strike at Coca-Cola Consolidated (COKE). They have extended picket lines from Anderson, Indiana, into multiple Ohio facilities and disrupted operations for hundreds of union workers.
Coca-Cola Consolidated shares trade at US$190.98, with a 1-day share price return of 0.57% after the strike news, and a 7-day share price return that has slipped 3.85%, even as the year to date share price return of 27.46% and 1-year total shareholder return of 67.55% point to strong longer term momentum.
Scan how other beverage and consumer staples stocks stack up on labor risk and valuation by reviewing the hand picked 30 resilient stocks with low risk scores alongside Coca-Cola Consolidated today.
Bulls point to Coca-Cola Consolidated’s strong 1 year and multi year returns, while bears focus on fresh labor disruption and operational risk. As you weigh the recent pullback, which side does the current valuation appear to support?
Price-to-Earnings of 23.1x: Is it justified?
Coca-Cola Consolidated trades on a P/E of 23.1x, which sits below its peer group average of 56.6x yet above the wider global beverage industry on 16.8x. This means the market is paying a premium to the sector while still assigning a lower tag than many closer comparables.
The P/E ratio compares what investors are paying for each dollar of current earnings. For a beverage bottler with a long trading history and established brands, this metric often reflects expectations about how reliable profits are and how resilient demand could be through different cycles.
For COKE, that 23.1x multiple comes alongside high quality earnings, a 5 year earnings growth rate of 19% per year, but a recent period where earnings declined 6.4% and net profit margins moved from 8.4% to 7.2%. The valuation also sits against a balance sheet flagged for a high level of debt and liabilities that exceed assets, which puts more pressure on those earnings to stay robust.
Compared with the US beverage peer average of 56.6x, Coca-Cola Consolidated trades at a much lower earnings multiple, while still looking expensive relative to the 16.8x global industry figure. That mix signals the market is assigning a richer value than the broader group of beverage stocks but not pricing COKE like some of the highest rated peers, which leaves room for investors to debate whether the current earnings profile and risk level justify that middle ground.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 23.1x (ABOUT RIGHT)
Still, fresh labor disputes and a balance sheet with liabilities above assets introduce real pressure points that could quickly influence how Coca-Cola Consolidated is priced.
Find out about the key risks to this Coca-Cola Consolidated narrative.
Another view on Coca-Cola Consolidated’s value
A different lens comes from the SWS DCF model. On that basis, Coca-Cola Consolidated at $190.98 is trading below an estimated future cash flow value of $253.17, which points to an undervalued setup. If earnings stumble further or labor issues deepen, does that discount still feel comfortable?
Look into how the SWS DCF model arrives at its fair value.
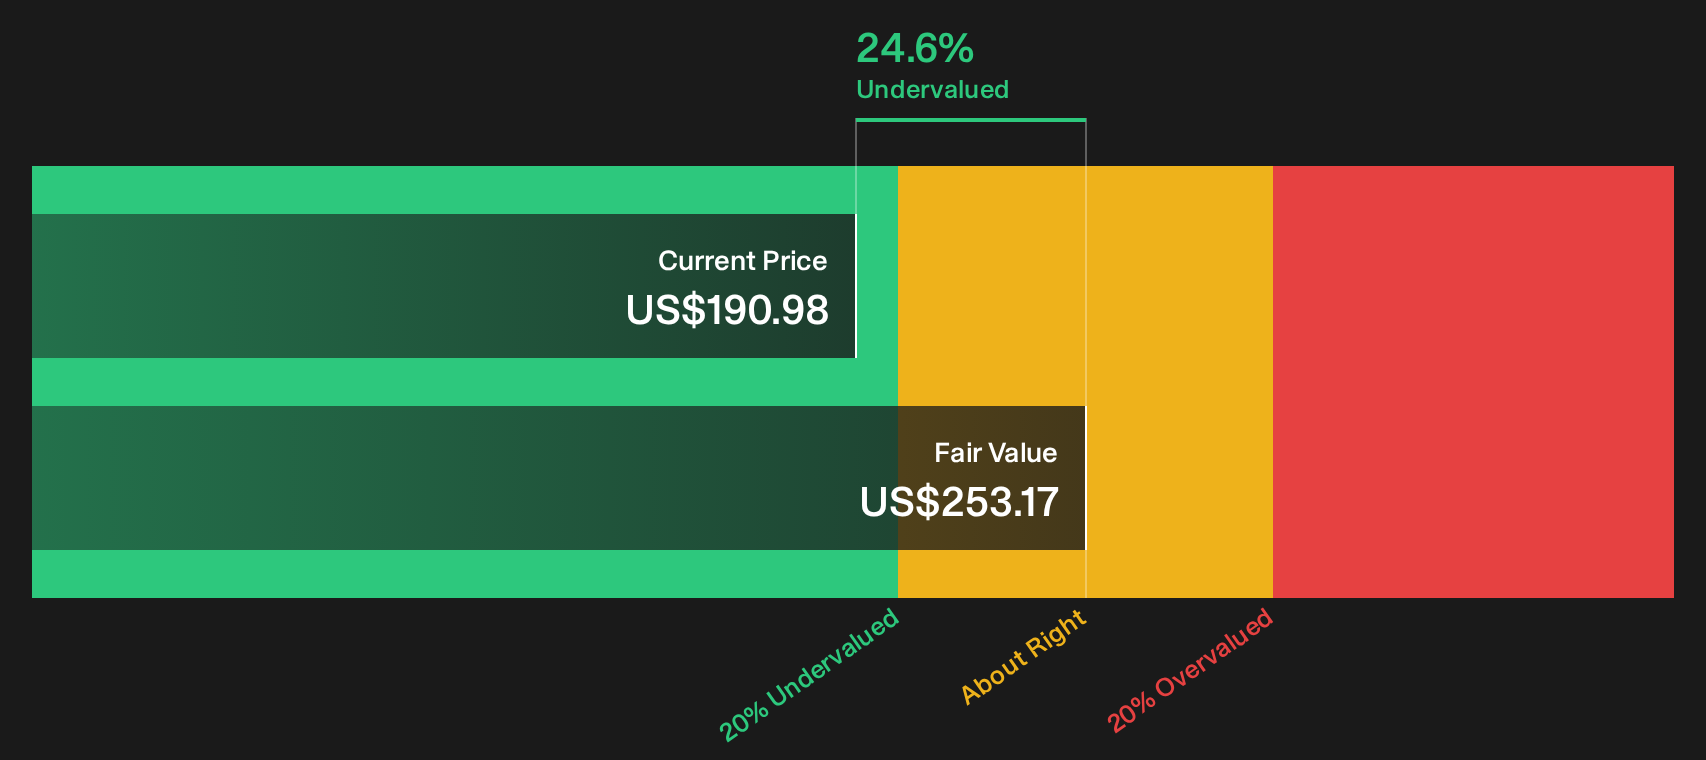
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Coca-Cola Consolidated for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mix of strong past returns and fresh labor risk around Coca-Cola Consolidated? Act quickly, review the data for yourself, and weigh both sides of the story by checking the 1 key reward and 2 important warning signs
Want more ideas beyond Coca-Cola Consolidated?
If Coca-Cola Consolidated has you thinking harder about risk, value, and return potential, broaden your watchlist now before the next move passes you by.
- Target resilience by sifting through a 30 resilient stocks with low risk scores that can help you focus on businesses with more measured risk profiles than Coca-Cola Consolidated.
- Hunt for mispriced potential and scan the 16 high quality undiscovered gems that may not yet be on every investor’s radar.
- Strengthen your income game and review the 7 dividend fortresses that highlights companies offering higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com