


Is Vicor (VICR) Still Undervalued Following Its New VPD Licensing Deal?
Vicor (VICR) has expanded its Vertical Power Delivery licensing program, granting a new OEM the ability to source VPD modules under its patents. Investors may view this move as one that reshapes future revenue opportunities.
Vicor’s licensing update lands after a sharp swing in the share price, with a 7-day share price return of 45.86% and a 1-day gain of 19.85%, following a 90-day period when the share price fell 16.74%.
Over a longer stretch, momentum has built, with a year-to-date share price return of 129.63% and a 1-year total shareholder return of very close to 4x. The 3-year total shareholder return is also close to 4x, and the 5-year total shareholder return sits just above 2x.
Scan beyond Vicor and see how other AI infrastructure suppliers are priced by reviewing the hand picked 86 AI infrastructure stocks now shaping this segment.
Bulls see Vicor’s licensing push and AI exposure as validation for a richer multiple, while bears see a story that has run too far on hype. Which case does the current valuation lean toward?
Most Popular Narrative: 31% Undervalued
On the prevailing narrative, Vicor is viewed as undervalued relative to a fair value of $386.25 when set against the last close at $268.34. That gap rests on bullish assumptions about how long term product demand and licensing income could shape future earnings.
The accelerated adoption of high-power, high-density AI computing in data centers is driving demand for advanced power delivery solutions. Vicor's Gen 5 vertical power delivery products and 800V-to-48V converters target this need, with customer engagements and sampling set to expand in Q3 and Q4. These next-gen products enable Vicor to address a market expected to exceed $5 billion by 2027, supporting long-term revenue growth and eventual margin expansion as manufacturing scales.
See why 25 investors see Vicor as 31% undervalued.
Result: Fair Value of $386.25 (UNDERVALUED)
Still, Vicor’s reliance on volatile licensing outcomes and the drag from underused manufacturing capacity could quickly challenge the 31% undervalued narrative if conditions turn.
Find out about the key risks to this Vicor narrative.
Another View On Vicor’s Valuation
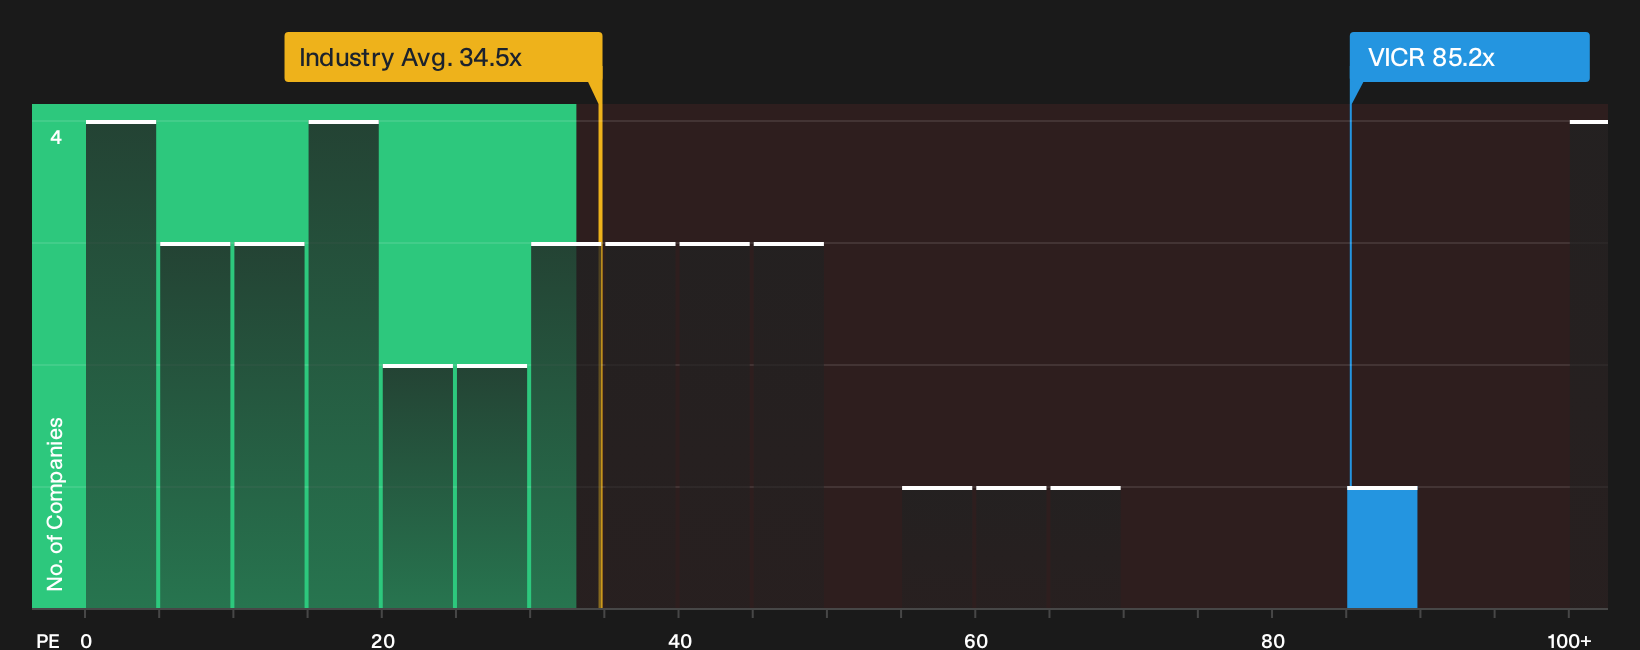
The analyst narrative cites a fair value of $386.25, yet Vicor currently trades on a P/E of 85.2x. That is well above the US Electrical industry at 34.5x, the peer average at 29.1x, and the fair ratio estimate of 68.4x. Is the market paying too much for the AI story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Vicor is split, and the only way to cut through the noise is to move quickly, stress test the assumptions, and weigh both the upside and downside using the 3 key rewards and 3 important warning signs.
Looking for more Vicor-sized investment ideas?
Vicor may already be on your radar, but your next strong idea probably is not. Use the Simply Wall St Screener to spot it before everyone else does.
- Target value first and filter for companies with strong fundamentals using the 29 high quality undervalued stocks that can help you focus on quality at a sensible price.
- Protect your downside and sort for businesses with solid finances through the list of solid balance sheet and fundamentals (23 results) so weak balance sheets do not catch you off guard.
- Hunt for overlooked potential and scan the 16 high quality undiscovered gems before these quieter opportunities attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com