


Matson (MATX) Raised Payouts After Strong Q2, Is The Upside Already Priced In?
Matson (MATX) has returned to investor focus after its presentation at Morgan Stanley's Laguna Conference on September 15, following Q2 results that featured 40.6% operating income growth and higher shareholder payouts.
Recent trading has cooled after a strong run, with the share price down about 3% over the last day and roughly 5% over the past week. Yet Matson still carries an 83% year to date share price return and a 117% one year total shareholder return that reflect how the market is reassessing its growth potential and risk profile.
Compare Matson's momentum and capital return story with other companies that screen well on cash generation and balance sheet strength by scanning our curated 29 high quality undervalued stocks.
Matson now trades near record territory after a sharp run supported by strong Q2 and richer cash returns. The real puzzle for investors is whether that move already captures the value on offer or still leaves meaningful upside.
Most Popular Narrative: 13% Undervalued
Against the last close at $226.78, the most followed narrative pegs Matson’s fair value near $261.67. This frames recent share gains as still leaving a valuation gap to the upside according to that framework.
The ongoing shift in manufacturing and sourcing from China to Southeast Asia and the Pacific, evidenced by Matson's rapid growth in Vietnam-originated volumes and new expedited Vietnam services, positions the company to capture increasing transpacific shipping demand as global supply chains diversify, supporting future revenue growth.
Population growth, economic development, and resilient construction activity, particularly in Hawaii and Alaska, are contributing to steady, long-term demand for essential goods and supply chain services in Matson's protected trade lanes. This underlines a stable and expanding revenue base.
See why 10 investors see Matson as 13% undervalued.
The prevailing narrative backs that $261.67 fair value with analyst assumptions that revenue can compound around 5.1% a year, profit margins hold near 12.4%, and earnings reach about $496.8 million by 2029, all discounted using a 7.45% rate.
Those inputs also imply a future P/E of roughly 17x on 2029 earnings, compared with about 14.4x today. The thesis therefore depends on both earnings growth and some multiple expansion relative to Matson’s current valuation and the wider US Shipping peer group.
Result: Fair Value of $261.67 (UNDERVALUED)
Still, this narrative could crack if concentrated trade routes such as Hawaii or Alaska weaken, or if required vessel spending weighs heavily on future cash generation.
Find out about the key risks to this Matson narrative.
Another View On Matson’s Valuation
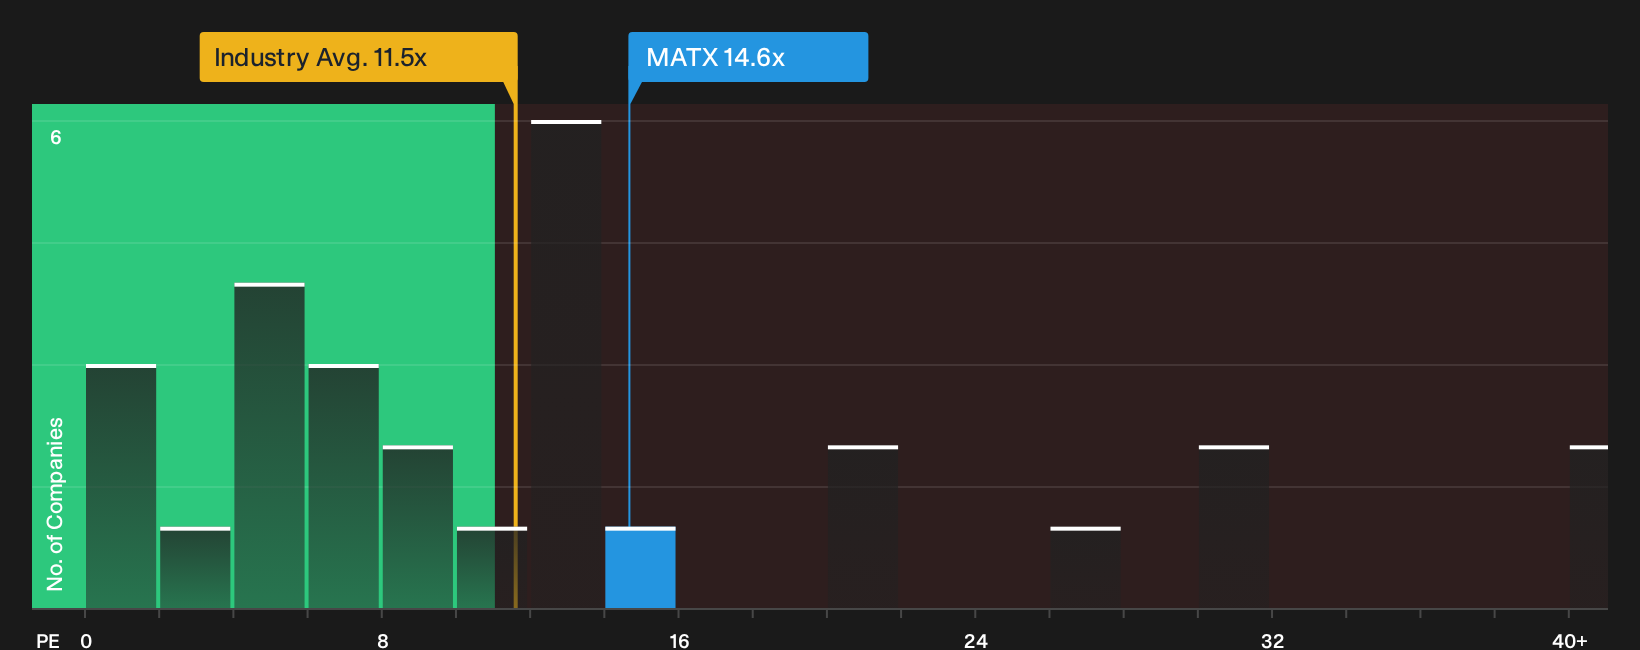
The story looks very different when you step away from the analyst fair value and focus on plain P/E math. Matson trades on about 14.6x earnings, which is slightly above its own fair ratio of 14.3x and well above the US Shipping sector at 11.7x. That gap suggests investors are already paying a premium, so the question becomes whether the quality of the franchise and cash generation justify that extra stretch.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling pulled between the bullish story and the price you see on screen today? Move quickly from headline impressions to your own judgment with the full breakdown of both risks and positives in the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Matson?
Do not stop your research with Matson. Fresh watchlist ideas matter, and diversified opportunities can sharpen your judgment and keep you a step ahead of the crowd.
- Spot potential high upside candidates early by scanning the 9 elite penny stocks with strong financials that already clear strict financial strength filters.
- Seek a balance of quality and value by reviewing the 29 high quality undervalued stocks that pair solid cash flows with disciplined balance sheets.
- Prioritise resilience first by checking the 30 resilient stocks with low risk scores that show lower risk scores yet still offer meaningful equity exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com