


3 Indian Export Stocks That Could Benefit From Lower Oil And A Steadier Rupee
Global markets are flashing mixed signals as US Iran talks ease regional risk, crude prices soften and Asian indices trade firm, yet volatility still hangs over the Nifty 50. Export heavy Indian large caps sit right in this crossfire, where a steadier rupee and lower oil can quietly reshape earnings quality. This article walks through 3 stocks from our export focused screener that appear positively exposed to this backdrop.
The three stocks below are just a sample, as the full screen surfaced 23 more large Indian exporters with equally interesting international revenue stories that are not covered here. To identify and analyze those additional opportunities directly, head straight into the Indian Export-Focused Large Caps Benefiting from Stable FX and Lower Macro Risk screener.
Timken India (BSE:522113)
Timken India plugs directly into the export focused large caps theme, supplying bearings and power transmission gear across rail, industrial and energy markets worldwide, which puts its manufacturing footprint and cross border supply chain in clear focus for this screener.
Timken India generates about ₹36 billion in revenue from bearings and allied goods and services, backed by a roughly ₹239.1 billion market cap that reflects its role as a sizeable industrial exporter within this theme.
Ramp-up of the new Bharuch plant, with target utilization of 45 to 50% by year-end and a strong pipeline of customer qualifications, positions Timken India for substantial incremental revenue and operating leverage benefits as domestic and export volumes scale.
What really matters next is how one quiet shift in its cost and mix profile feeds through to margins as global demand moves.
That margin story is only half the picture, so read the full narrative for Timken India to see how Timken India’s export mix and capex could be quietly accelerating earnings quality.

Gland Pharma (NSEI:GLAND)
Gland Pharma is a Hyderabad based injectable specialist that fits cleanly into this export focused large caps theme, with its sterile products supplying regulated markets where reliable Indian manufacturing and a steady rupee really matter for long run contract visibility.
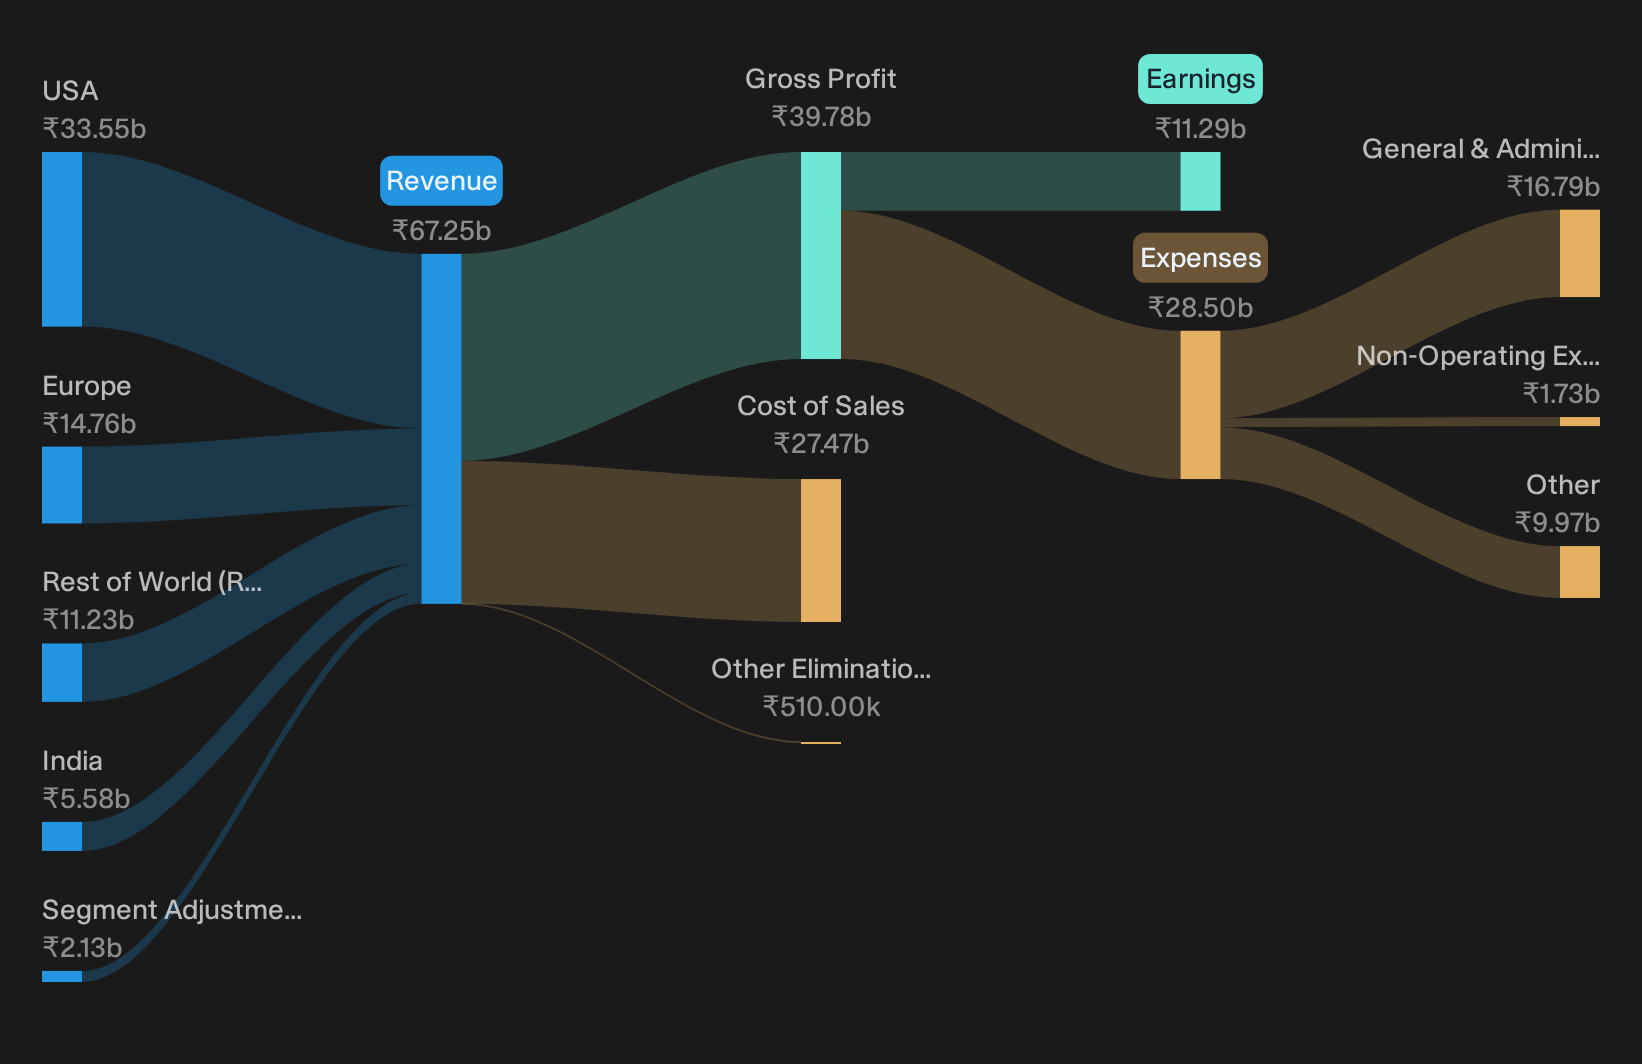
Gland Pharma generates all its ₹67.3 billion in revenue from pharmaceuticals, powered by a ₹481.1 billion market cap that reflects its role as a sizeable global injectable supplier.
The rapid global expansion of Gland Pharma's pen and cartridge capacity (from 40 million to 140 million units by Q1 FY'27) is positioned to serve demand for GLP-1 injectable therapies, such as liraglutide and semaglutide, which are used in chronic disease management and advanced metabolic treatments.
What happens when one concentrated source of demand meets that much fresh injectable capacity will go a long way to shaping future profitability.
That profitability question is exactly what the full narrative for Gland Pharma unpacks, showing where Gland Pharma’s capacity build could accelerate returns and where contract risk might quietly be building.
Ratnamani Metals & Tubes (BSE:520111)
Ratnamani Metals & Tubes brings the screener theme to life in a very physical way, with export focused pipes and tubes feeding long dated energy and infrastructure projects, where a calmer rupee and softer crude feed straight into cost competitiveness.
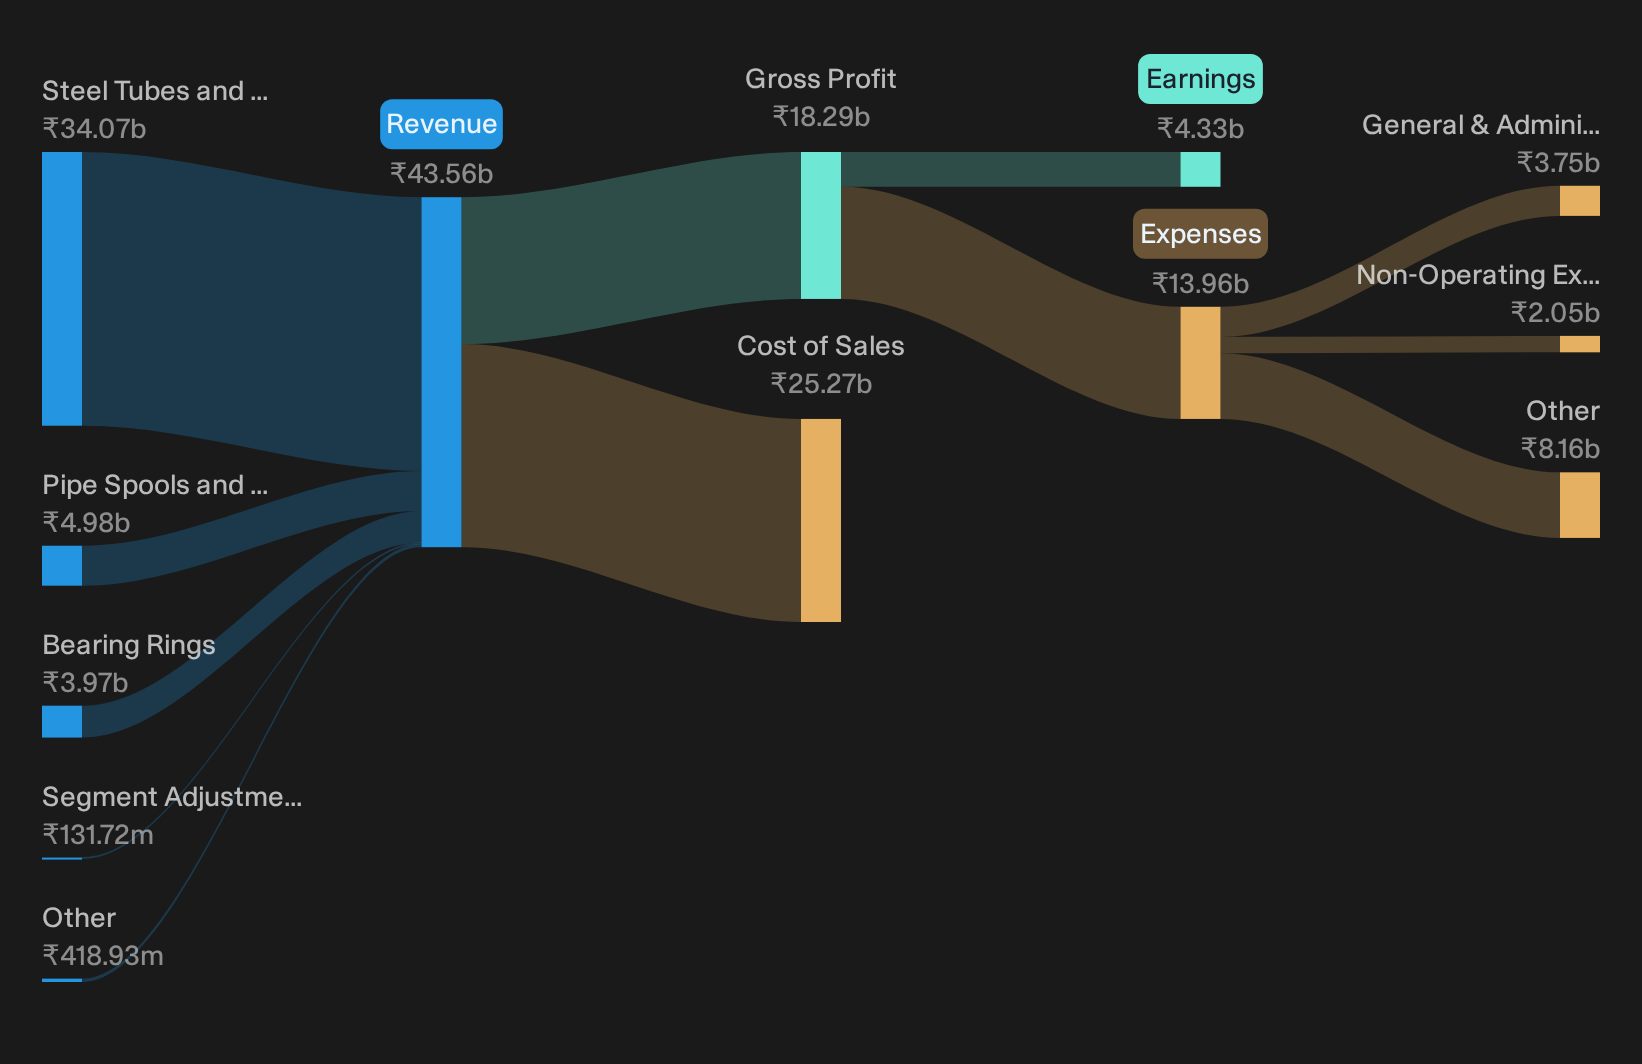
Ratnamani Metals & Tubes manufactures stainless steel and carbon steel pipes and tubes for sectors like oil and gas, LNG and nuclear energy, earning about ₹34.1b from steel tubes and pipes, ₹5b from pipe spools and support systems and ₹4b from bearing rings, underpinned by a roughly ₹195.1b market cap.
"The company is investing in specialized and high value-added products, such as setting up a cold finishing project out of India, which can increase margins and revenue from high-value export markets."
What happens to Ratnamani Metals & Tubes’ earnings profile if one pressure point in its export heavy order book shifts in the right direction will be crucial.
If that export heavy order book really turns, the full narrative for Ratnamani Metals & Tubes shows how Ratnamani Metals & Tubes’ margin mix, project risk and valuation story could be quietly accelerating.
Seeking Fresh Alternatives Beyond Today
Some of the sharpest breakouts start quietly while attention is elsewhere. Use momentum while it matters and look for fresh ideas that may still be under the radar so you can position early.
- Scan the 162 dividend fortresses to explore income workhorses curated for staying power when markets keep shifting.
- Use the 620 high quality undiscovered gems to hunt for under followed compounders curated to spotlight quality businesses before they are fully in the spotlight.
- Follow cash generative AI leaders with the 38 profitable AI stocks that aren't just burning cash, which filters for businesses where revenue and profits both matter, not just hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com