


Camtek (CAMT) Could Be 19% Below Fair Value On AI Packaging Growth
Camtek (CAMT) edged 1.07% higher in the latest session, moving against mixed semiconductor sector trading. The gain comes as investors look ahead to an upcoming earnings report that is expected to show higher EPS and revenue.
That single session move sits on top of a strong near term upswing for Camtek, with a 7 day share price return of 12.4% and a 30 day gain of 3.1%, even though the 90 day share price performance is down 9.3% from earlier levels. At the current share price of US$151.36, momentum has picked up again this month after that recent pullback. The year to date share price return of 31.05% and 1 year total shareholder return of 43.97% leave the longer track record, including a 5 year total shareholder return of 262.85%, still firmly intact.
Scan beyond Camtek's latest move and compare it with a hand picked set of semiconductor peers using the 86 AI infrastructure stocks to see how other enablers of chip manufacturing are trading.
Camtek’s sharp rebound has investors debating whether fresh optimism is tied to its inspection and metrology business or a short term shift in sentiment. The valuation picture helps sort those signals.
Most Popular Narrative: 19% Undervalued
Camtek is trading at a last close of $151.36 against a widely followed fair value narrative of $187.25. This frames the recent rebound as investors weighing how much of the AI packaging opportunity is already reflected in the price.
Accelerating demand for high-performance computing (HPC) and AI-driven applications is expanding the need for advanced packaging, micro-bump, and hybrid bonding inspection, directly growing Camtek's total addressable market and supporting multi-year revenue growth.
See why 35 investors see Camtek as 19% undervalued.
Result: Fair Value of $187.25 (UNDERVALUED)
Still, Camtek’s heavy exposure to Asian customers and rising competition from larger semiconductor equipment suppliers could quickly challenge the AI packaging-led upside that analysts are banking on.
Find out about the key risks to this Camtek narrative.
Another View on Camtek’s Valuation
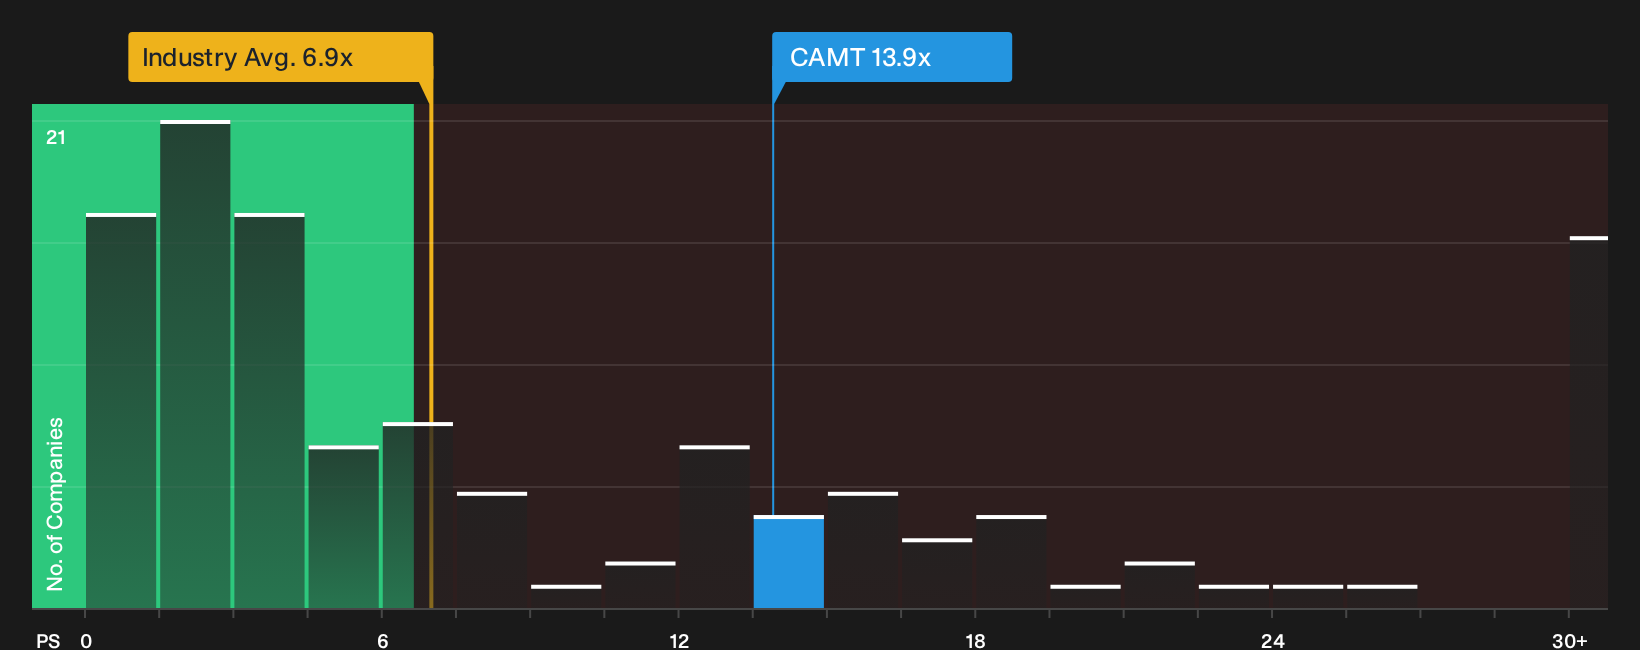
While the fair value narrative and analyst targets frame Camtek as undervalued, the pricing signal from its sales multiple tells a very different story. The stock trades at a P/S ratio of 13.9x, which is more than double the 6.8x US Semiconductor industry average and well above an estimated fair ratio of 5.8x.
That gap implies investors are already paying a steep premium for Camtek’s AI packaging potential, relative both to peers and to where the fair ratio suggests the multiple could settle over time. The question for you is simple: How comfortable are you paying that much upfront for a story that still has to be delivered?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Camtek’s valuation and growth story naturally raise questions, so review the numbers, weigh the risks against the upside, and ground your own judgment in the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Camtek?
If Camtek has you thinking harder about price, quality, and risk, use that momentum to scan for other opportunities that match your standards.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) that filters for financial strength upfront.
- Hunt for mispriced quality by using the 29 high quality undervalued stocks that highlights opportunities where fundamentals and valuation screens align.
- Focus on stability and capital preservation through the 30 resilient stocks with low risk scores that spotlights businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com