


Twist Bioscience (TWST) Joins Lilly TuneLab, Is The Stock Fully Priced?
Twist Bioscience (TWST) just tied its antibody characterization platform to Lilly TuneLab, an AI and machine learning drug discovery hub built around Eli Lilly research data and collaborating biotech users.
The Lilly TuneLab agreement comes after a powerful run in Twist Bioscience’s shares, with a 90 day share price return of 80.19% and year to date share price return of 408.18%, while the 1 year total shareholder return is very large at about 5x. Recent momentum has been strong, with a 7 day share price return of 19.19% and 30 day share price return of 13.06%, even though the latest session saw the share price slip 0.74% to close at US$164.60. Over longer horizons, the total shareholder return of about 7x over three years and 58.27% over five years signals that investors have already priced in a lot of optimism, so fresh partnerships like TuneLab tend to influence expectations around future opportunity and risk rather than reset the story entirely.
Surf ahead of the AI drug discovery wave by comparing Twist Bioscience with a curated shortlist of 37 healthcare AI stocks that are also tying their platforms to machine learning breakthroughs.Twist Bioscience now trades far above the average analyst price target, while an intrinsic value estimate sits below the market as well. After a run this steep, where does a reasonable fair value range actually land?
Most Popular Narrative: 56% Overvalued
Twist Bioscience closed at $164.60, while the most followed narrative anchors fair value at $105.30. The current quote sits well above that implied mark and focuses attention on whether AI driven demand can support such a gap over time.
Significant improvements in gross margin (now above 50%) through volume leverage, process improvements, and increased vertical integration signal ongoing margin expansion and a clear near-term path toward adjusted EBITDA breakeven, indicating robust future earnings potential.
See why 23 investors see Twist Bioscience as 56% overvalued.
Result: Fair Value of $105.30 (OVERVALUED)
Still, heavy reliance on a handful of NGS customers and ongoing losses that could require fresh capital both sit uncomfortably alongside Twist Bioscience’s stretched valuation.
Find out about the key risks to this Twist Bioscience narrative.
Another View: SWS DCF Points To Upside
While analyst narratives around Twist Bioscience cluster around a fair value of about $105, the SWS DCF model lands in a very different place. On that framework, the shares at $164.60 are tracking about 17% below an estimated future cash flow value of $199.35. This frames the recent rally as less extreme. That split between story driven targets and cash flow math leaves a simple question: Which lens do you trust more when real money is on the line?
To understand how sensitive that DCF outcome is to growth, margins, and dilution assumptions, it is worth looking at how the SWS DCF model is built Look into how the SWS DCF model arrives at its fair value.
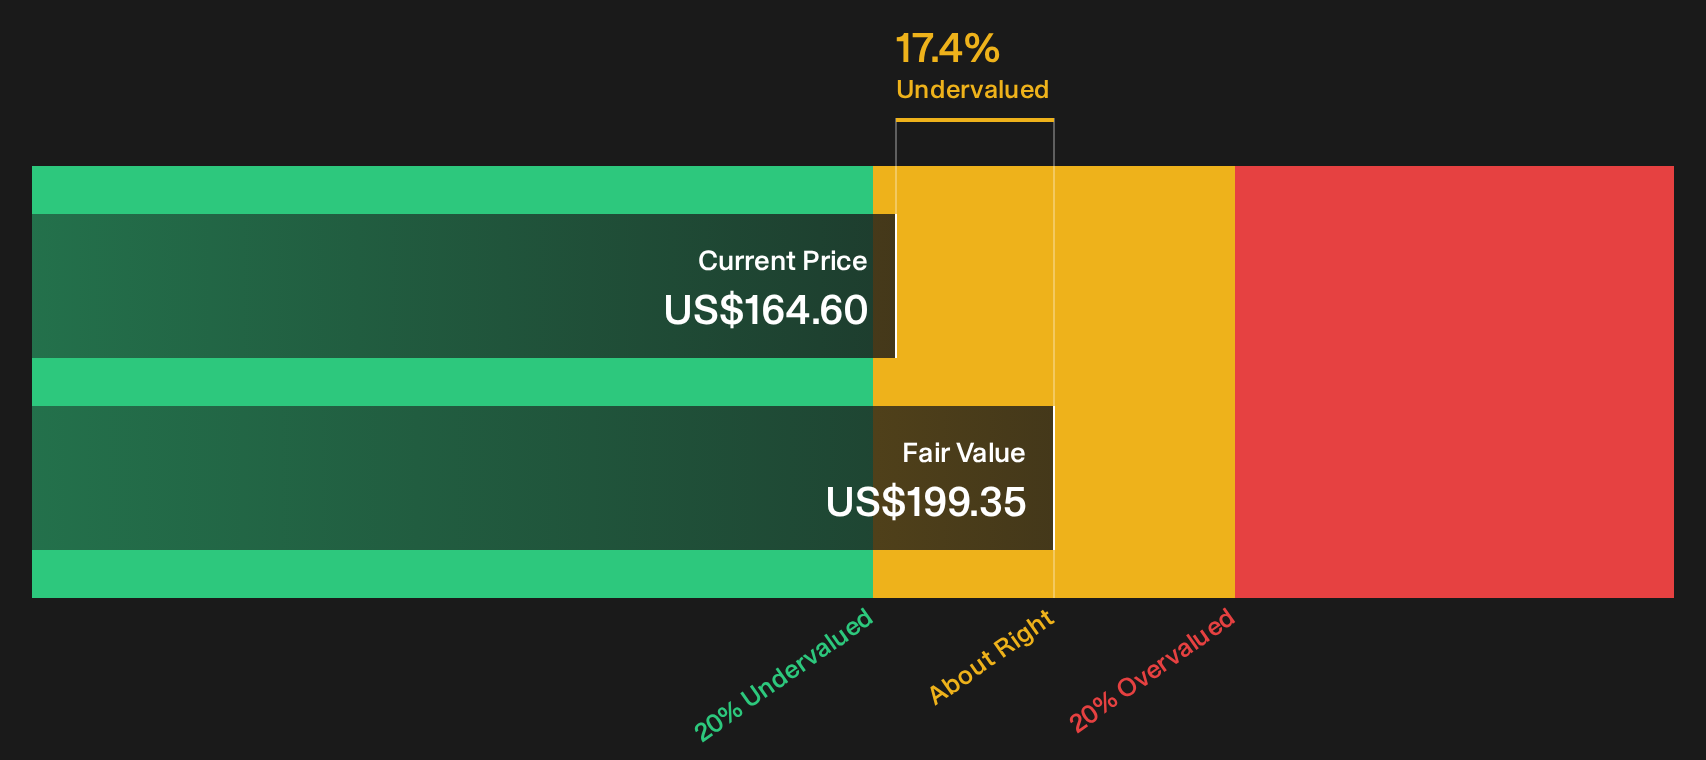
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Twist Bioscience for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big moves in Twist Bioscience often split opinion, and the latest TuneLab news is no exception. Consider acting while sentiment is this divided and anchor your own view using our breakdown of 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Twist Bioscience?
If you only watch Twist Bioscience, you risk missing other clear setups where quality, price, and timing line up in your favor across the market.
- Target resilient upside by focusing on a 30 resilient stocks with low risk scores that can help you lean toward steadier performers instead of roller coaster trades.
- Hunt for potential mispricing by scanning our 29 high quality undervalued stocks so you are not chasing crowded stories after the easy gains have gone.
- Prioritize financial strength by reviewing a list of solid balance sheet and fundamentals (23 results) and keep your watchlist stacked with companies built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com