


What Equinix (EQIX)'s Comcast Connectivity Deal Means For Shareholders
- On 10 September 2026, Comcast Business announced a collaboration with Equinix that lets enterprises order last-mile Ethernet connectivity via standards-based APIs directly within Equinix Fabric, with validation underway in live customer environments and plans to expand into optical wavelengths, cloud connectivity and cybersecurity over time.
- The move threads Comcast Business’s digital orchestration platform into Equinix Fabric, which could tighten Equinix’s grip on interconnection workflows by making third-party network access feel like an on-platform feature rather than a separate procurement step.
- We will now examine how this deeper Comcast Business integration into Equinix Fabric could influence Equinix’s broader investment narrative and execution risks.
Scan how Equinix fits into the buildout of digital infrastructure, and then size up peers riding the same trend with our curated list of 86 AI infrastructure stocks.
Equinix Investment Narrative Recap
To own Equinix, you need to believe it can keep turning dense interconnection demand and AI heavy workloads into recurring rental income while executing a multiyear build program of US$5 billion to US$7 billion annually. The Comcast Business tie-in mostly strengthens the existing Fabric story rather than changing the near-term picture in a big way.
The key swing factor still sits on the supply side. Power access, permitting and higher build costs remain the biggest execution watchpoints, because any delay in bringing roughly 600 MW under development online could push out returns. Faster, more automated last-mile provisioning may ease customer onboarding, but it does not meaningfully change those physical build risks.
The Comcast Business collaboration is the most relevant recent development for this thesis. Letting enterprises price and order last-mile Ethernet connectivity through Equinix Fabric aligns directly with the push toward usage-based interconnection services, which analysts already view as one of the faster-growing, higher-margin parts of the platform.
If Equinix successfully validates this API-based model and later extends it to optical wavelengths, cloud on-ramps and cybersecurity, Fabric could become a denser transaction hub that supports the planned multibillion-dollar development pipeline. Failure to scale these types of partnerships would not break the story, but it could limit how much incremental stickiness and utilization Equinix can squeeze out of each new megawatt of capacity.
Equinix's current analyst narrative points to US$13.5b in revenue and US$2.3b in earnings by 2029, based on an assumed 10.8% yearly revenue growth rate and an earnings increase of about US$0.8b from US$1.5b today.
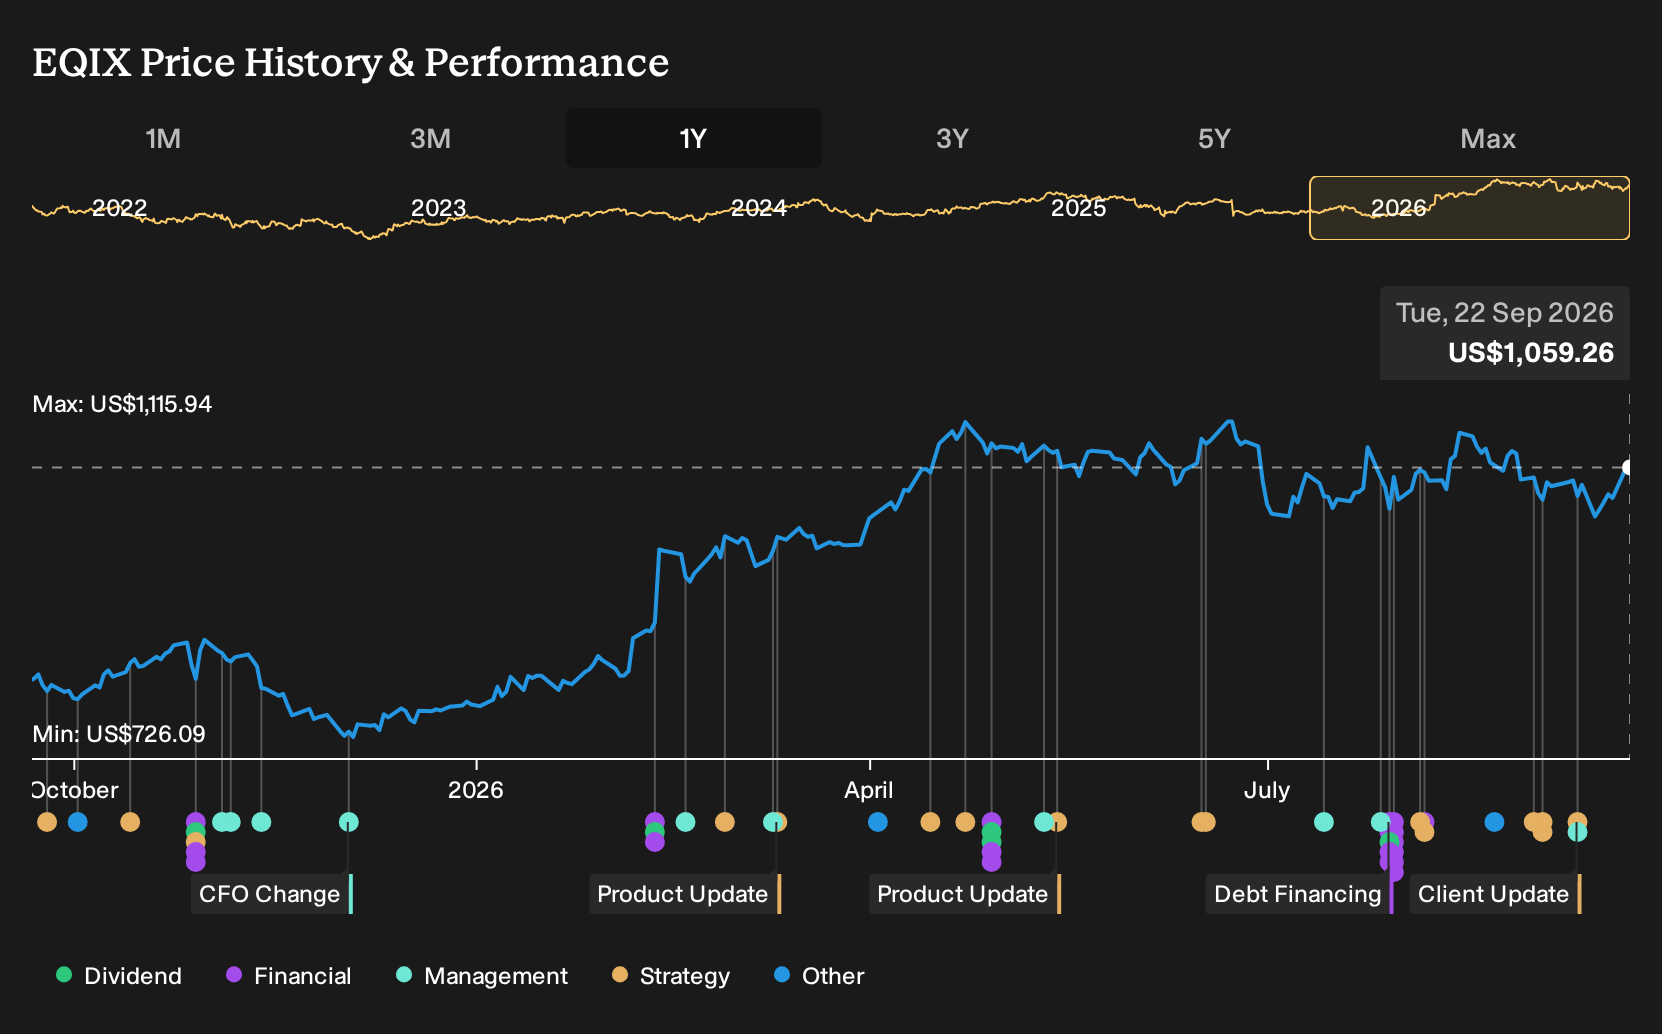
Uncover how Equinix's fair value indicates a 16% potential upside to its current price, which could narrow quickly as expectations catch up.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, views on Equinix cluster between roughly US$1,233 and US$1,635 per share, which already shows a wide gap for a single stock. You are looking at individual retail investors, not Wall Street, weighing the same buildout plans, power constraints and AI demand, then reaching very different conclusions. That spread reflects genuine disagreement on how quickly Equinix can turn grid access, new development and interconnection products into cash flow. It therefore makes sense to review several of these viewpoints before leaning too hard on any single narrative.
Explore 2 other Equinix fair value estimates, including one that suggests it could be worth just $1,233.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Equinix research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Equinix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equinix's overall financial health at a glance.
Looking For More Investment Ideas Beyond Equinix?
Once you have formed a view on Equinix, it can help to compare it with other opportunities that share some of the same qualities or offer very different risk and income profiles. The Simply Wall St Screener gives you a simple way to filter for those traits instead of starting from a blank page.
- If you want income resilience first and foremost, scan for companies that aim to combine durability with higher yields through 7 dividend fortresses.
- If capital preservation matters more than chasing maximum upside, focus on businesses that score well on stability using the 30 resilient stocks with low risk scores.
- If you prefer to hunt for overlooked opportunities with solid fundamentals, start with a curated universe of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com