


Learn Why The Bull Case For Builders FirstSource Stock Could Change Following Earnings Estimate Cuts
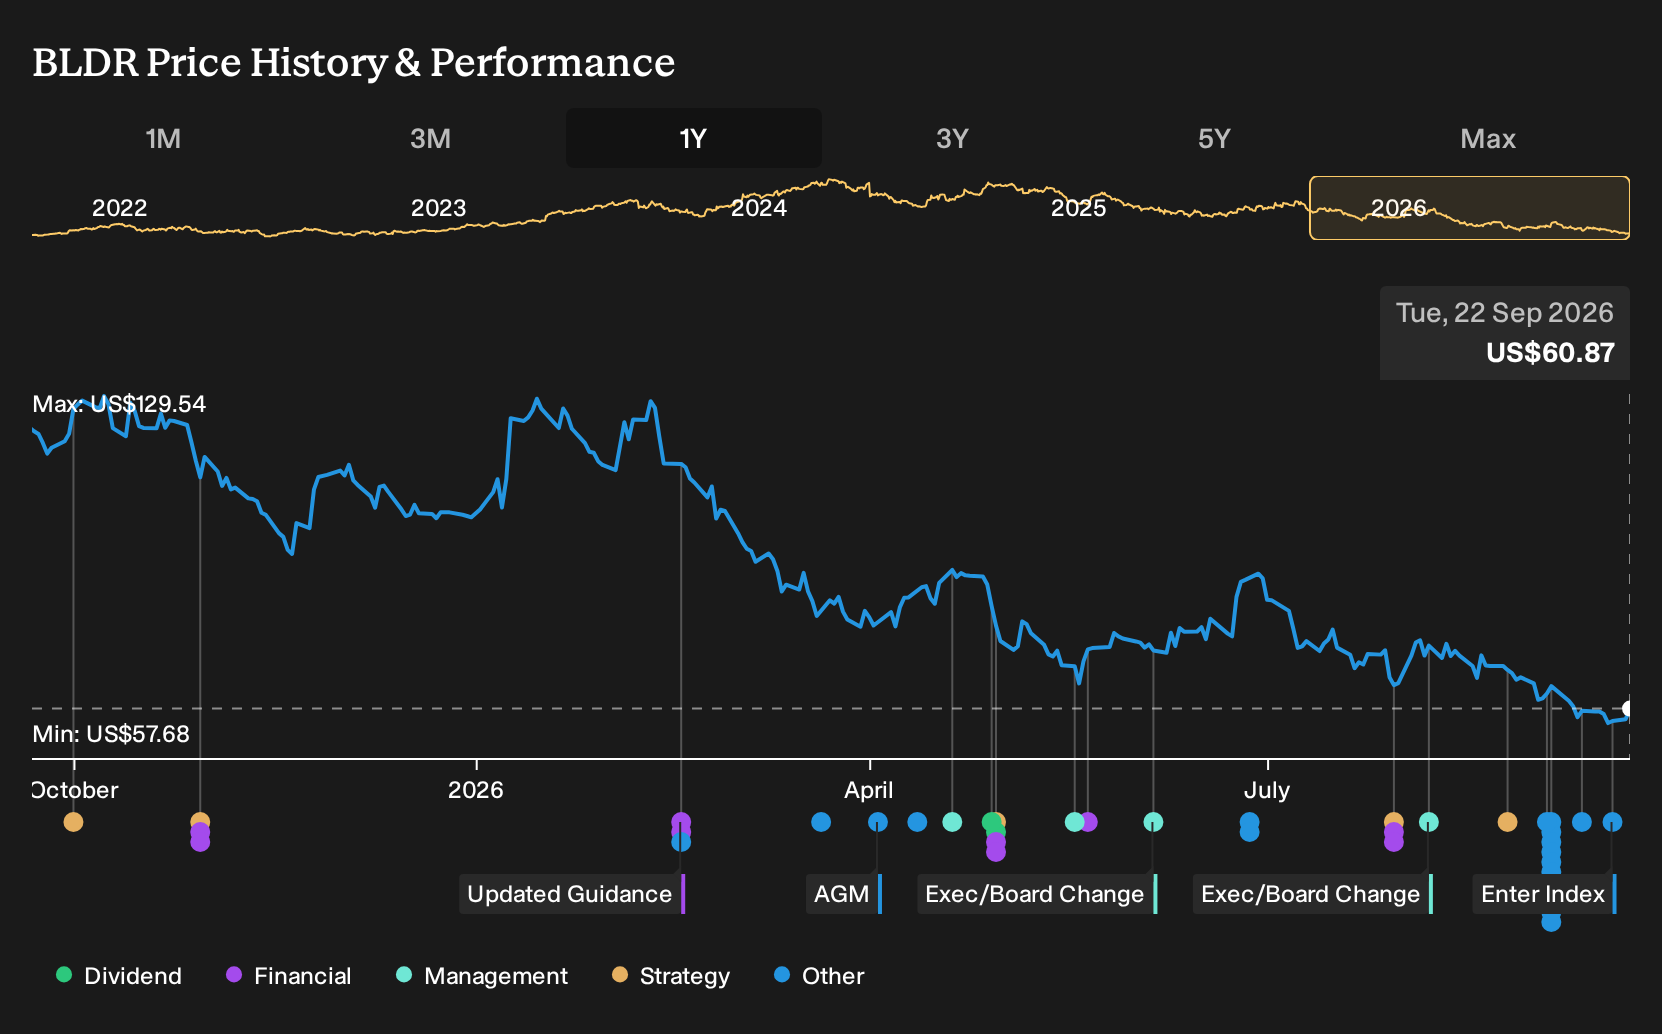
- Builders FirstSource was removed from the S&P 500 Equal Weighted Index and later added to the Russell Small Cap Comp Value Index, while earnings estimates and recent revenue trends have turned weaker.
- The combination of softer fundamentals and a Zacks Rank #5 (Strong Sell) rating suggests pressure on Builders FirstSource's near term operating outlook despite discounted valuation metrics versus peers.
- We will now look at how Builders FirstSource's investment narrative is tested by weakening earnings estimates and recent negative revenue trends.
Compare Builders FirstSource's current pressure to other potential value ideas and scan a curated 29 high quality undervalued stocks that also pair discounted pricing with solid fundamentals.
Builders FirstSource Investment Narrative Recap
To own Builders FirstSource today, you need to believe that investments in digital tools, value added components and offsite manufacturing can offset pressure from a choppy housing cycle and tighter profitability. The key near term swing factor is how quickly single family construction and repair and remodel activity stabilise, because recent revenue and margin compression leaves less room for error.
The biggest risk right now is that soft housing demand, commodity volatility and high leverage keep returns subdued while interest costs stay heavy. Index reshuffling and short term share price weakness matter less to the business than execution on cost control, pricing and adoption of its higher margin building solutions.
The recent removal from the S&P 500 Equal Weighted Index and addition to the Russell Small Cap Comp Value Index is operationally minor, but it can still affect who owns Builders FirstSource. Different benchmarks can pull in a different mix of investors, which may alter trading patterns around earnings and macro data.
For you as a shareholder, the more relevant question is whether the business can improve profitability from today’s slim 0.7% net margin and cover interest more comfortably while earnings expectations remain cautious. Index changes do not fix weaker recent revenue trends or high P/E optics, so the catalyst still rests on execution in housing, cost discipline and the build out of higher margin digital and prefabricated offerings.
Builders FirstSource's current analyst narrative points to revenues of US$16.0b and earnings of US$545.3m by 2029, based on 3.4% yearly revenue growth and an earnings increase of about US$442.8m from US$102.5m today.
Uncover why Builders FirstSource's fair value indicates a 33% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One sharp contrast comes from the bearish focus on cash generation. While the baseline discussion highlights longer term housing and margin potential for Builders FirstSource, the lowest analysts leaned on a flatter path, with revenue expectations of about US$15.3b and earnings of roughly US$425.3m by 2029. Those forecasts were set before these index changes, so opinions may shift and it is worth exploring how different scenarios might emerge.
Explore 3 other Builders FirstSource fair value estimates, including one that suggests it could be worth just $67.13.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Builders FirstSource research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Builders FirstSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Builders FirstSource's overall financial health at a glance.
Looking for more Builders FirstSource style investment ideas?
If the Builders FirstSource story has you thinking about where else discounted pricing, quality fundamentals and clear narratives might line up, it can help to widen the search beyond a single stock.
- For investors who want value plus quality, scan a curated group of companies trading on compressed valuations yet backed by solid balance sheets and earnings strength through the 29 high quality undervalued stocks.
- If resilience matters more than excitement, focus on businesses with stronger financial footing and cleaner leverage profiles using a dedicated list of solid balance sheet and fundamentals (23 results).
- For those who prefer smoother rides, concentrate on companies with lower assessed risk while still aiming for reasonable upside potential by running a targeted 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com