


Donaldson Company (DCI) Screens As Undervalued, Is The Higher P/E A Warning?
Donaldson Company (DCI) has drawn investor attention after recent price softness, with the share price down about 8% over the past month and modestly weaker over the past 3 months.
Against that softer recent stretch, the 1-year total shareholder return of 7.6% and the 3-year figure of 52.5% show Donaldson Company has still rewarded long term holders, suggesting momentum has eased lately after a stronger multi year run.
Scan how Donaldson Company compares to other industrials under pressure by reviewing our hand picked 30 resilient stocks with low risk scores with relatively resilient profiles despite recent share price softness.
Donaldson Company now trades at a meaningful discount to both analyst targets and an intrinsic value estimate after that pullback. Is the market rightly cautious, or has the selling pushed this filtration specialist too far?
Most Popular Narrative: 13% Undervalued
On the widely followed narrative, Donaldson Company screens as undervalued, with a fair value estimate of $98.80 against the recent $86.05 close, and that gap is driving much of the debate around the stock today.
Global expansion of environmental regulations and emissions standards is increasing demand for advanced filtration across industrial and transportation sectors, positioning Donaldson to achieve record sales in both Industrial Solutions and Mobile Solutions, with a direct positive impact on revenue and earnings growth in FY26 and beyond.
See why 10 investors see Donaldson Company as 13% undervalued.
Result: Fair Value of $98.80 (UNDERVALUED)
Still, the bullish Donaldson Company story can crack if Life Sciences growth keeps lagging or if tariff and input cost pressures squeeze already modeled margins.
Find out about the key risks to this Donaldson Company narrative.
Another View on Donaldson Company Valuation
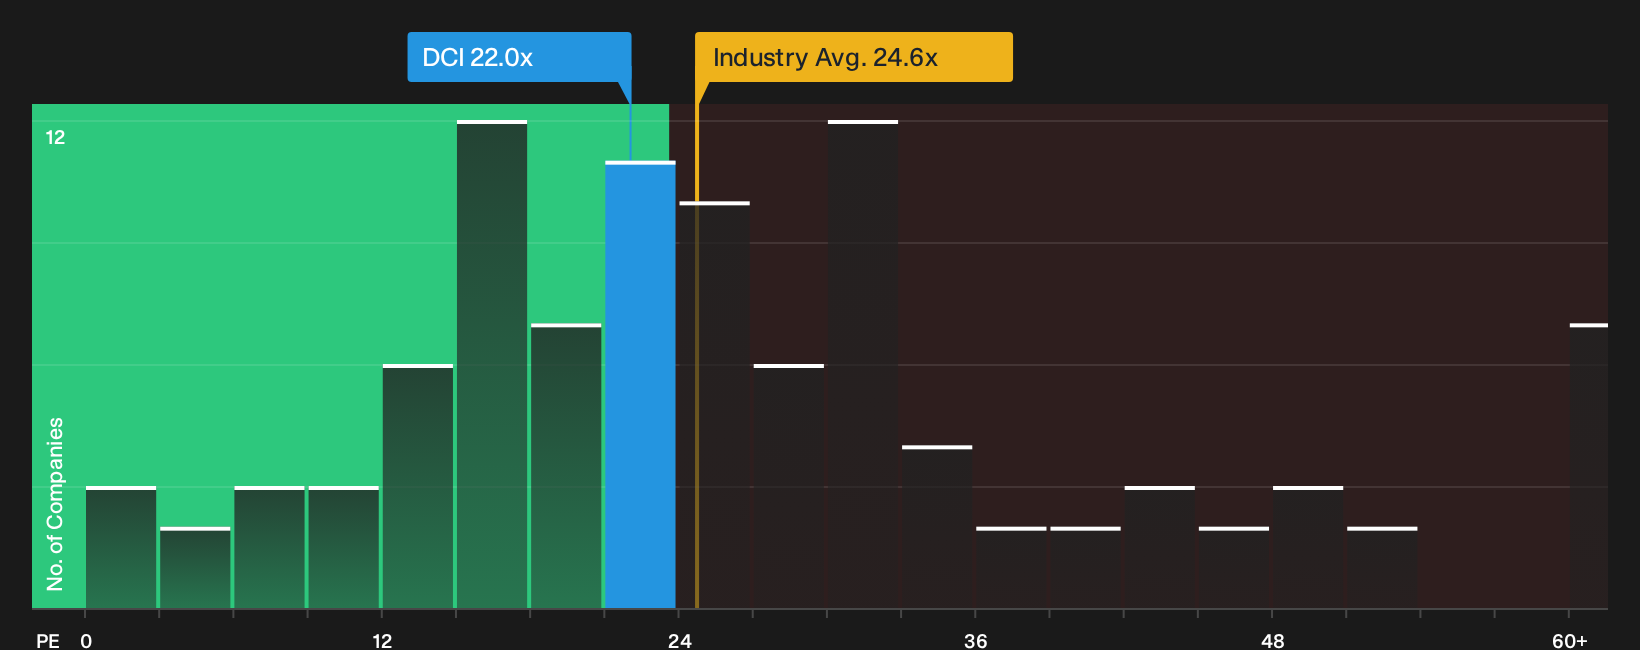
While the fair value narrative suggests Donaldson Company is about 13% undervalued, the market is sending a different signal through earnings multiples. The stock trades on a P/E of 22x, above a fair ratio estimate of 20.7x and ahead of peer levels at 18.1x. That higher multiple indicates less room for error. This raises the question: which signal would you place more weight on?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Donaldson Company is mixed, with both upside and downside angles on display. Move quickly, review the data for yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Donaldson Company?
If Donaldson Company has caught your eye, do not stop there. Use the Simply Wall Street Screener to quickly surface other opportunities that might suit your approach.
- Target strong value setups by scanning a curated 29 high quality undervalued stocks that combines quality fundamentals with potentially appealing pricing.
- Build a steadier income stream by reviewing a focused 7 dividend fortresses built around higher yields and firm cash generation.
- Prioritise financial resilience by working through a list of solid balance sheet and fundamentals (23 results) that pairs robust balance sheets with sound underlying business performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com