


FTSE All World Addition Could Be A Big Moment For MKS Stock (MKSI)
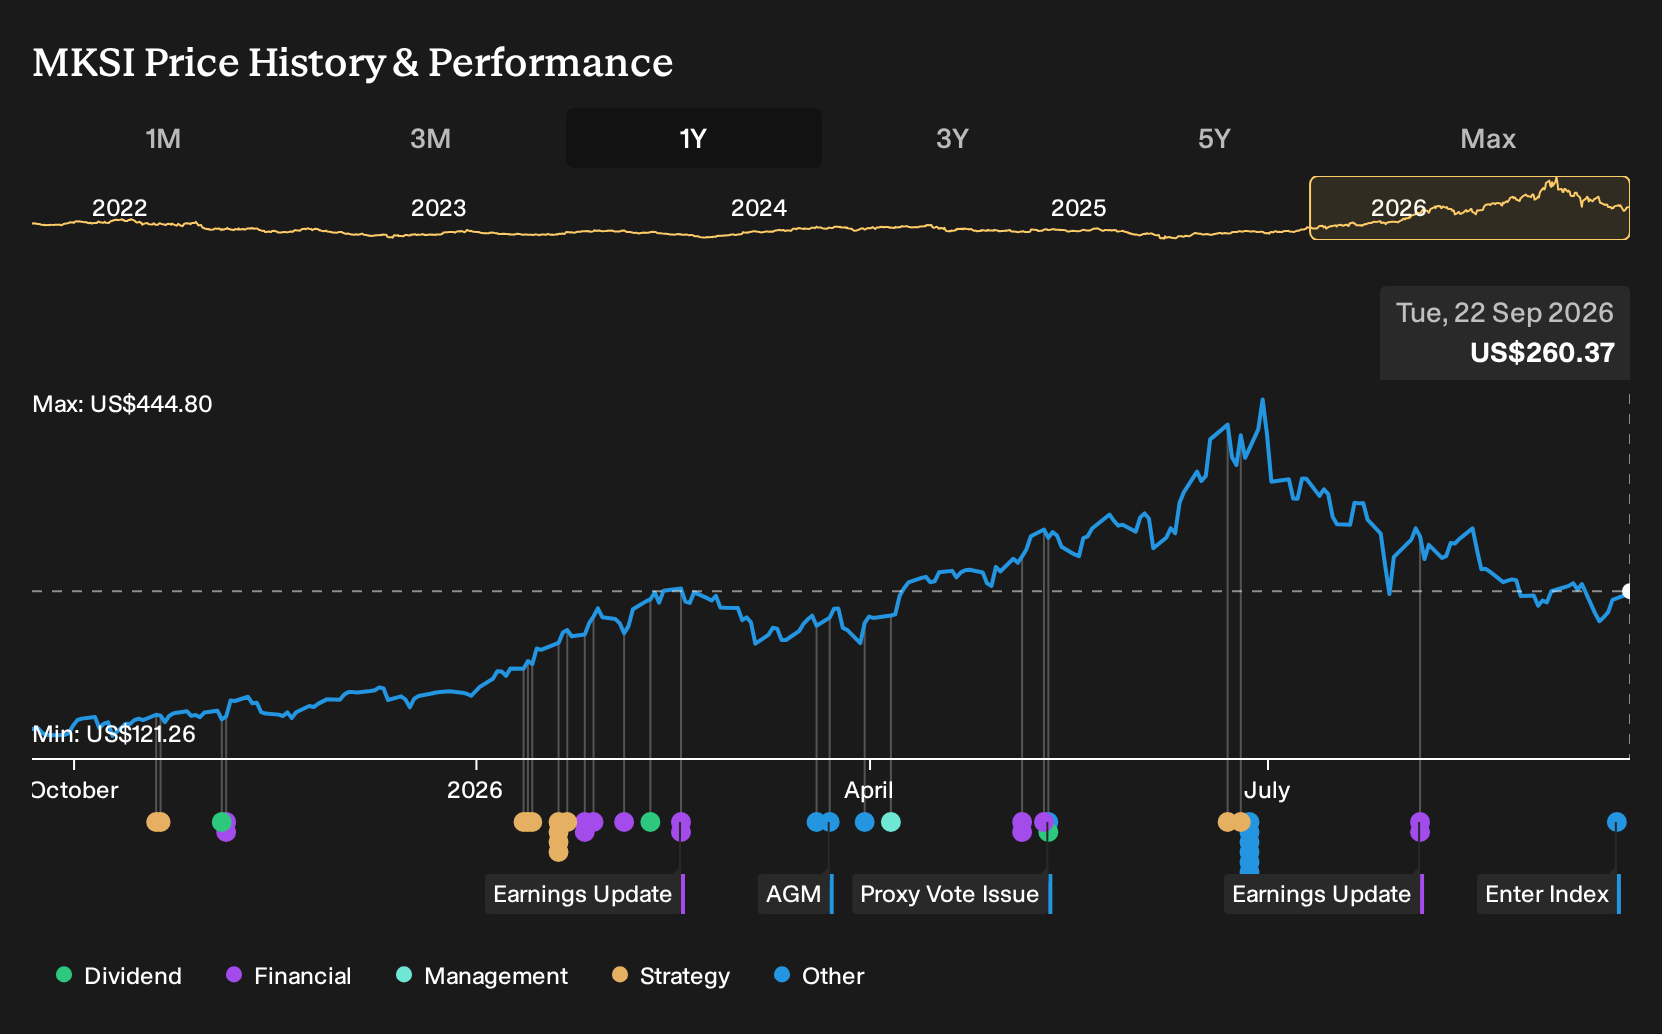
- MKS Inc. was added to the FTSE All-World Index in September 2026, increasing its formal inclusion in a major global equity benchmark.
- The index inclusion directly affects how MKS sits within benchmark-aware portfolios, since many funds track or reference this index when allocating capital.
- This article examines how MKS Inc.'s investment narrative is shaped by its new FTSE All-World Index membership and the resulting index-tracking demand.
Scan how MKS compares to other globally watched holdings and spot potential next additions to your portfolio with our curated list of list of solid balance sheet and fundamentals (23 results).
MKS Investment Narrative Recap
To own MKS, you need to be comfortable with a business tied closely to semiconductor buildouts, AI demand and complex materials processing. The near term story leans on converting that demand into higher earnings while integrating equipment and chemistry under one roof. The FTSE All World inclusion mainly influences how some funds hold the stock rather than how factories order tools or chemistry.
The bigger swing factor over the next stretch remains how well MKS converts a strong order environment into cash, given debt is not well covered by operating cash flow. The main risk stays the same. Cyclical chip spending and lumpy NAND related orders could still pressure revenue and earnings even if index driven flows add trading liquidity.
There is no other fresh corporate announcement directly tied to this FTSE All World move, which makes the index change more of a capital markets event than an operating update. That places the focus back on the company’s existing pillars, such as semiconductor equipment, advanced plating and electronics packaging exposure.
Your attention probably belongs on how MKS executes on earnings growth that analysts expect to be strong, and how effectively it chips away at leverage with free cash flow. Index inclusion does not resolve tariff exposure, customer concentration or competition in semiconductor equipment and specialty chemicals, so those remain core variables for any catalyst or setback from here.
What The Forecasts Assume For MKS
MKS' narrative projects US$7.6b revenue and US$1.7b earnings by 2029. This rests on analysts using a 20.3% yearly revenue growth rate and an earnings increase of about US$1.3b from US$439.0m today.
Uncover why MKS' fair value indicates a 60% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
One optimistic twist on the MKS story comes from analysts who see AI driven chemistry demand as the real engine. Before this index news, the most bullish forecasts already pencilled in about US$7.0b of sales and US$1.2b of earnings by 2029. You can treat today’s FTSE All World inclusion as a fresh reason to compare those upbeat assumptions with more cautious views.
Explore 3 other MKS fair value estimates, including one that suggests as much as 121% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MKS research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MKS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MKS' overall financial health at a glance.
Looking For More Investment Ideas Beyond MKS?
If this FTSE All World shift has sharpened your focus on portfolio construction, it could be a good moment to widen the lens beyond MKS and scan for businesses that better match your risk tolerance and income goals using the Simply Wall St Screener.
- For investors hunting for mispriced quality, compare MKS with other candidates that screen as potentially overlooked using our 29 high quality undervalued stocks.
- If capital preservation and steadier balance sheets matter most to you, you can filter for companies that look financially robust through the 30 resilient stocks with low risk scores.
- Income focused investors can round out their watchlist by scanning for higher yielding opportunities via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com